
Applied Digital (APLD) Rises With CoreWeave Readthrough As Fair Value Debate Returns
Applied Digital (APLD) drew fresh attention after CoreWeave reported strong third quarter results, raised its full year revenue outlook, and highlighted firm demand for AI computing infrastructure. This lifted sentiment across data center focused stocks.
Despite the positive readthrough from CoreWeave, Applied Digital’s recent price action has been volatile, with the share price falling 24.47% over the past 30 days and 45.67% over 90 days. This comes even after a strong 19.62% 7 day share price return that hints at short term momentum rebuilding off a weakened base. Over longer periods, the picture is mixed, with the year to date share price return down 39.70%, while the 3 year total shareholder return is very large. This contrasts with a 26.50% total shareholder return decline over the last 12 months and a 34.00% total shareholder return drop over five years.
Spot emerging AI infrastructure momentum alongside Applied Digital by scanning our hand picked 53 AI infrastructure stocks that are also tied to rising demand for high performance computing capacity.Applied Digital now trades far below both its recent highs and the average analyst target, creating a wide gap between price and implied worth. How much of that spread appears justified once you run the valuation math?
Most Popular Narrative: 72% Undervalued
On the analyst consensus Narrative on Simply Wall St, Applied Digital screens as materially undervalued, with a fair value of $60.94 against a last close of $16.95. That wide gap is built on long-term AI data center contracts, ambitious capacity additions, and a specific discount rate of 12.54%.
The long-term leasing agreements that Applied Digital has signed with Tier 1, investment-grade hyperscalers now total about US$36b of contracted lease value across 1.41 GW of IT load under mainly 15-year take-or-pay structures. This extends the earlier CoreWeave focused thesis into a broader, annuity-like revenue base that can support cash flow visibility and earnings quality over time.
See why 293 investors see Applied Digital as 72% undervalued.
Result: Fair Value of $60.94 (UNDERVALUED)
Still, the whole Applied Digital story leans heavily on US$6.4b of debt and a large, unfunded capacity build that could strain financing and project timing.
Find out about the key risks to this Applied Digital narrative.
Another View: Applied Digital Through A Sales Multiple Lens
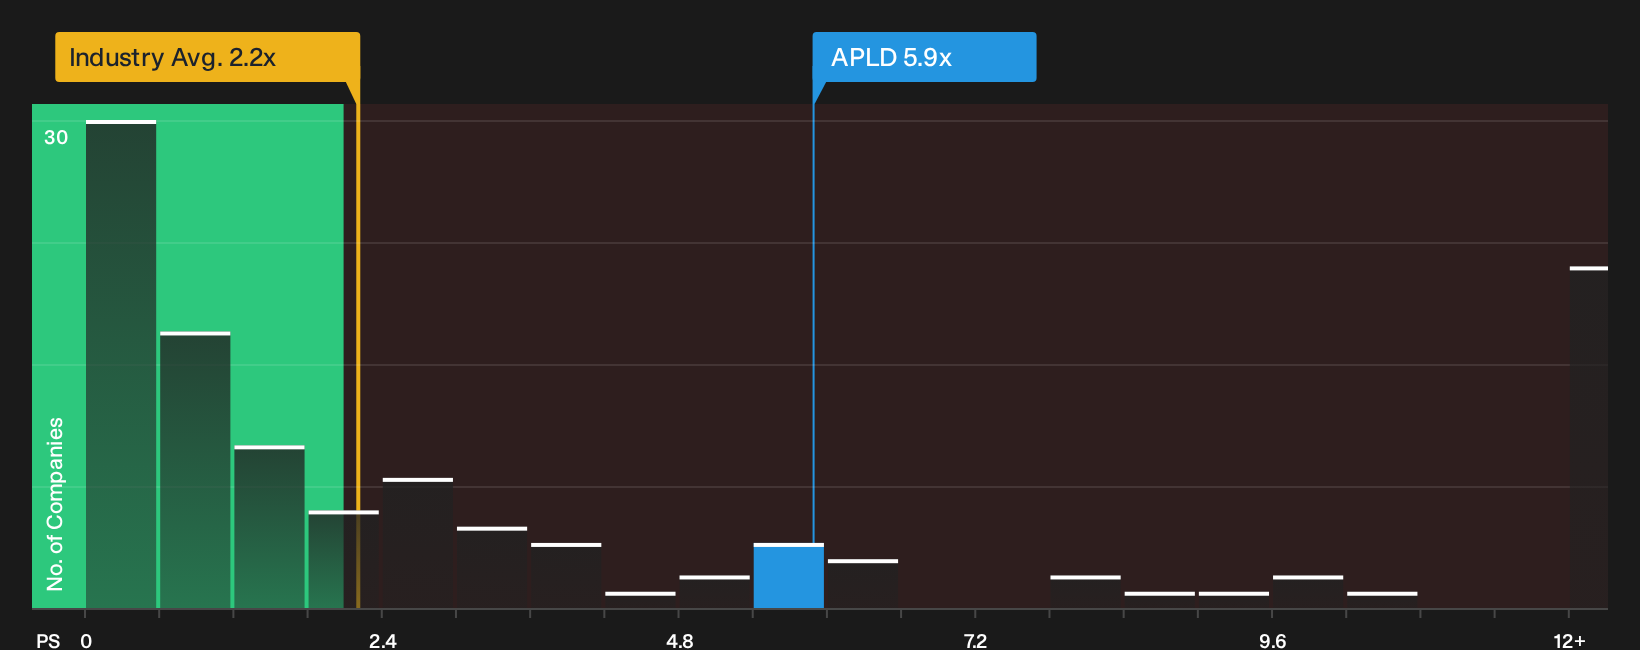
The 72% undervaluation story for Applied Digital presents a different picture when viewed through the P/S ratio. The stock trades around 5.9x sales, while both the US IT industry and its peer group are closer to 2.2x, and the fair ratio is estimated at 4.3x. That premium points to valuation risk if the business underdelivers.
Before placing too much weight on the higher sales multiple, it is worth examining how the detailed valuation breakdown compares with your own expectations for growth and funding capacity. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of investors see opportunity here, while others focus on the pressure points. Move quickly, review the full data, and weigh both sides with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Applied Digital?
If you only stop at Applied Digital, you could miss other opportunities that better match your style, risk tolerance, and income goals in minutes.
- Target potential mispricing by scanning a focused set of quality opportunities through the 32 high quality undervalued stocks.
- Strengthen portfolio resilience by reviewing a curated list of solid balance sheet and fundamentals (23 results) that can help anchor returns when conditions get tougher.
- Grow your income stream by checking out a hand picked group of 6 dividend fortresses built around higher yields and robust payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com