
Is InnovAge Holding (INNV) Undervalued After First Quarter Results And 2027 Guidance?
What the latest InnovAge Holding results tell investors
InnovAge Holding (INNV) put fresh numbers on the table on 3 November 2026, pairing first quarter results with confirmed fiscal 2027 revenue guidance of US$1,050 million to US$1,085 million.
The healthcare provider reported first quarter revenue of US$264.76 million and net income of US$19.55 million, alongside basic and diluted earnings per share from continuing operations of US$0.14.
At a share price of US$9.40, InnovAge Holding has seen its 1‑month share price return climb 4.21%, while the 90‑day move is down 11.40%. However, the year to date share price return of 81.12% and 1‑year total shareholder return of 75.37% point to momentum that has been building ahead of and around these stronger quarterly results and the confirmed 2027 revenue guidance.
Scan beyond InnovAge Holding and see how it compares to other healthcare operators with strong balance sheets and fundamentals using our curated list of solid balance sheet and fundamentals (23 results).
After an 81% gain year to date and confirmed 2027 revenue guidance on the table, the real puzzle for InnovAge Holding investors now is simple: Is most of the upside already booked, or not yet priced in?
Most Popular Narrative: 22% Undervalued
Against the last close of $9.40, the analyst consensus Narrative on Simply Wall St anchors InnovAge Holding at a fair value of $12.00 based on its modelled cash flows and earnings path. That gap frames the latest results as one part of a longer profitability story rather than a one quarter surprise.
Operational transformation initiatives, including technology investments, cross functional efficiencies, and the integration of in house pharmacy and clinical services, are actively reducing per participant costs and are now reflected in higher center level contribution margins. This supports further improvement in net margins and earnings.
Enhancements in clinical management and care delivery, including tighter control of external provider use and pharmacy expense that have already contributed to lower external provider cost per participant, create room to apply similar care protocols and tools more broadly across the census. This can support future gains in medical cost ratio and adjusted EBITDA margins.
See why 2 investors see InnovAge Holding as 22% undervalued.
Result: Fair Value of $12 (UNDERVALUED)
Still, the story around InnovAge Holding can change quickly if external provider and pharmacy costs flare up again or if fiscal 2027 guidance proves too optimistic.
Find out about the key risks to this InnovAge Holding narrative.
Another View: What InnovAge Holding’s P/E Is Telling You
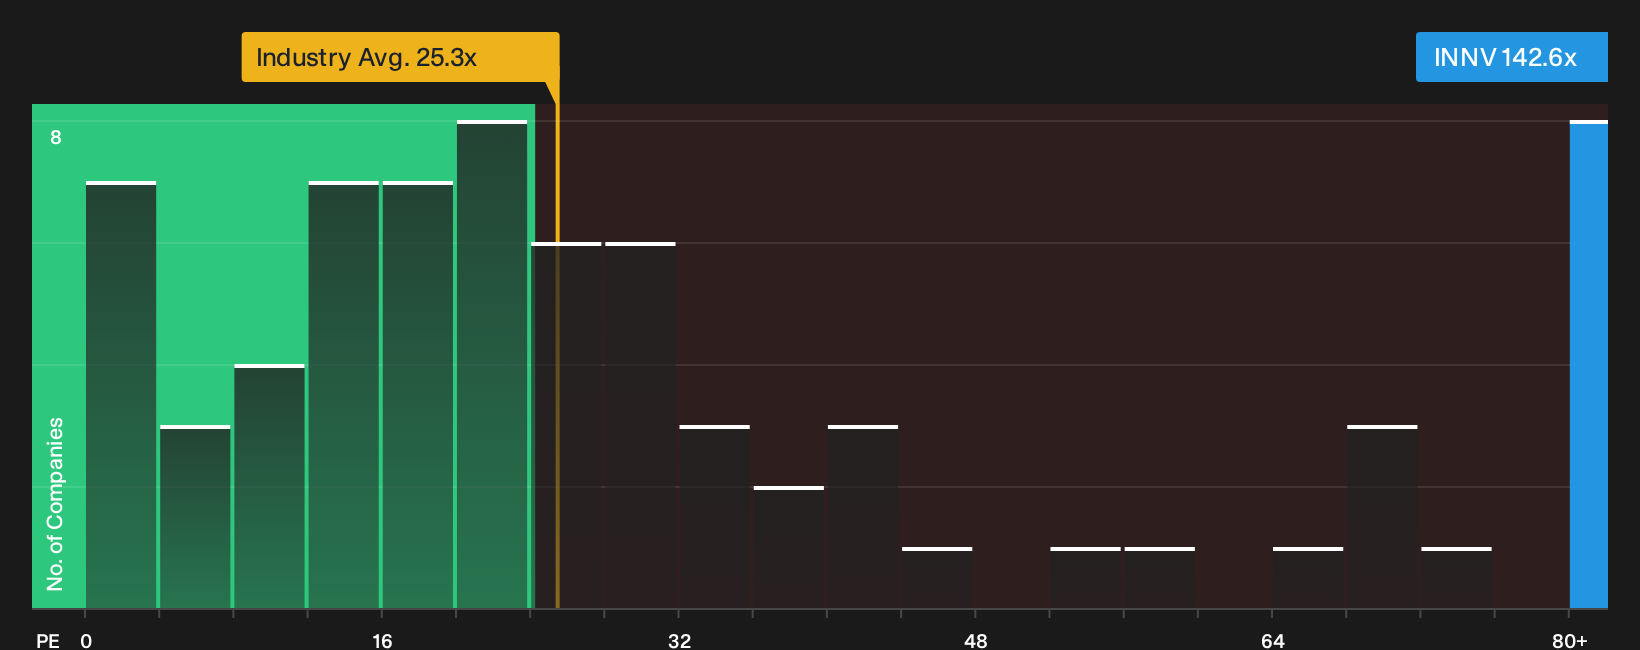
The first take frames InnovAge Holding as undervalued using a cash flow lens, yet the P/E ratio paints a sharper picture of the risk side. At about 142.6x earnings, the stock trades far above the US Healthcare sector on 25.3x and a peer group at 40.6x, and even more richly than a fair ratio of 63.6x that the market could move towards. If the multiple drifts closer to those levels while the business simply tracks expectations rather than outperforms, how much room is left for error on the story you are buying today?
Investors who lean on earnings multiples rather than cash flow models can stress test their own view using our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
To see where that P/E gap versus healthcare peers actually shows up in charts, review the latest ratio snapshot in
Next Steps
If the mix of optimism and caution around InnovAge Holding feels finely balanced, consider reviewing the data promptly before sentiment shifts. To see what investors are focused on in the current setup, start with the 3 key rewards.
Looking for more investment ideas beyond InnovAge Holding?
If InnovAge Holding sharpened your focus, do not stop there. Broader opportunity often sits just outside the first stock that caught your attention.
- Target resilient balance sheets and robust cash flows by scanning companies through the list of solid balance sheet and fundamentals (23 results).
- Hunt for quality trades that the market has not fully priced by reviewing the 20 high quality undiscovered gems.
- Prioritise sleep at night holdings by checking out the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com