
Lumexa Imaging Holdings (LMRI) Stock Looks Fully Valued Despite Reiterated 2026 Guidance
Lumexa Imaging Holdings has rallied sharply over the past month, which puts a spotlight on whether the current valuation can be backed up by its sales base. With the share price moving this quickly, the key issue for you is how much underlying revenue performance can reasonably justify where Lumexa Imaging now trades.
- The stock has gained 40.8% over the past month, putting recent momentum front and center as you weigh how much sales strength is already reflected in the price.
- Recent updates from Lumexa Imaging on expanding advanced imaging modalities and new center openings may support expectations for higher future revenue and potentially different sales productivity per site than in the past.
- There is a second opinion on Lumexa Imaging Holdings worth weighing. See what analysts think Lumexa Imaging Holdings's shares could be worth.
The issue now is whether Lumexa Imaging's current share price around US$14.94 can be sensibly explained by the level and trajectory of its sales alone.
If you are weighing Lumexa Imaging Holdings against other healthcare names that are screened for balance sheet strength and fundamentals, it can help to compare it with the solid balance sheet and fundamentals stocks screener (23 results).
Does Lumexa Imaging Holdings Look Pricey on Sales?
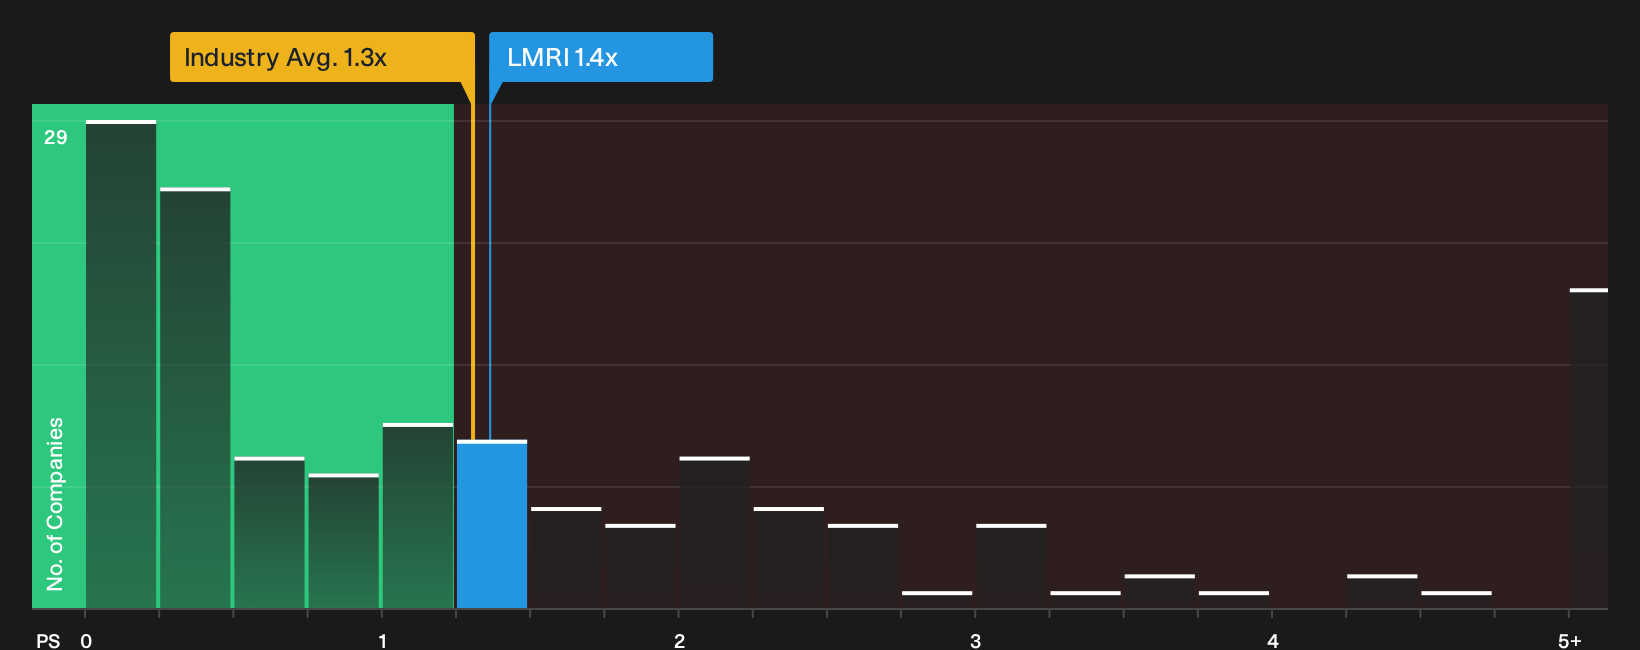
P/S fits Lumexa Imaging Holdings because the business is being valued largely on its revenue footprint rather than current earnings. From this perspective, the stock trades on a P/S of about 1.4x, which is slightly above both the wider Healthcare sector at roughly 1.3x and the peer group closer to 1.2x. That places the valuation on the richer side of the pack for each dollar of sales.
Management recently reiterated 2026 revenue guidance and adjusted its profit outlook. Despite that support for the top line, the current P/S screens as overvalued relative to the Fair Ratio implied by the broader fundamental model. The Fair Ratio reflects what investors might usually pay for Lumexa Imaging's mix of growth profile, margins, business risks and market size, so the current premium suggests the recent share price strength already builds in a healthy degree of optimism around future execution. Explore the numbers behind Lumexa Imaging Holdings's P/S valuation.
The Lumexa Imaging Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Lumexa Imaging Holdings valuation puzzle leaves off. They spell out which combinations of future growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than today, and they treat Lumexa Imaging Holdings' fair value as a clear thesis about the business that you can watch over time, rather than a one-off snapshot on a single date.
On Lumexa Imaging Holdings, the bullish and bearish Narratives both lean on the same business model, yet they read very differently on how much is already priced in.
Bull case: 34% undervalued
This view, from the bullish analyst Narrative on Simply Wall St, leans on mix upgrade, pricing power and cash generation to support the upside.
"System-wide same-site revenue growth of 4.4% in Q2 2026, split evenly between volume and rate, points to underappreciated pricing power as Lumexa Imaging Holdings renews contracts and expands higher value services..."
Discover why this Narrative puts Lumexa Imaging Holdings at 34% undervalued.
Bear case: 15% overvalued
The bearish analyst Narrative on Simply Wall St focuses on reimbursement pressure, heavier capital spending and tighter JV economics as potential brakes.
"While free cash flow conversion has been strong so far in 2026, the step up in second half capital spending to US$9.7 million in Q2 and US$14.2 million in Q3, compared with a typical US$5 million to US$7 million per quarter, raises the bar for new de novo centers, equipment upgrades and targeted M&A to perform..."
Explore why this Narrative puts Lumexa Imaging Holdings at 15% overvalued.
One more angle on Lumexa Imaging Holdings that is easy to miss
There is a separate thread worth pulling on with Lumexa Imaging Holdings, which is how professional analysts currently map out its revenue and earnings profile a few years from now, and how that compares with where the shares trade today. Explore where analysts expect Lumexa Imaging Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com