
Amneal (AMRX) Stock Looks Above Fair Value As Its 397% Run Continues
Amneal Pharmaceuticals has delivered a striking share price run in recent years, which naturally puts the focus on whether the current level is still backed by the earnings the business is producing. After such a move, the key issue for you is how much of Amneal’s profit power is already reflected in the stock.
- Over the past 3 years the stock has returned about 4x, which puts real pressure on its earnings to keep justifying this kind of market value.
- Management has raised longer term earnings expectations as new products and an expanded portfolio feed into profit forecasts, which can feed directly into how much investors are prepared to pay for each dollar of income.
- There is a second opinion on Amneal Pharmaceuticals worth weighing. See what analysts think Amneal Pharmaceuticals's shares could be worth.
The issue now is whether Amneal Pharmaceuticals' current share price is adequately explained by its earnings when judged against the Fair Ratio benchmark.
If you want more context around whether Amneal Pharmaceuticals' earnings power justifies this kind of move, it can help to line it up against other 32 high quality undervalued stocks.
Is Amneal Pharmaceuticals Getting Expensive on Earnings?
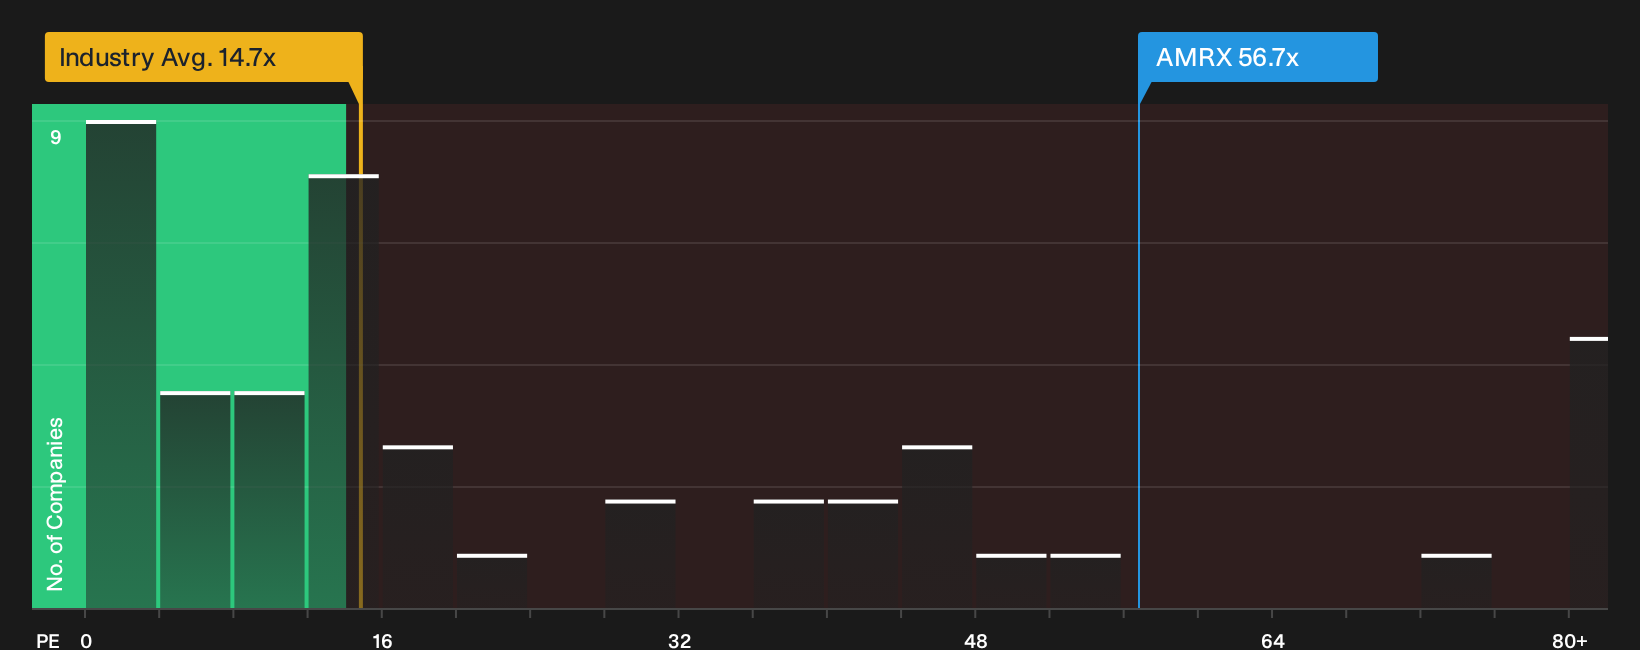
The P/E ratio fits Amneal Pharmaceuticals because earnings are now a central reference point for how investors value the business. The current P/E sits around 56.7x, which is well above the Pharmaceuticals sector average of roughly 14.7x and also above the peer group at about 48.0x. On Simply Wall St’s Fair Ratio framework, which looks at what multiple might suit Amneal’s mix of growth, profitability, size and risk, the present P/E sits higher than the level that model would usually attach to this profile.
Because management recently raised 2026 earnings guidance after a strong Q3, the market appears willing to pay a richer price for each dollar of profit. However, that optimism already shows up in this elevated earnings multiple. For you as a shareholder or prospective buyer, the key question is whether Amneal Pharmaceuticals can keep delivering the kind of earnings path that would make a premium P/E look justified compared with both its sector and its closest peers. Explore the numbers behind Amneal Pharmaceuticals's P/E valuation.
The Amneal Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Amneal Pharmaceuticals leaves off by explaining which combinations of future growth, profitability and earnings paths would need to occur for the stock to appear meaningfully cheaper or more expensive than it does today. Each idea on the Community page links its number to a clear view on how Amneal Pharmaceuticals' revenue mix, margins and risk profile might change, so you can revisit those assumptions as new results and guidance are released.
Views on Amneal Pharmaceuticals split between complex generics and specialty upside on one side and execution and capacity risk on the other.
Bull case: 6% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St.
"Management is targeting an additional US$1b to US$2b of Affordable Medicines revenue by 2030, which directly targets higher value revenue growth..."
Discover why this Narrative puts Amneal Pharmaceuticals at 6% undervalued.
Bear case: 8% overvalued
This view comes from the bearish analyst Narrative on Simply Wall St.
"Plans to triple capacity in estrogen and lidocaine patches, expand sterile injectables in the U.S. and lift CapEx from about US$110 million to about US$150 million introduce heavier fixed cost commitments..."
Explore why this Narrative puts Amneal Pharmaceuticals at 8% overvalued.
One more Amneal Pharmaceuticals check that belongs beside the earnings multiple
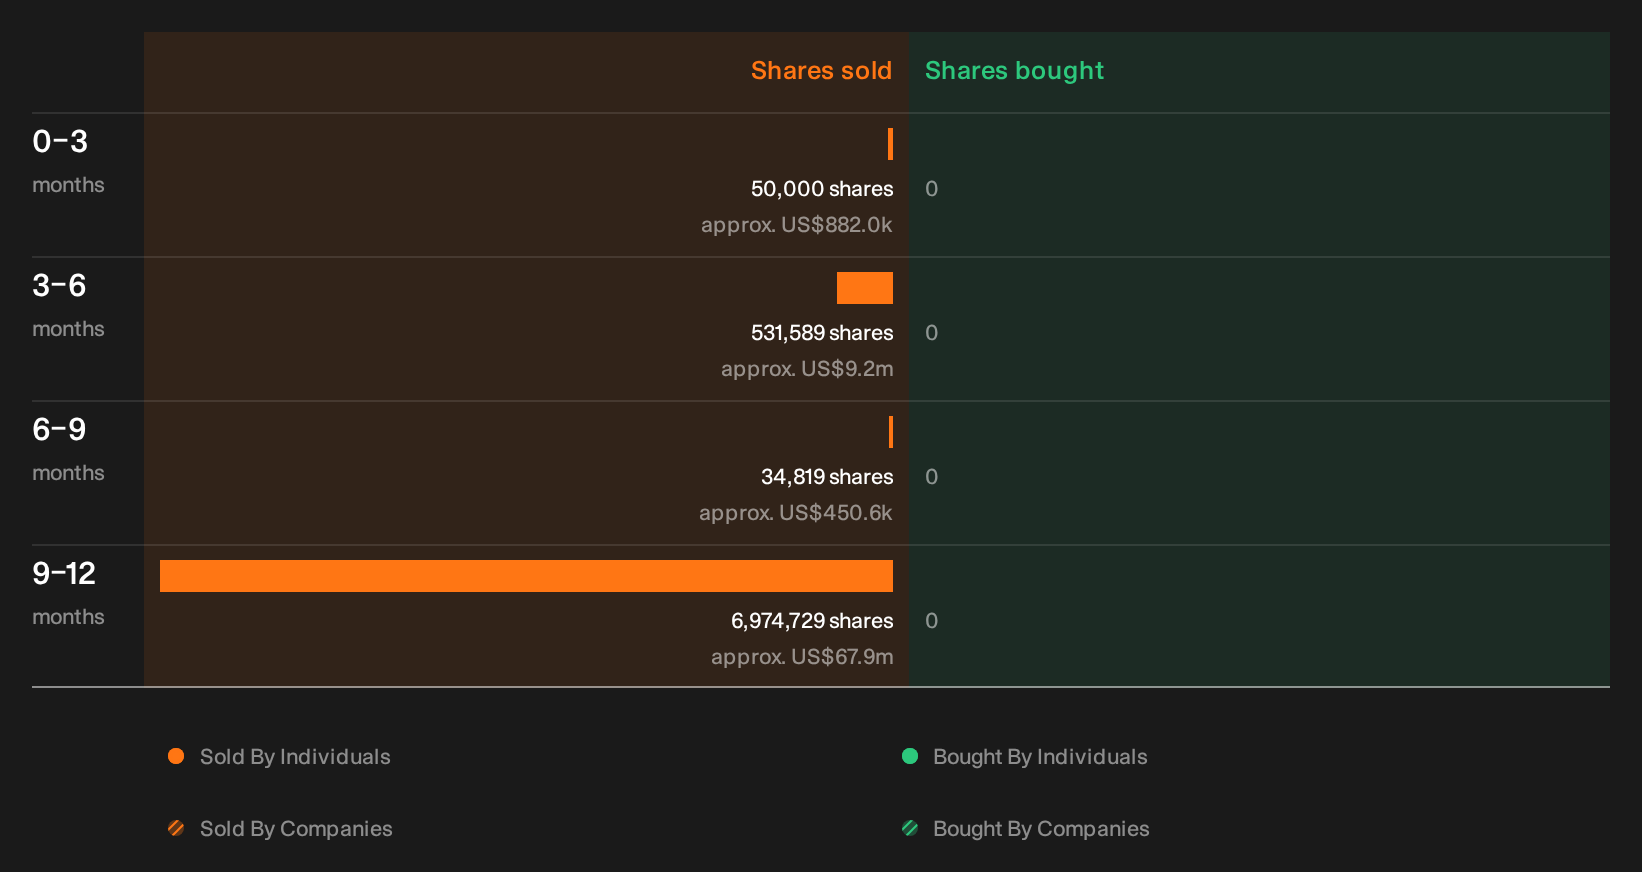
Before you get comfortable with any valuation view on Amneal Pharmaceuticals, it is worth knowing that our checks have picked up recent insider share sales, with who sold, how much, and what it could signal still for you to review. See the recent insider selling flagged for Amneal Pharmaceuticals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com