
NetApp (NTAP) Wins Nebul For Novus, Is The Stock Still 12% Undervalued?
Why Nebul’s Novus Adoption Matters For NetApp
Nebul’s move to adopt NetApp (NTAP) Novus as the storage backbone for its Intelligent Cloud puts a fresh spotlight on NetApp’s role in high throughput, GPU heavy infrastructure.
The deal centers on Novus, now generally available and built on ONTAP software. It is designed to let Nebul scale performance, capacity and concurrency separately while keeping data governance consistent across sovereign cloud environments.
NetApp’s recent Nebul win comes at a time when momentum is mixed, with the share price slipping 22.15% over the past month while still showing a 74.77% year to date share price return and a 72.39% 1 year total shareholder return that reflects strong longer term enthusiasm.
See how other AI infrastructure players compare with NetApp by running the curated 53 AI infrastructure stocks alongside this Nebul Novus deal.
NetApp now trades at a double digit discount to both its average analyst target and one intrinsic value estimate after the Nebul Novus announcement. Where does a reasonable fair value band actually land in that gap?
Most Popular Narrative: 12% Undervalued
NetApp’s last close at $186.08 sits below the analyst consensus Narrative fair value of $211.69. The analyst consensus Narrative on Simply Wall St derives this figure from detailed revenue, earnings and discount rate assumptions rather than a simple multiple comparison.
Expansion of NetApp''s AI ready storage and software platform, including Novus for large AI factories and the pending acquisition of PEAK:AIO alongside recent purchases like DataPelago and JetStream, is aimed at higher value AI and cyber resilient workloads and can support higher gross profit dollars and operating margin as these offerings are commercialized.
See why 58 investors see NetApp as 12% undervalued.
The Narrative applies an 8.63% discount rate to those forecast cash flows. This is a key input behind the $211.69 figure and reflects how analysts are weighing NetApp’s AI related deal flow, Public Cloud margins and capital return plans against risks such as component costs and inventory.
That same view frames the current analyst consensus price target of $211.69 as implying that much of the expected FY27 revenue, EPS and operating margin profile is already in the share price. Any future rerating would therefore lean heavily on execution in AI storage, cloud partnerships and cost control.
Result: Fair Value of $211.69 (UNDERVALUED)
Still, rising component costs that pressured product gross margin in Q1 FY27, along with the sharp inventory build, could quickly challenge this NetApp upside story.
Find out about the key risks to this NetApp narrative.
Another View On NetApp’s Valuation
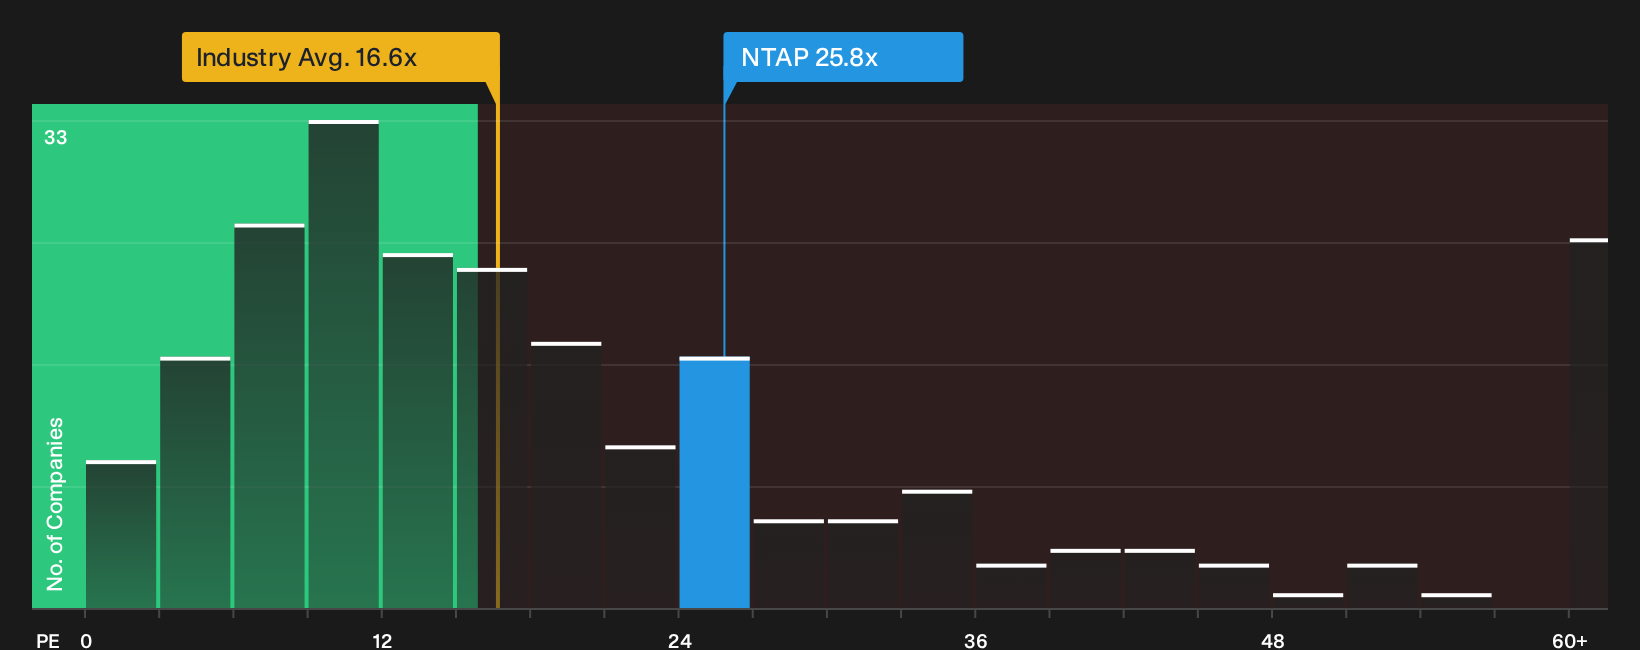
The narrative fair value pegs NetApp at $211.69 and labels the stock undervalued, yet the current P/E of 25.8x is higher than the Global Tech average of 16.6x and very close to its fair ratio of 26x. That mix of discount on future cash flows and full pricing on earnings leaves a simple question: Which signal would you trust more if sentiment weakens?
For a closer look at how our earnings based view lines up against a cash flow driven approach, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and concern around NetApp leaves you unsure, act promptly, review the numbers yourself, then weigh up the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond NetApp?
If NetApp has sharpened your thinking on valuation and execution, do not stop here. Use fresh screeners to surface other opportunities that match your criteria.
- Target durable balance sheets by scanning a list of solid balance sheet and fundamentals (23 results) that filters for companies with financial foundations that can better handle shocks.
- Hunt for strong companies at appealing prices by reviewing a curated 32 high quality undervalued stocks that focuses on quality and fundamentals.
- Lock in income focused ideas through a 6 dividend fortresses built to highlight higher yielding stocks with supporting data on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com