
Is Nintendo (TSE:7974) Below Fair Value After Record Zelda Sales And Switch 2 Bundles?
Nintendo stock: why the recent headlines matter for investors
Nintendo (TSE:7974) is back in focus after The Legend of Zelda Ocarina of Time remake set a Switch 2 launch sales record and new Black Friday hardware bundles were announced.
The Zelda remake headlines and Black Friday bundles come against a mixed backdrop for Nintendo. The stock has climbed 4.78% on a 1 month share price return and gained 28.92% on a 3 year total shareholder return, yet it is down 19.60% on a year to date share price return and 35.50% on a 1 year total shareholder return. This suggests that early momentum may be building again after a tougher recent stretch for holders.
Scan beyond Nintendo and see which gaming and media stocks our analysts have surfaced in the 74 high quality undiscovered gems.
Recent gains, a weaker year to date and record Switch 2 game sales put Nintendo in an awkward middle ground. Is it worth committing at ¥8,563 now, or is it better to wait for a clearer valuation cushion?
Most Popular Narrative: 11% Undervalued
Nintendo closed at ¥8,563, while the most followed valuation story on Simply Wall St pegs fair value at ¥9,615.72, which implies an 11% gap that the market has not closed yet according to this view.
According to richard_53rym, an investor in the Simply Wall St Community who wrote the narrative, Nintendo’s current positioning in consoles and pricing power could be a key reason that estimate sits above the market price.
Nintendo currently holds a competitive advantage because the unit price of the switch 2 undercuts the steam deck significantly. Apparently supplier arrangements have secured the supply of LPDDR5X 12 gb modules.
See why 10 investors see Nintendo as 11% undervalued.
That narrative leans on a simple idea. If Nintendo can keep hardware at a relatively low entry price while managing component supply tightly, then margins and ecosystem spending on games and services could justify a higher valuation than today’s share price implies.
The same author flags risks that investors should not gloss over. A weaker software slate in 2026, questions about how many casual players will actually move to Switch 2, and future competition from consoles like a potential PlayStation 6 are all mentioned as potential brakes on that fair value estimate if they play out differently than expected.
Result: Fair Value of ¥9,615.72 (UNDERVALUED)
Still, the absence of GTA VI on Switch 2 and a weaker 2026 software slate could quickly challenge that underpriced Nintendo narrative if player engagement softens.
Find out about the key risks to this Nintendo narrative.
Another view on Nintendo’s valuation
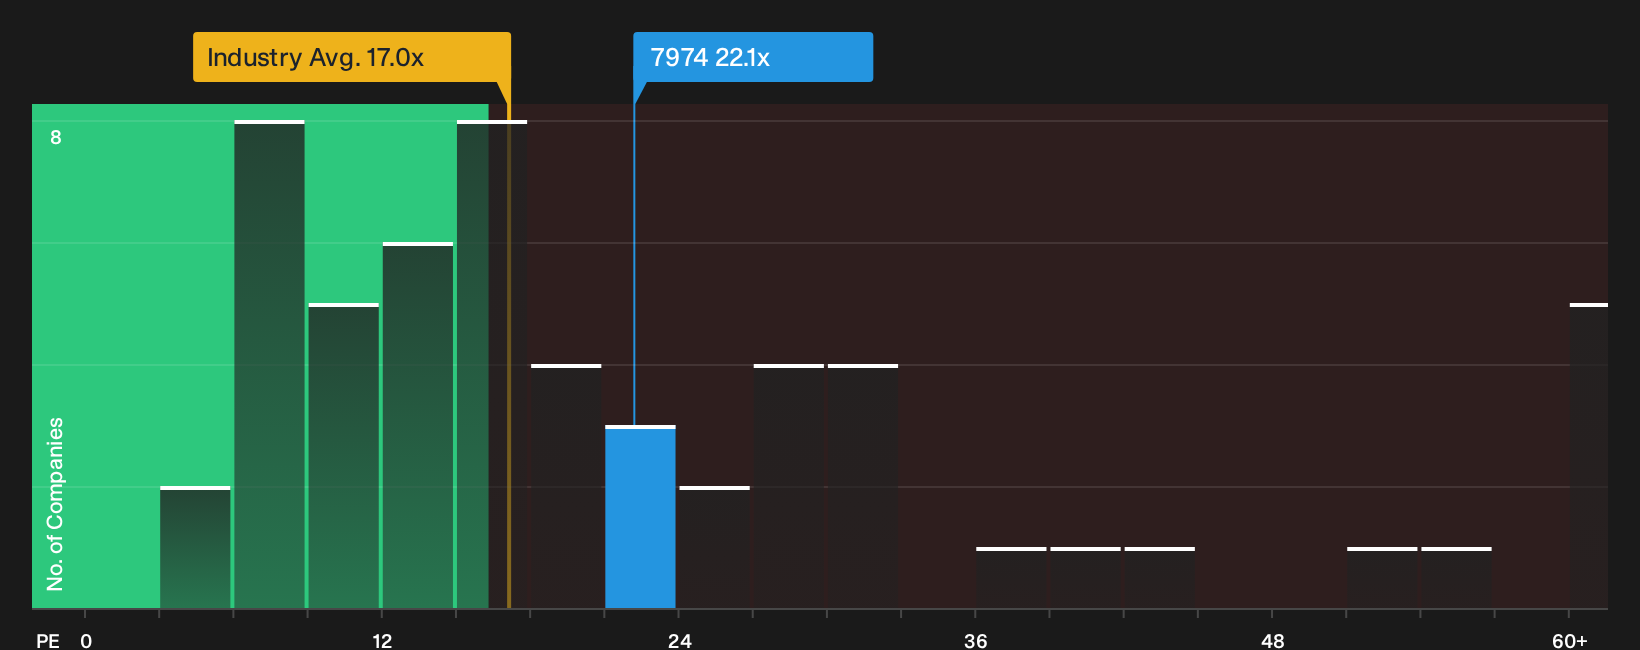
The community story paints Nintendo as 11% undervalued at ¥9,615.72, yet the market is also putting a rich price on current earnings. The stock trades on a P/E of 22.1x compared with 17x for the JP Entertainment group, while peers average a higher 24.8x and the fair ratio model points to 26.8x.
That mix of a premium to the wider industry but a discount to peers and the fair ratio leaves you weighing valuation risk against possible upside if sentiment shifts. For an investor deciding what to do at ¥8,563, the key question is which reference point matters more in practice.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed headlines and conflicting valuation signals can feel messy, so consider acting while the details are fresh and test the numbers yourself using 2 key rewards and 1 important warning sign.
Looking for more Nintendo investment ideas?
If the Nintendo story has sharpened your thinking, do not stop here. Broader idea generation helps you avoid tunnel vision and spot opportunities others skip.
- Target resilient cash generators that can handle shocks by scanning our list of solid balance sheet and fundamentals (25 results).
- Hunt for pricing gaps where quality and valuation still line up by reviewing the 18 high quality undervalued stocks.
- Shift your focus to potential income anchors by sizing up companies in the 27 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com