
e.l.f. Beauty (ELF) Stock Could Be Overvalued Despite Its 51% Q2 Sales Surge
e.l.f. Beauty has been a strong performer in recent years, and that kind of run naturally raises a question for you as an investor. Is the current share price still grounded in what the business is earning, or has sentiment moved ahead of the underlying profits story?
- Over the past 5 years the stock has returned about 250.2%, which puts real pressure on the question of whether earnings are pulling their weight at today’s valuation.
- Management is leaning into brand launches and international expansion, which can support higher earnings over time but also sets a higher bar for profit delivery to keep justifying the current P/E.
- Your read on e.l.f. Beauty is one view; the desks covering it have another. See what analysts think e.l.f. Beauty's shares could be worth.
The issue now is whether e.l.f. Beauty's current price can be explained by the earnings power that shareholders are paying for today.
If you want to stress test this question about e.l.f. Beauty against a wider field of opportunities, compare its earnings story with companies in 32 high quality undervalued stocks.
Has e.l.f. Beauty Run Too Far on Earnings?
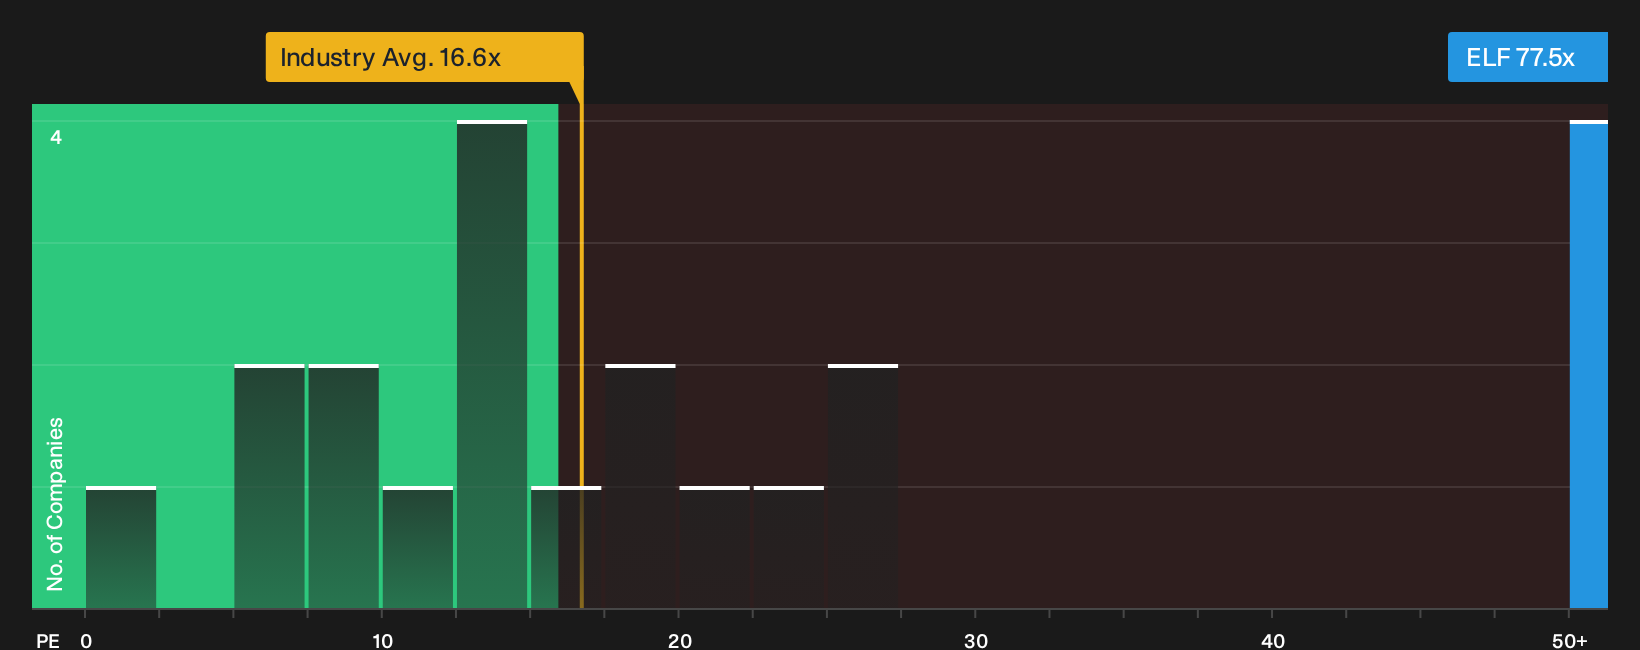
The P/E ratio fits e.l.f. Beauty because earnings still sit at the center of how investors are framing the story. Right now the stock trades on about 77.5x earnings, which is more than double the Personal Products sector average of 16.6x and well above the broader peer group around 32.5x.
On this model the multiple that would typically line up with e.l.f. Beauty's mix of growth prospects, profitability profile, size and risks is lower than where the shares change hands today, so the stock screens as overvalued on P/E. Despite the recent Q2 update highlighting strong sales momentum and an upbeat long term outlook, the current valuation already prices in a lot of that optimism. If you are weighing an entry point in e.l.f. Beauty, the key question is how much earnings power you believe justifies paying this kind of premium multiple relative to peers. Explore the numbers behind e.l.f. Beauty's P/E valuation.
The e.l.f. Beauty Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for e.l.f. Beauty pick up where this valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than where it trades today, and they sit on the company’s Community page. Rather than a single P/E or model output, each scenario lays out its own fair value assumptions so you can compare them with actual results as they arrive.
On e.l.f. Beauty, one view sees enough execution to support today’s price, while the other worries rich expectations leave little slack.
Bull case: roughly fairly valued
This view comes from the analyst consensus Narrative on Simply Wall St. It rolls up Street targets and forecasts into one storyline.
"The push into new brands and categories, including e.l.f. SKIN, Naturium, and the launch of e.l.f. Hair with products priced at US$10 or less and attracting a high share of new consumers to the franchise, extends the original thesis about value driven, inclusive positioning and adds further potential for unit led revenue growth and support for overall earnings…"
Discover why this Narrative puts e.l.f. Beauty at roughly fairly valued.
Bear case: roughly fairly valued
This angle comes from the bearish analyst Narrative on Simply Wall St. It leans on the most cautious targets and assumptions.
"Even though e.l.f. Beauty reports marketing returns that are multiples above industry benchmarks and plans to lean further into entertainment, sports sponsorships and AI driven engagement, sustaining this level of spend at 23% to 25% of net sales, as SG&A has already risen to 54% of revenue, risks eroding operating leverage and putting ongoing pressure on EBITDA margins…"
Explore why this Narrative puts e.l.f. Beauty at roughly fairly valued.
One more angle on e.l.f. Beauty that could change the way you see this valuation
Everything so far has focused on what e.l.f. Beauty looks like today. The analyst outlook a few years from now offers a separate reference point you can weigh against the current share price. Explore where analysts expect e.l.f. Beauty to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com