
Yesway (YSWY) Stock Still Looks Undervalued Despite Its 15% Rise
Yesway shares have gained 14.9% year to date, which puts a spotlight on whether the current price around US$24.39 still lines up with what the company is earning. With that move coming alongside a reshaping of its store footprint, the question now is how firmly those earnings support the market value investors are paying for Yesway stock.
- A 14.9% year to date rise means recent buyers are paying a meaningfully higher price, so the key issue is whether the underlying earnings profile has kept pace with that move.
- The sale of Iowa and Kansas convenience stores for US$21 million may support a sharper focus on remaining locations and potentially shift how investors think about Yesway's future profit mix and cash generation.
- There is a second opinion on Yesway worth weighing. See what analysts think Yesway's shares could be worth.
The issue now is whether the current market price of Yesway is adequately backed by its earnings when set against the Fair Ratio benchmark.
To compare Yesway in this earnings-focused context, consider evaluating it alongside other consumer stocks screened using 31 high quality undervalued stocks
Is Yesway Still Cheap on Earnings?
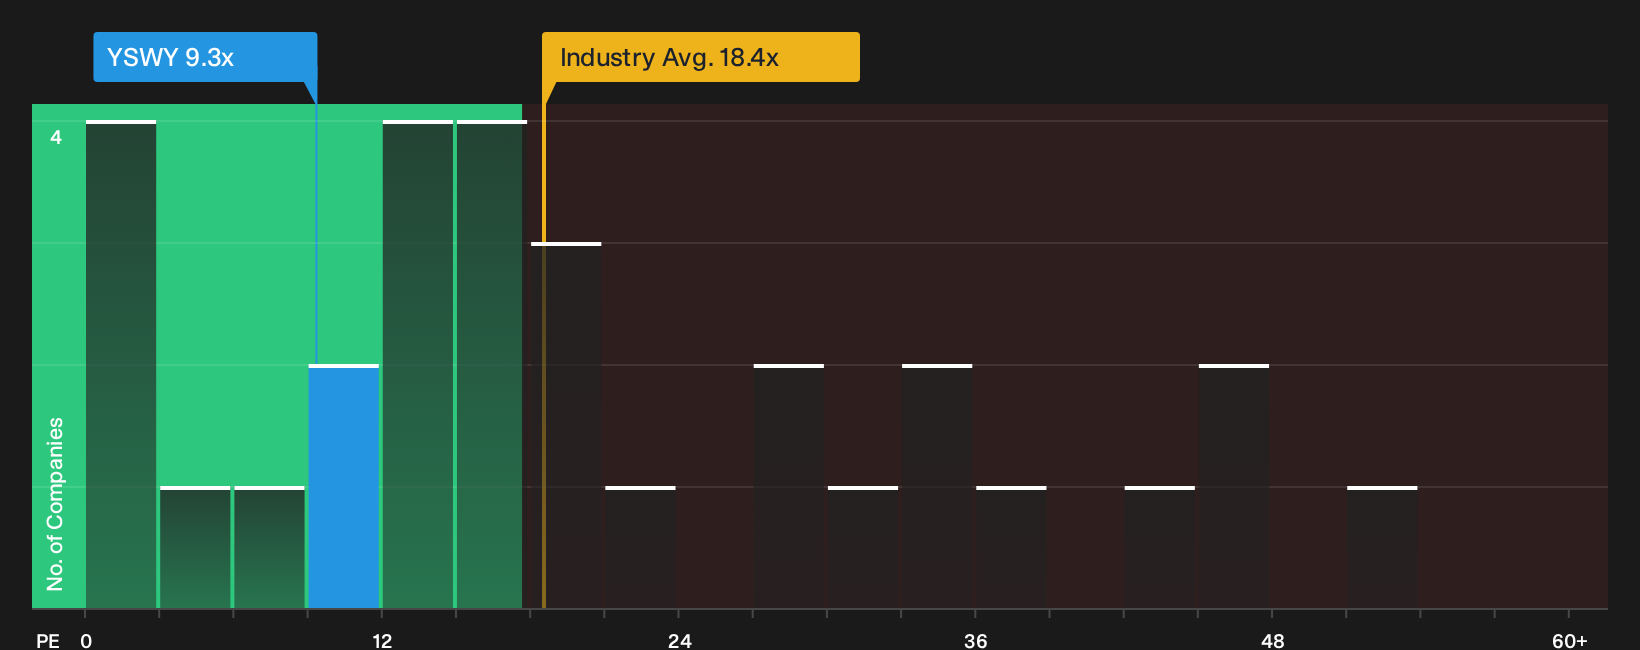
The P/E ratio makes sense for Yesway because earnings are a key driver for how this retailer is being priced today. At roughly 9.3x earnings, the stock trades at a clear discount to the Consumer Retailing sector, where the average sits near 18.4x, and also below the peer group around 15.1x. The Fair Ratio model, which blends factors like growth, profitability, size and risk into a tailored benchmark, points to a higher multiple than the one the market is currently paying, so on this metric Yesway screens as undervalued.
Because the Iowa and Kansas store sale has reshaped the footprint, investors now weighing Yesway need to decide whether the current earnings base and mix of locations justify a gap this wide to sector norms. For investors who believe the reshaped network can sustain or improve its profit engine, a single digit P/E, well below both peers and the modelled benchmark, suggests the market is still cautious on the story. Explore the numbers behind Yesway's P/E valuation.
The Yesway Narrative: What Would Justify Today's Price?
Narratives for Yesway pick up where the valuation puzzle leaves off. They spell out what kind of future path for growth, margins and earnings would need to hold for the stock to trade meaningfully above or below today’s level. Where a single ratio or model gives you just one number, these narratives lay out the underlying assumptions so you can watch how Yesway's actual progress lines up with that implied future over time on Simply Wall St's Community page.
A written, number driven view on Yesway matters now because the Iowa and Kansas store sale gives you a concrete test case for how a leaner footprint might influence earnings and valuation over time. Laying out the assumptions behind that view in advance makes it easier to track whether Yesway's actual results end up supporting or challenging the logic behind today's P/E.
Share your own Narrative for Yesway and set out the assumptions behind your valuation.
One big Yesway question still hanging over the current price
Everything so far circles around today's earnings and P/E, but analyst models sketch a very different picture of where this business might be a few years from now. Explore where analysts expect Yesway to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com