
Why Is Halozyme Therapeutics (HALO) Drawing Fresh Attention Today?
Halozyme Therapeutics earnings event
Halozyme Therapeutics (HALO) just put fresh numbers on the table, with third quarter 2026 results and raised full year guidance giving investors new data to assess the stock.
The biotech reported third quarter revenue of US$492.97 million and net income of US$247.05 million, alongside updated 2026 revenue expectations in a range of US$1.86 billion to US$1.93 billion.
Despite the upbeat third quarter report and raised 2026 guidance, Halozyme Therapeutics’ share price has pulled back sharply in the very short term, falling 18.13% over the last week and 8.16% over the past month. However, the year to date share price return of 43.18% and 1 year total shareholder return of 41.41% still point to strong longer term momentum, which investors are now reassessing in light of valuation concerns raised in recent broker commentary.
Spot opportunities beyond Halozyme Therapeutics by scanning a curated list of peers with similar quality traits in our 31 high quality undervalued stocks.The jump in Halozyme Therapeutics’ earnings and guidance has collided with an 18% pullback in the share price. Is most of the upside now already captured, or is the market overreacting to valuation worries?
Most Popular Narrative: 34% Undervalued
Halozyme Therapeutics last closed at $100.67, while the most followed narrative on Simply Wall St places fair value at $151.83, implying a sizeable valuation gap according to Teg, an investor in the Simply Wall St Community who set out a detailed royalty-based thesis.
Halozyme is being valued like a company with one great platform, management appears to be building three.
ENHANZE already generates more than $1 billion annually in royalties and still has a visible growth runway. Hypercon is targeted to become a second billion-dollar royalty franchise. Aerocon, acquired through Surf Bio's Snapshot technology, provides an additional layer of optionality that most valuations ignore entirely.
See why 5 investors see Halozyme Therapeutics as 34% undervalued.
The fair value estimate in the narrative uses a discount rate of 8.21% and assumes Halozyme Therapeutics can support a royalty driven model with a 25% profit margin and a future P/E of 25x. That framework also factors in revenue growth of 20% and an emerging multi platform structure that Teg views as underappreciated by the market at the current share price.
On that basis, the gap between the $151.83 narrative fair value and the $100.67 market price reflects differing views on how durable Halozyme Therapeutics’ royalty streams could be and how much weight to give newer platforms like Hypercon and Aerocon. The community thesis essentially treats those additional assets as material future contributors, where recent broker commentary appears more focused on near term earnings, forecast revenue growth of 4.6% a year and concerns about valuation and leverage.
Result: Fair Value of $151.83 (UNDERVALUED)
Still, the Halozyme Therapeutics story can break if partner royalties underwhelm expectations or if newer platforms like Hypercon and Aerocon struggle to gain traction.
Find out about the key risks to this Halozyme Therapeutics narrative.
Another View: Market Pricing Signals Caution
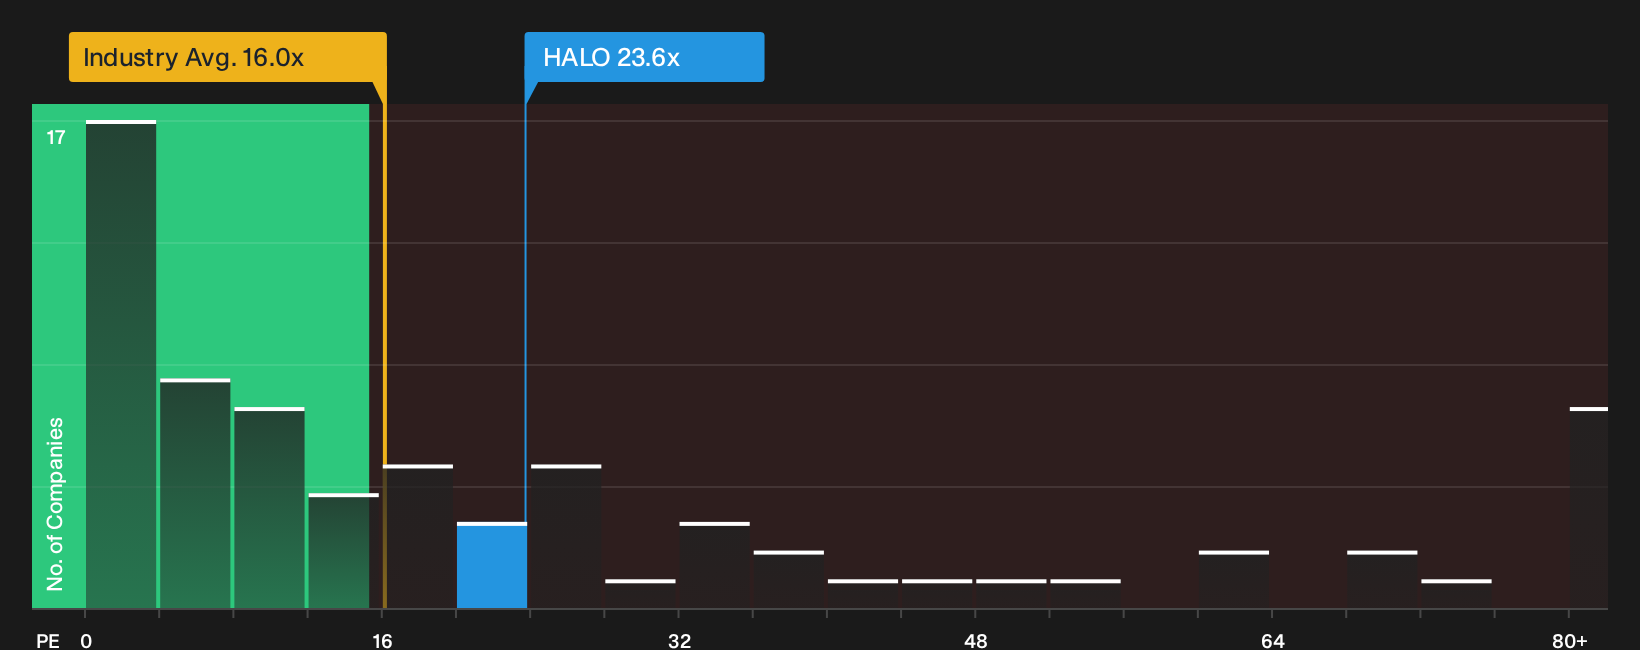
The community narrative frames Halozyme Therapeutics as meaningfully undervalued, yet the market is asking a different question. At a P/E of 23.6x compared to 16x for the US biotech industry and 19.3x for peers, the stock trades on a richer multiple. It also sits above an estimated fair ratio of 22.2x, which is the level the valuation could drift toward if sentiment cools. That premium can reflect belief in the royalty story, or it can leave less room for error if execution slips. Which side of that trade do you feel more comfortable on?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Halozyme Therapeutics can be useful if you use them as a prompt to stress test your own thesis quickly, then weigh up the balance of 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Halozyme Therapeutics?
If Halozyme Therapeutics has sharpened your thinking, do not stop there. Fresh ideas often come from comparing a few very different opportunities side by side.
- Target resilient cash generators by scanning a 6 dividend fortresses that focus on income strength as well as business durability.
- Spot potential quality-on-sale opportunities by reviewing a 20 high quality undiscovered gems that combine solid fundamentals with limited current market attention.
- Reduce portfolio stress by assessing a 29 resilient stocks with low risk scores designed to highlight businesses with stronger balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com