
Celestica (TSX:CLS) Guides For 85% CCS Growth, Is The Stock Cheap?
Recent commentary around Celestica (TSX:CLS) has focused on management’s guidance for roughly 85% revenue growth in the Connectivity & Cloud Solutions segment in 2026, tied to accelerating AI infrastructure investment by hyperscaler customers.
Celestica’s guidance is landing in a period where momentum has been choppy, with the share price up 4.77% in the last session and 25.48% over seven days, but still down 28.74% over 30 days and 22.21% over 90 days.
Those pullbacks leave the year-to-date share price return down 12.73%, even though total shareholder return over the past three and five years is reported as roughly 9x and 25x respectively. This indicates that investors may be reassessing how much future AI-driven growth and execution risk to price in at today’s CA$361.92 level.
Scan beyond Celestica and compare this AI hardware story with other potential breakouts using our hand picked 53 AI infrastructure stocks for the current data center buildout cycle.
Bulls see Celestica as a rare pure play on hyperscaler AI buildouts, while bears focus on a sharp pullback and customer concentration. Which story does the current valuation actually support?
Most Popular Narrative: 47% Undervalued
Against Celestica’s last close at CA$361.92, the analyst consensus Narrative on Simply Wall St pins fair value at CA$685.63. This points to a wide gap that analysts link to AI rack programs and long dated demand visibility.
Extended component lead times above 52 weeks, combined with non cancellable, non returnable orders and long term materials planning out to 2028 and 2029, provide unusual visibility on multi year AI and networking demand. This can underpin Celestica’s revenue planning and support consistent free cash flow generation.
See why 192 investors see Celestica as 47% undervalued.
Result: Fair Value of CA$685.63 (UNDERVALUED)
Still, concentrated hyperscaler exposure and heavy AI driven CapEx mean that any order cuts or project delays could quickly challenge the current Celestica upside story.
Find out about the key risks to this Celestica narrative.
Another View: Celestica Through The P/E Lens
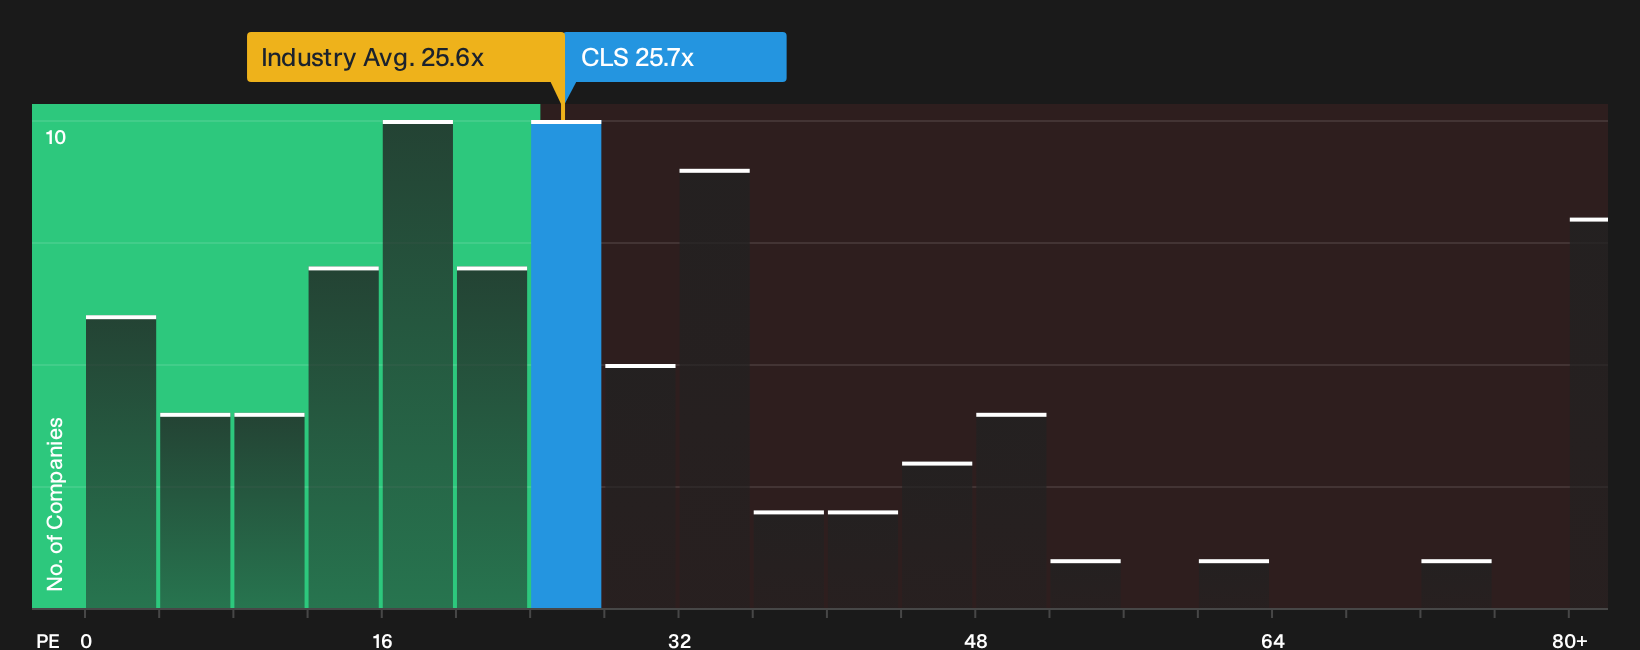
The first story frames Celestica as roughly 47% undervalued versus a CA$685.63 fair value. A simpler yardstick tells a quieter story. On a P/E of 25.7x, the stock is slightly more expensive than the North American Electronic industry at 25.6x, yet screens cheap against its own 47.9x fair ratio. Is that a genuine opportunity or just extra valuation risk baked into optimistic AI assumptions?
Before leaning too hard on any single earnings multiple, it helps to see how the current price stacks up against that fair ratio and against peers in more detail. The breakdown in See what the numbers say about this price — find out in our valuation breakdown. puts these metrics side by side for you.
Next Steps
Mixed messages on Celestica usually mean one thing for you: act quickly, look through both sides of the story and weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Celestica?
Your edge rarely comes from a single stock. It comes from lining up several quality ideas that fit your risk, income, and growth priorities.
- Target potential mispricings by scanning a curated 6 high quality undervalued stocks that filters for quality companies trading at what may be appealing valuations.
- Strengthen your downside protection by reviewing a 9 resilient stocks with low risk scores that highlights businesses with more resilient balance sheets and risk profiles.
- Spot earlier stage opportunities by running through a 18 elite penny stocks with strong financials focused on smaller companies with stronger financial traits than the broader microcap universe.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com