
BBB Foods (TBBB) Earnings Turnaround Has Investors Asking If The Valuation Is Already Priced In
BBB Foods (NYSE:TBBB) is back in focus after its third quarter earnings on November 2, 2026, showed higher sales, stronger revenue and a move from loss to profit in Mexican peso terms.
Investors have reacted quickly to the stronger third quarter, with BBB Foods’ share price returning 20.48% over the past month and 42.29% across 90 days. This has contributed to a 97.85% year to date share price return and a 158.56% 1 year total shareholder return that signals strong momentum building behind the earnings turnaround story.
Scan other consumer-focused stocks showing similar earnings momentum with our curated list of 20 high quality undiscovered gems alongside the recent turnaround at BBB Foods.
After a near doubling in 2026 and a move into profit in Mexican peso terms, BBB Foods now trades above the average analyst target while still screening at a discount to intrinsic value. Is the market being too cautious, or not cautious enough?
Most Popular Narrative: 9% Overvalued
On the Simply Wall St analyst consensus Narrative, BBB Foods carries a fair value estimate of $62.11 compared with a last close of $68. This view, built from aggregated analyst targets and forecasts using a 9.24% discount rate, frames the current price as richer than that Narrative suggests.
The current valuation, alongside this narrative's view that BBB Foods is fairly valued and bullish, implies that the market is already pricing in continued high growth, strong cash generation and effective execution on the expansion plan.
Ongoing aggressive store expansion, with Tiendas 3B opening 574 net new stores in 2025 and adding 278 more in the first half of 2026 to reach 3,624 locations, points to continued growth in revenue as new stores ramp and contribute more meaningfully to earnings over time.
See why 20 investors see BBB Foods as 9% overvalued.
Result: Fair Value of $62.11 (OVERVALUED)
Still, the bullish BBB Foods narrative can unravel if rapid store openings continue to squeeze margins or if ongoing equity issuance dilutes any future earnings recovery.
Find out about the key risks to this BBB Foods narrative.
Another View: BBB Foods Through A Cash Flow Lens
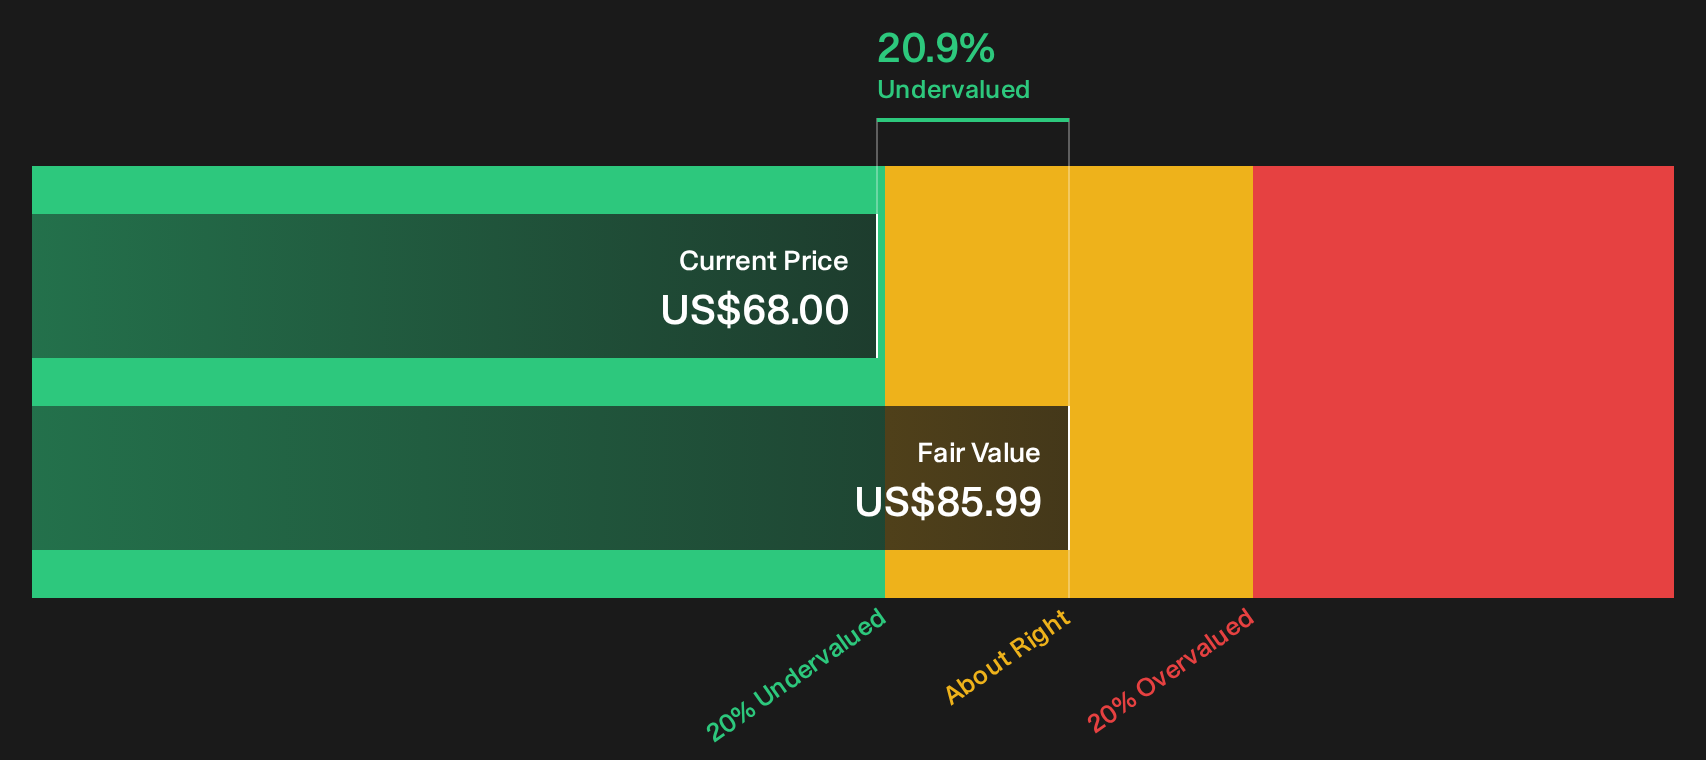
The analyst consensus tags BBB Foods as about 9% overvalued at $62.11 versus a $68 share price. Our DCF model points in a different direction. On projected future cash flows, Simply Wall St estimates a value of $86.03 per share, which flags BBB Foods as trading at roughly a 21% discount. Which story do you trust more: analyst targets or modeled cash generation over time?
For a closer look at how each cash flow assumption feeds into that $86.03 estimate, and where the big sensitivities sit, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out BBB Foods for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around BBB Foods feels familiar, consider acting while the data is fresh and shape your own view with 2 key rewards and 1 important warning sign.
Looking for more ideas beyond BBB Foods?
Do not stop your research with BBB Foods. Broaden your watchlist now and give yourself a better chance of spotting the next opportunity before the crowd moves.
- Hunt for mispriced quality by scanning companies that currently screen as 31 high quality undervalued stocks and might suit a value-focused checklist.
- Strengthen your defense by reviewing a 29 resilient stocks with low risk scores that focuses on businesses with more resilient profiles when conditions get tougher.
- Target sturdier finances by running a list of solid balance sheet and fundamentals (23 results) and focusing on companies with cleaner balance sheets and stronger fundamentals supporting their story.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com