
Sampo Oyj (HLSE:SAMPO) Faces A 4% Fair Value Gap As Earnings Weaken
Sampo Oyj (HLSE:SAMPO) just posted third quarter results that showed net income of €270 million, with basic earnings per share from continuing operations at €0.10.
The latest report lands after a busy few months for Sampo Oyj, which has been running a sizeable buyback program and now trades at €10.065, with a 1 month share price return of 12.99% and a 5 year total shareholder return of 65.59%. This points to long term momentum even as shorter term moves react to the weaker earnings and shifting views on risk.
Scan for other insurance and financials stocks showing strong total return profiles and active capital returns with our curated list of 193 high quality undervalued stocks.
Sampo Oyj shares have rallied while earnings have moved the other way, which leaves a simple tension. Is the price now tracking sentiment more than the underlying insurance business, or do the current numbers still justify the move?
Most Popular Narrative: 4% Undervalued
Sampo Oyj closed at €10.07, while the analyst consensus Narrative on Simply Wall St points to a fair value of €10.51 when discounting future cash flows at 6.11%. That gap is modest, yet it reflects a view that the insurer’s earnings profile and capital returns still justify a slightly higher tag than the current market price.
Ongoing investments in digital distribution, automation, and analytics are now visible in over 70% of claims reported digitally, 1.8 million mobile app downloads and AI tools such as IfGPT and If Vet, which increases scope for lower cost ratios, more accurate pricing and ultimately higher net margins and earnings power.
See why 33 investors see Sampo Oyj as 4% undervalued.
Result: Fair Value of €10.51 (UNDERVALUED)
Still, the story can change quickly if claims inflation in areas like UK motor proves sticky, or if the Topdanmark integration delivers weaker cost savings than expected.
Find out about the key risks to this Sampo Oyj narrative.
Another View: Sampo Oyj Looks Expensive On Earnings
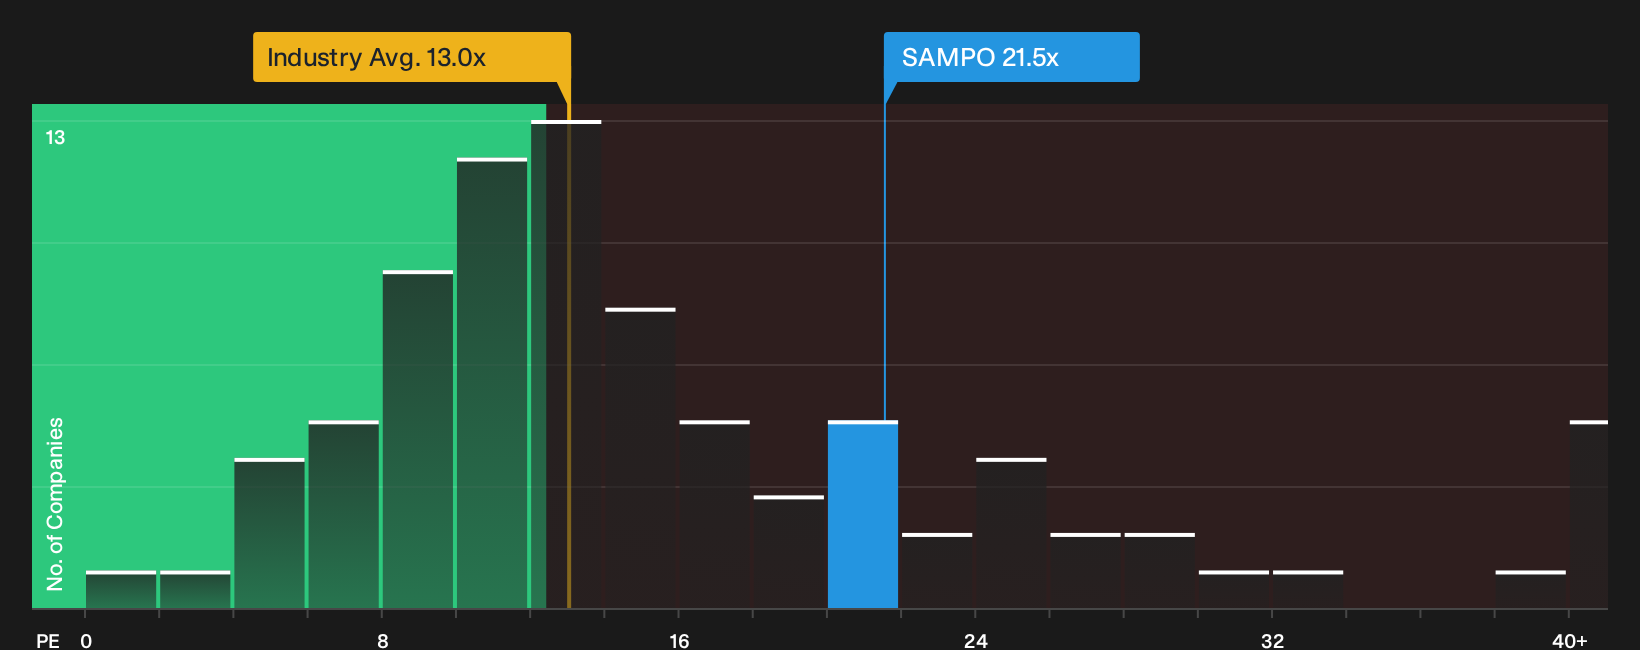
The first take on Sampo Oyj leans on future cash flows and lands on a fair value above today’s share price. A simple P/E check tells a different story. The stock trades on 21.5x earnings, versus 15.2x for peers and 13x for the wider European insurance group, while the fair ratio model points to 19.1x. That gap suggests investors are already paying a premium, so the question is whether you are comfortable underwriting that extra valuation risk.
For a closer look at how that earnings multiple compares with peers and the fair ratio, and what the numbers imply for potential future pricing shifts, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by mixed signals around Sampo Oyj and unsure which way to lean right now? Move quickly from headline impressions to hard data and weigh both sides of the story with 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sampo Oyj?
If you only stop at Sampo Oyj, you risk missing other opportunities that fit your style, your risk tolerance, and your income needs.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (200 results), which can help you focus on financially steady businesses instead of fragile stories.
- Hunt for mispriced quality by running through 193 high quality undervalued stocks, built to surface companies where strong fundamentals do not fully match the current share price.
- Build a cash flow paycheck by sorting through 216 dividend fortresses, which highlights higher yielding options when you want your portfolio to work a little harder.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com