
Ecovyst (ECVT) Lifted Its 2026 Outlook, Is The Stock Cheap Or Pricey?
Why Ecovyst Stock Is Back On Investors’ Radar
Ecovyst (ECVT) moved into focus after management raised its 2026 earnings outlook and reported third quarter results that showed higher sales and a shift back to profitability.
Ecovyst’s recent guidance hike and return to profit have arrived alongside a clear shift in sentiment, with the 7-day share price return of 5.6% and 30-day gain of 6.65% pointing to building momentum, while the 1-year total shareholder return of 25.15% reflects a stronger longer term payoff than its shorter term share price moves alone might suggest.
Scan Ecovyst’s momentum shift against other potential breakouts on our hand picked list of 31 high quality undervalued stocks with improving fundamentals and room for sentiment to catch up.
After Ecovyst’s sharp rebound in earnings and guidance, the share price has started to move, but not explosively. Does it make more sense to step in now or wait for a cleaner entry on valuation grounds instead?
Most Popular Narrative: 29% Undervalued
On the analyst consensus Narrative on Simply Wall St, Ecovyst screens as undervalued, with a fair value of $15.17 against the last close of $10.75. That gap reflects a view that the sulfur platform has more earnings power than the current share price implies.
The ongoing build out of Ecovyst's integrated sulfur solutions platform, with the completed acquisitions of Chem32, Waggaman and Calabrian and the prior divestiture of Advanced Materials & Catalysts, is creating a more focused network that can serve shared customers and is expected to support future revenue and adjusted EBITDA growth.
See why 3 investors see Ecovyst as 29% undervalued.
Result: Fair Value of $15.17 (UNDERVALUED)
Still, the Ecovyst story can change quickly if higher sulfur costs inflate sales without much profit, or if rising capital spending drags on cash generation.
Find out about the key risks to this Ecovyst narrative.
Another View: Ecovyst Looks Pricey On Earnings
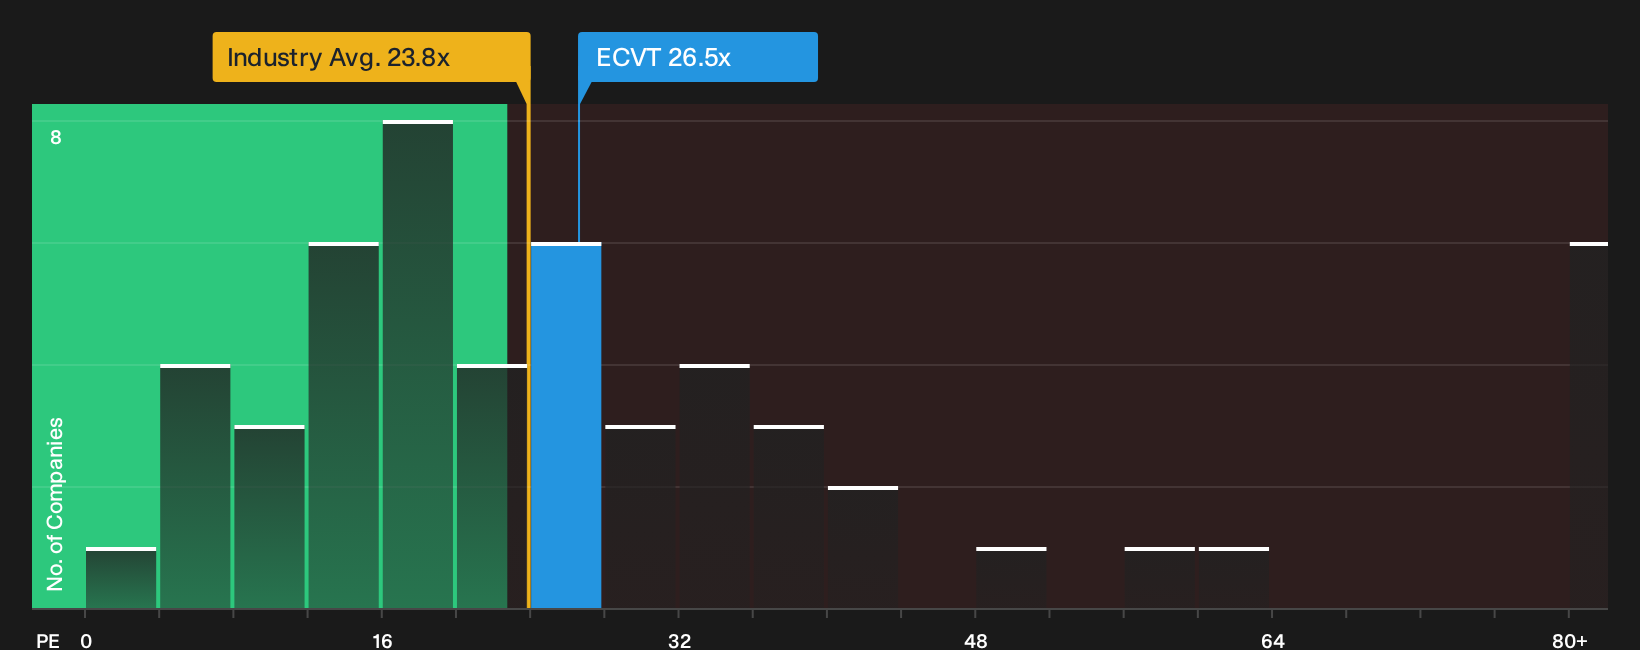
On the flip side of that Ecovyst fair value estimate of $15.17, the current share price of $10.75 equates to a P/E of 26.5x, compared with 18.5x for peers and 23.8x for the wider US Chemicals group. That richer multiple suggests less room for error if earnings wobble again.
Higher quality growth stories can justify a premium, but a stock trading on a P/E well above both direct competitors and the sector can also see sentiment reverse quickly if expectations reset. Which signal do you treat as more important? The analyst fair value gap, or the earnings multiple sitting ahead of the pack.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Ecovyst leave you torn between caution and optimism, move quickly to inspect the details yourself and decide where you stand. To balance both sides of the story in one place, review the 3 key rewards and 3 important warning signs.
Looking For More Ideas Beyond Ecovyst?
Do not stop with Ecovyst alone. Use the Simply Wall St Screener to line up fresh prospects and keep your watchlist packed with high conviction ideas.
- Target durable income streams by scanning for reliable payouts and balance sheet support through the 6 dividend fortresses.
- Hunt for quality at a discount by sorting companies that combine strong fundamentals with pricing that still looks appealing using the 31 high quality undervalued stocks.
- Zero in on financial resilience by filtering for businesses that back their story with robust finances through the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com