
What Kinder Morgan (KMI)'s Record Gas Backlog Means For Shareholders
- Kinder Morgan reported third quarter results with a record US$13.2b natural gas expansion backlog, including new projects such as Southeast Connector and Permian Link scheduled to start phased operations in 2030.
- The enlarged backlog signals that Kinder Morgan is leaning into long term, contract backed natural gas transport demand rather than short term commodity price swings.
- We will examine how Kinder Morgan's investment narrative is shaped by its record US$13.2b natural gas expansion project backlog.
Scan beyond Kinder Morgan and explore other infrastructure plays tied to long term energy demand by reviewing our hand picked 43 power grid technology and infrastructure stocks
Kinder Morgan Investment Narrative Recap
To own Kinder Morgan, you have to believe in long term demand for its natural gas infrastructure and its ability to turn a growing backlog into fee based cash flow. The record US$13.2b expansion queue reinforces that story, but does not change the near term focus, which still sits on executing existing projects and keeping daily operations steady.
The analyst consensus narrative on Simply Wall St leans heavily on Kinder Morgan converting its project pipeline while holding leverage within the stated 3.5x to 4.5x range. The main short term swing factor is disciplined capital allocation versus that balance sheet. The key risk is taking on too much expansion spend if volumes or contract terms end up softer than planned.
Among recent updates, the enlarged Board approved growth backlog that previously sat around US$9.6b is central to this news. Management had linked that queue to roughly US$1.7b of potential incremental EBITDA over time, and the move to a US$13.2b natural gas focused backlog pushes execution risk and opportunity further in the same direction.
Projects such as Permian Link and Southeast Connector now sit alongside earlier efforts like Mississippi Crossing and South System Expansion 4, giving Kinder Morgan a deeper bench of contract driven work to deliver. For you as a shareholder, the story now hinges even more on on time, on budget construction, stable counterparties, and Kinder Morgan keeping leverage and dividend coverage in a range that feels comfortable.
Kinder Morgan Forecasts Behind the Backlog Story
Kinder Morgan's narrative projects US$20.4b revenue and US$3.9b earnings by 2029. This is based on analysts assuming 3.6% yearly revenue growth and an earnings increase of about US$300m from US$3.6b today.
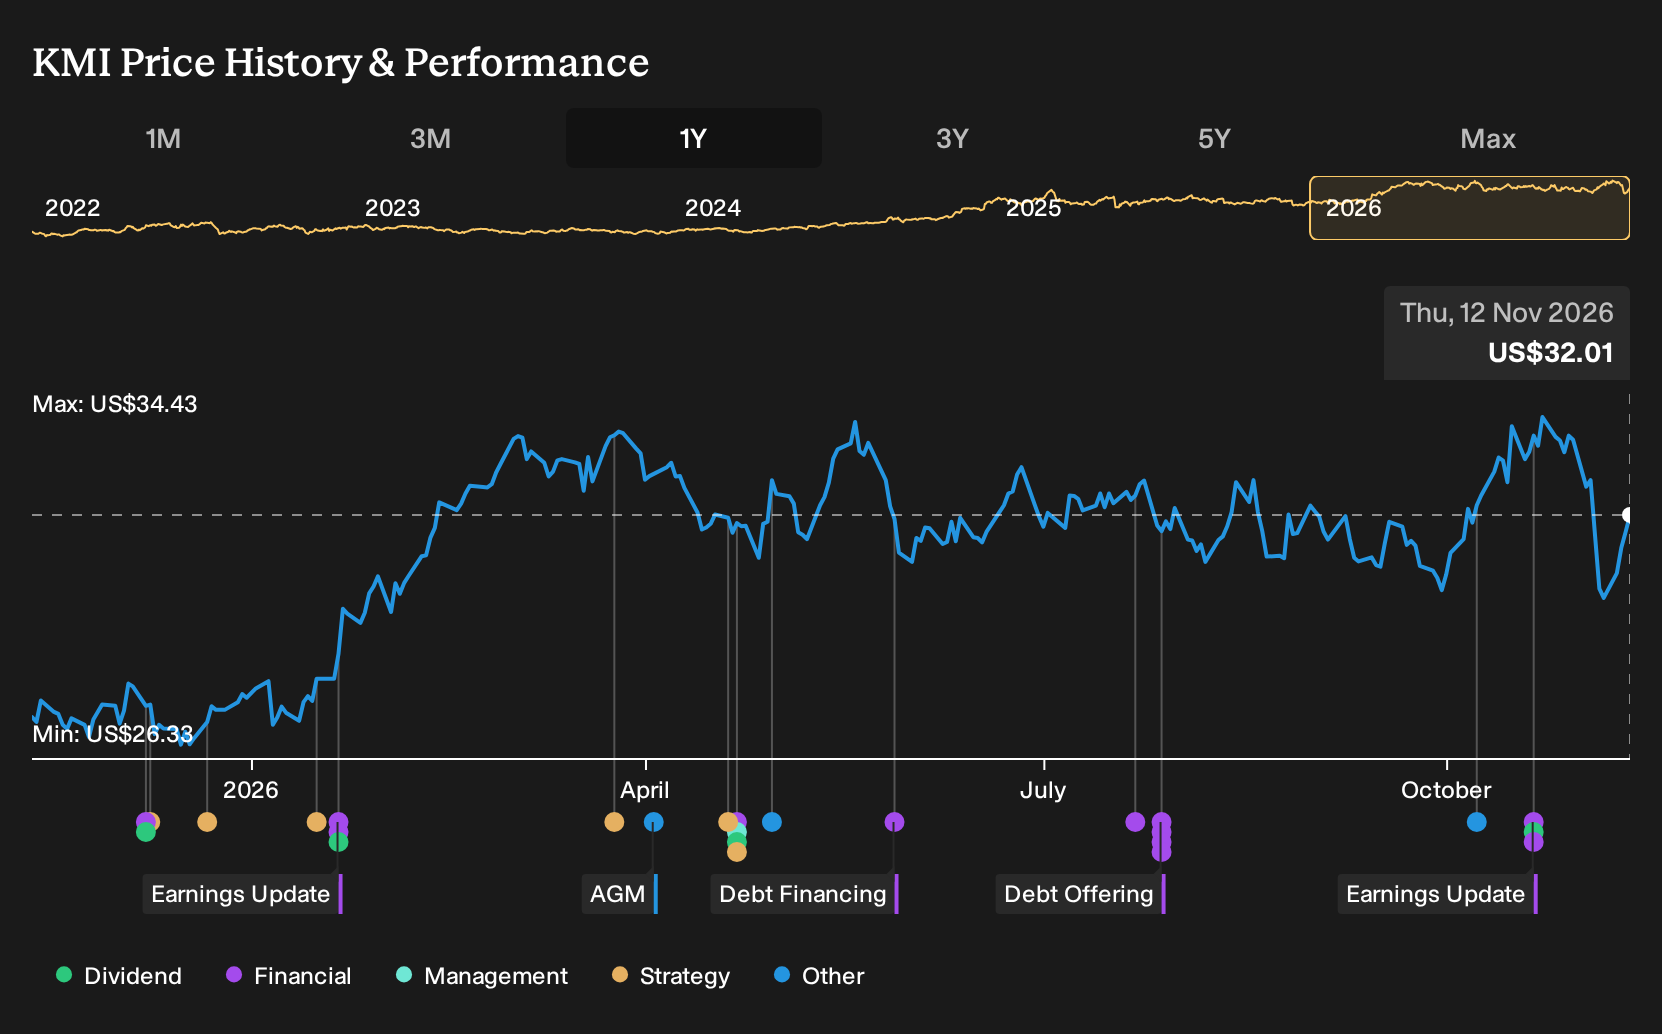
Discover why Kinder Morgan's fair value currently reflects a 16% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$29 to US$37 per Kinder Morgan share, which shows how far private investors can diverge on the same data. In light of that spread, project delays, leverage drifting toward the top of the 3.5x to 4.5x band, or successful backlog conversion could all reshape expectations. Explore multiple viewpoints before deciding how Kinder Morgan fits your portfolio.
Explore another Kinder Morgan fair value estimate, including one that suggests there may be as much as 10% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Kinder Morgan research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kinder Morgan. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kinder Morgan's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kinder Morgan?
If Kinder Morgan has sharpened your focus on durable cash flows and capital discipline, it can be useful to line it up against other candidates that share similar qualities or target very different opportunities. The Simply Wall St Screener lets you scan the market through that lens so you can build a watchlist that actually matches your goals rather than the latest headline.
- For investors hunting for mispriced opportunities with solid fundamentals, start by scanning our 31 high quality undervalued stocks that pass strict quality and valuation checks.
- If capital preservation ranks high for you, compare Kinder Morgan with our 29 resilient stocks with low risk scores that combine resilient balance sheets with lower volatility profiles.
- For those who care most about financial strength and staying power, filter for companies on the list of solid balance sheet and fundamentals (23 results) to see which businesses keep leverage and liquidity in tighter shape.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com