
Excelerate Energy (EE) Could Be 12% Undervalued After Its 11 Year Bahamas LNG Deal
Why the Bahamas LNG deal matters for Excelerate Energy
Excelerate Energy (EE) has just signed an 11-year LNG supply agreement tied to the planned Bahamas LNG Hub, giving the business a fresh Caribbean anchor for long-term contracted volume.
Initial LNG deliveries linked to this deal are expected in 2027, with a possible floating storage unit near Grand Bahama targeted for 2028, subject to permitting, construction, and contractual milestones.
Excelerate Energy shares trade at US$38.10 and have seen strong momentum recently, with a 7-day share price return of 7.81% and a year-to-date share price gain of 34.44%, while the 3-year total shareholder return of 120.71% points to a powerful longer-term run.
Scan Excelerate Energy’s Caribbean LNG momentum against a hand-picked set of infrastructure-focused peers using our 43 power grid technology and infrastructure stocks for potential breakout and resilience ideas in the wider energy network.
The Bahamas deal and record earnings have already pushed Excelerate Energy higher. The question now is whether the current price reflects that momentum, or if patience could offer a cleaner entry as the valuation work shows.
Most Popular Narrative: 12% Undervalued
On the analyst consensus Narrative on Simply Wall St, Excelerate Energy’s fair value of $43.46 sits above the latest $38.10 close. This points to upside that hinges on how its LNG infrastructure pipeline plays out over the next few years.
The sequenced rollout of the integrated Iraq LNG import terminal in early Q2 2027 and the Methane Patricia Camila FSRU conversion targeted for early 2028, with management citing expected 5x to 7x unlevered build multiples on the conversion, creates a visible project queue that can support higher adjusted EBITDA beyond current guidance.
See why 13 investors see Excelerate Energy as 12% undervalued.
Result: Fair Value of $43.46 (UNDERVALUED)
Still, the Excelerate Energy story can shift quickly if LNG demand softens, or if large, capital-heavy projects in markets such as Iraq or the Caribbean face delays or underutilization.
Find out about the key risks to this Excelerate Energy narrative.
Another View: Excelerate Energy on Earnings Multiples
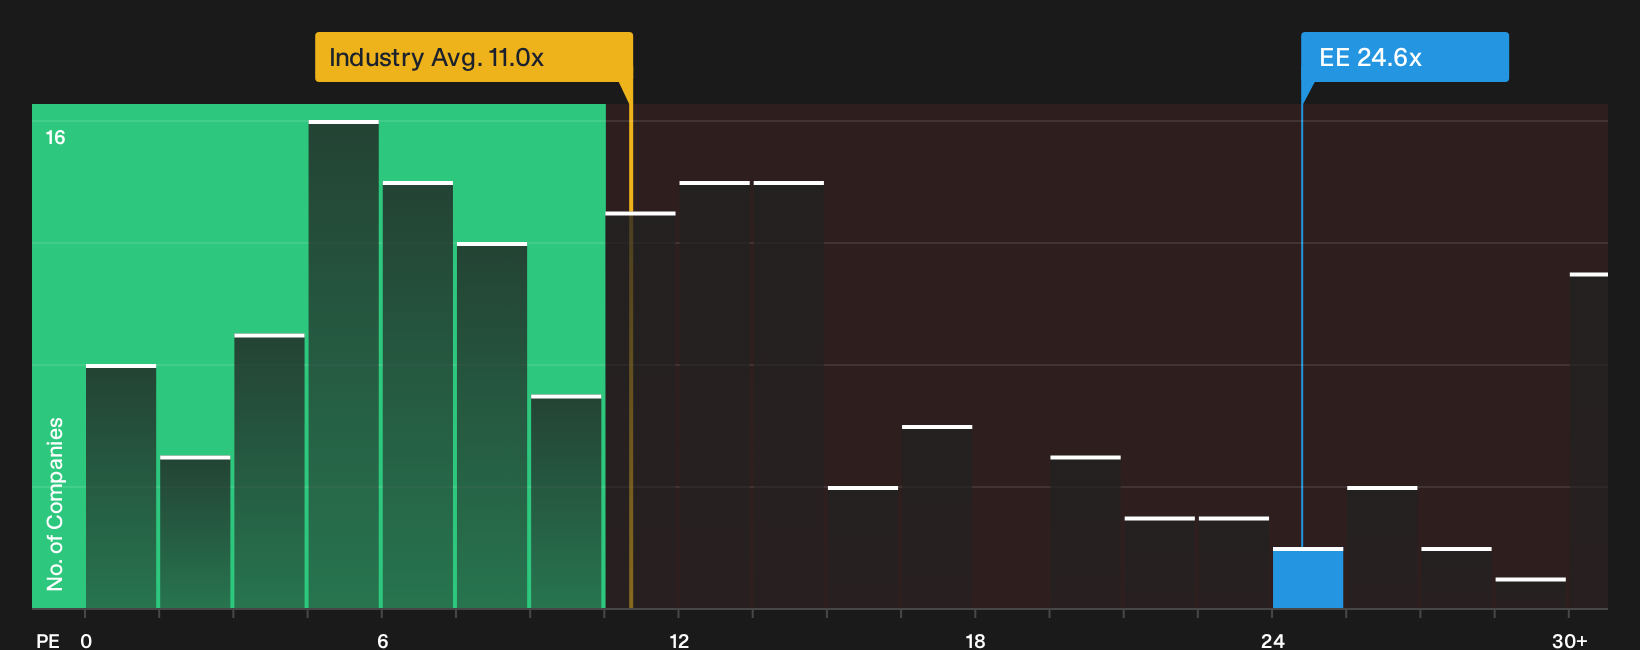
The SWS DCF model points to Excelerate Energy trading at a 70.1% discount to its future cash flow value, yet the picture shifts when earnings multiples enter the frame. At a P/E of 24.6x versus 11x for the US Oil and Gas industry and a fair ratio of 18.8x, the stock screens expensive on this yardstick. This raises a simple question: is the gap a genuine opportunity or just added valuation risk if growth stumbles?
To see how that premium multiple stacks up against the underlying cash flow work, and what would need to go right for the current price to hold up, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Is this a big upside narrative or just enthusiasm chasing Excelerate Energy’s LNG pipeline? Either way, move quickly to stress test the optimism against the 3 key rewards.
Looking for more investment ideas beyond Excelerate Energy?
Do not stop at Excelerate Energy. Broaden your watchlist with fresh opportunities filtered by quality, resilience, and income so you are not relying on a single story.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (23 results). This can help anchor your portfolio when sentiment swings.
- Hunt for mispriced quality using a curated set of 31 high quality undervalued stocks that combine stronger fundamentals with more appealing valuations.
- Strengthen your income stream by reviewing a focused group of 6 dividend fortresses built around higher yields and balance sheet support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com