
How Strong Third Quarter Earnings At Coca Cola Consolidated (COKE) Has Changed Its Investment Story
- Coca-Cola Consolidated reported third quarter 2026 results with sales of US$1,989.54 million and net income of US$175.86 million, along with higher diluted EPS from continuing operations compared with the prior year period.
- Across the first nine months of 2026, Coca-Cola Consolidated generated US$5,888.63 million in sales and US$446.24 million in net income, highlighting earnings power that extends beyond a single-quarter headline.
- Attention now turns to how Coca-Cola Consolidated's stronger third quarter earnings profile could reshape the investment narrative that investors have been using.
Scan the beverage space for other earnings stories that might echo Coca-Cola Consolidated's momentum by reviewing our curated 20 high quality undiscovered gems.
What Is Coca-Cola Consolidated's Investment Narrative?
Coca-Cola Consolidated appeals to investors who want exposure to everyday consumption, with an emphasis on execution in bottling, distribution and pricing rather than big product bets. The third quarter report fits that story. Sales and earnings for both the quarter and the first nine months of 2026 show a business that is still moving volume and collecting cash in a capital intensive setup where trucks, plants and coolers do most of the talking. In the short term, the key questions sit around how firmly recent pricing sticks and how much of the earnings power is coming from operational tweaks versus mix.
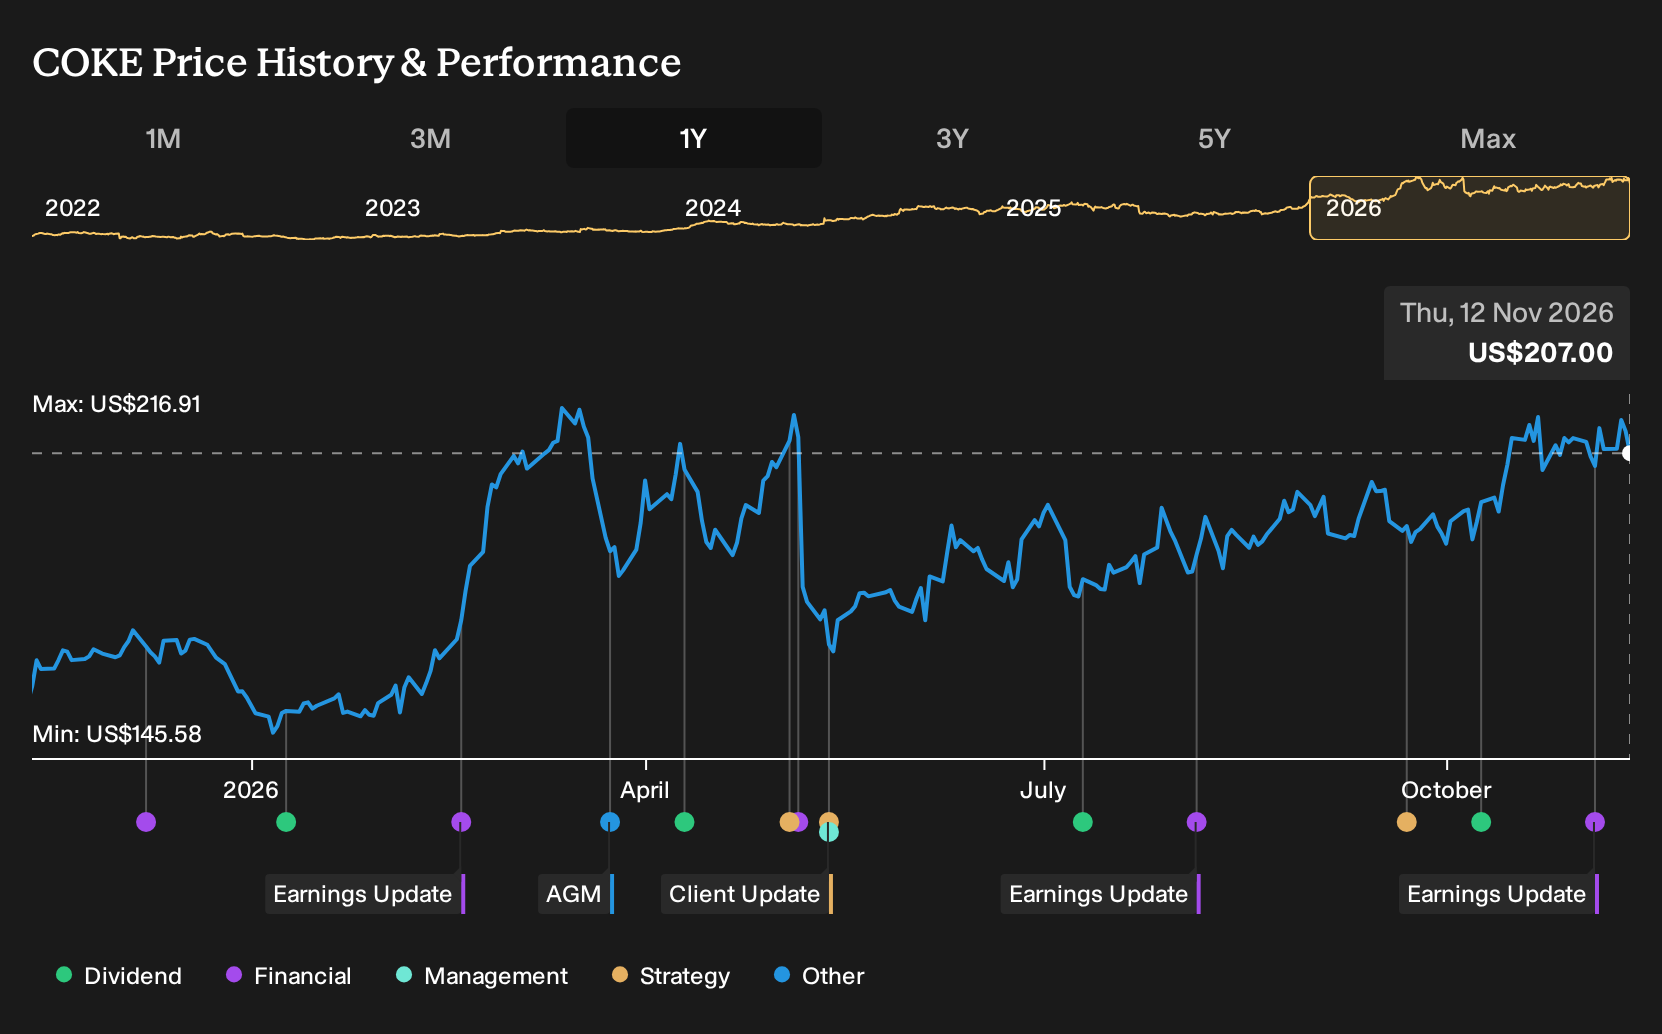
The latest earnings print also lands against a balance sheet that carries high debt and negative shareholders’ equity. That combination keeps funding and interest costs front of mind, especially when every extra cooler or delivery route absorbs more capital. The share price has risen strongly year to date, and the P/E sits above the global beverage average, so investors are already paying for consistency. Quarterly EPS momentum helps the near term story, yet it does not remove the need to watch how much flexibility Coca-Cola Consolidated really has if conditions change.
Even so, there is a specific pressure point in Coca-Cola Consolidated's setup that deserves closer attention before assuming this run can continue.
There's only one way to know the right time to buy, sell or hold Coca-Cola Consolidated. Head to Simply Wall St's company report for the latest analysis of Coca-Cola Consolidated's Fair Value.
Exploring Other Perspectives
The two fair value estimates for Coca-Cola Consolidated from the Simply Wall St Community cluster tightly between US$186.20 and about US$186.87, so you are seeing agreement rather than a wide spread. Those views also predate the latest earnings release. This gives you a clear reason to compare fresh results with these existing opinions and explore more than one angle before deciding how the current price lines up with your own expectations.
Explore another Coca-Cola Consolidated fair value estimate, including one that indicates as much as 10% downside from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Coca-Cola Consolidated research is our analysis highlighting 2 important warning signs that could impact your investment decision.
- See our latest analysis for Coca-Cola Consolidated. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coca-Cola Consolidated's overall financial health at a glance.
Looking For More Ideas Beyond Coca-Cola Consolidated?
If you want to stress test your view on Coca-Cola Consolidated or simply broaden your watchlist, it can help to line it up against businesses with very different risk and income profiles. The Simply Wall St Screener gives you a quick way to compare fundamentals side by side and see which stories actually fit your own return and risk preferences.
- For investors who want potential upside without ignoring balance sheet quality, consider scanning a curated 20 high quality undiscovered gems that combine strong fundamentals with under-the-radar profiles.
- If capital preservation and steadier profiles matter more than headline excitement, filter for 29 resilient stocks with low risk scores and focus on businesses that score well on resilience.
- For readers who prefer getting paid while they wait, narrow in on income-heavy opportunities with a 6 dividend fortresses that target higher yielding payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com