
Delta Galil Industries (TASE:DELG) Rallies On Strong Results While Valuation Still Looks In Focus
Delta Galil Industries (TASE:DELG) just posted fresh third quarter and nine month results, reporting higher sales, net income and earnings per share compared with the same periods a year earlier.
The latest earnings update appears to have reset expectations around Delta Galil Industries, with the share price climbing to ₪202.8 and recent momentum strengthening. This is shown by a 30-day share price return of 18.11% and a 3-year total shareholder return of 51.45%, which points to a longer-running recovery story.
Scan how Delta Galil Industries compares with other consumer names showing fresh earnings momentum by checking out our handpicked 564 high quality undiscovered gems in the same space.
Delta Galil Industries is putting up stronger earnings and a rising share price, but that combination only helps you if the stock still offers fair value. So what are you actually paying for at ₪202.8 per share?
Price-to-Earnings of 15.9x: Is it justified?
On a simple P/E lens, Delta Galil Industries trades on 15.9x earnings, which puts the current ₪202.8 share price at a richer level than parts of its sector but cheaper than a group of closer peers.
The P/E ratio compares what investors pay for each ₪1 of earnings to what they might pay for other businesses. For a branded apparel and intimatewear group like Delta Galil Industries, this measure often reflects how confident the market is in the durability of profits and the stability of demand across regions and channels.
At 15.9x earnings, the stock is priced above the Asian Luxury industry average of 14.3x, which signals investors are accepting a higher entry price than the wider industry. At the same time, the multiple is far below the peer average of 32.5x, which shows the market is valuing this business far more cautiously than comparable companies.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 15.9x (ABOUT RIGHT)
Still, the story can change quickly if demand for intimatewear and denim weakens or if licensed brands choose different partners for key markets.
Find out about the key risks to this Delta Galil Industries narrative.
Another View: What The Cash Flows Say About Delta Galil Industries
The P/E of 15.9x paints Delta Galil Industries as roughly in the middle of the pack on earnings, yet the SWS DCF model points to something different. With an estimated future cash flow value of ₪313.09 per share versus a market price of ₪202.8, the stock screens as undervalued on this lens.
That gap suggests investors may be paying more attention to recent profit trends and industry comparisons than to long range cash generation. The question for you is which picture feels more compelling when you think about holding Delta Galil Industries through a full cycle.
Look into how the SWS DCF model arrives at its fair value.
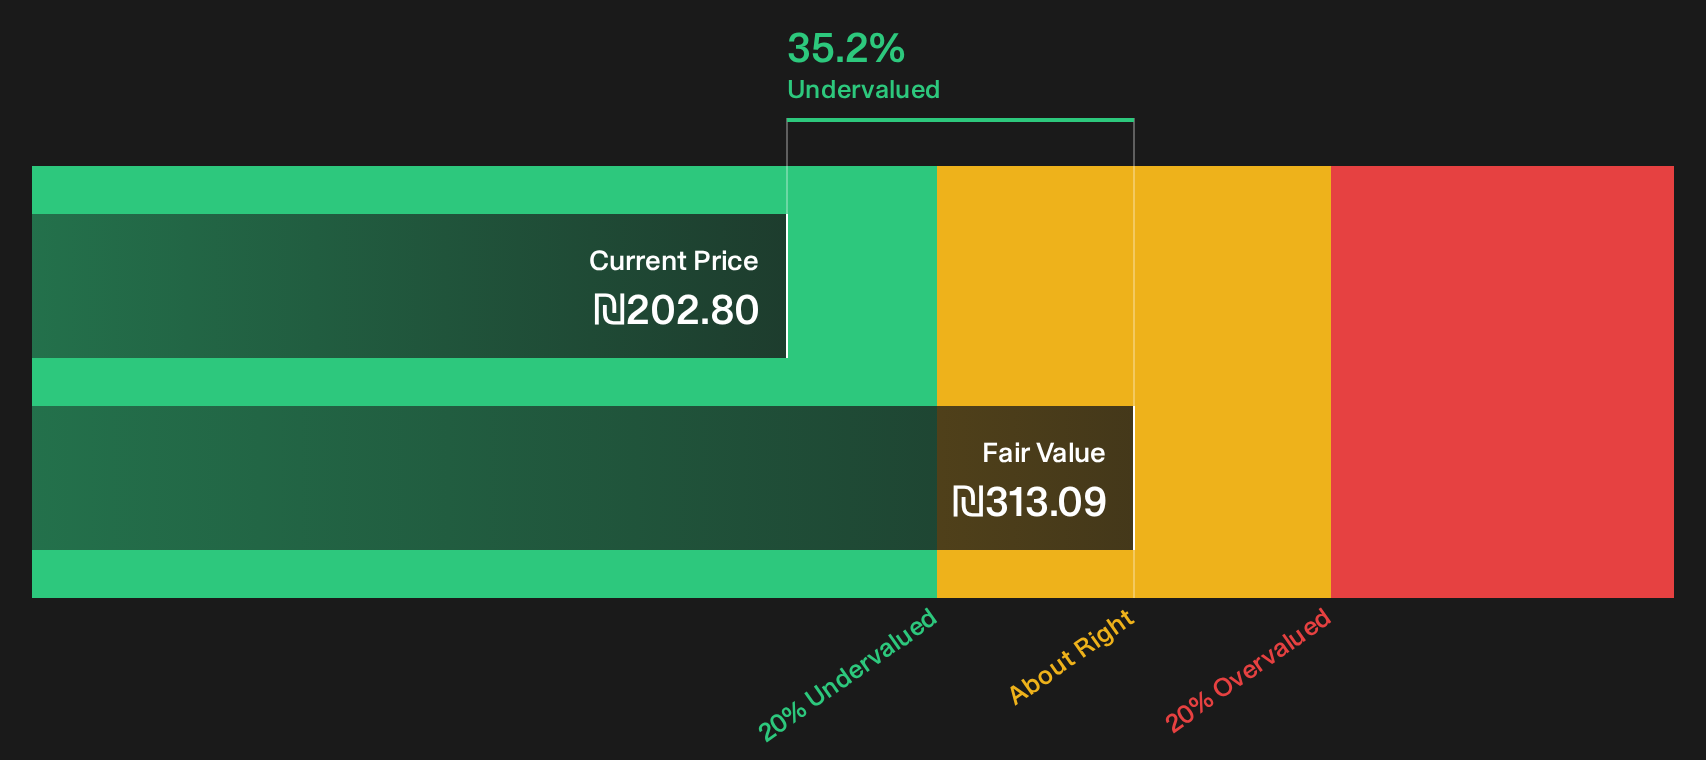
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Delta Galil Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on valuation and future cash flows can feel exciting or uncomfortable, depending on your risk tolerance and time horizon. Act while the information is fresh and test the numbers yourself by weighing the 2 key rewards and 1 important warning sign.
Hunting for more ideas beyond Delta Galil Industries?
If you stop with Delta Galil Industries, you only see one opportunity. Broaden your watchlist and you may uncover setups that fit your goals even better.
- Target potential mispricing opportunities by scanning companies that currently appear cheap on quality and valuation metrics using the 193 high quality undervalued stocks.
- Strengthen your income stream by reviewing stocks that offer higher yields with a focus on payout resilience through the 216 dividend fortresses.
- Dial down portfolio stress by focusing on companies that show sturdier financial footing and lower risk scores with the 205 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com