
Arteris (AIP) Could Be 46% Undervalued After Raising Full Year Revenue Guidance
Arteris (AIP) just paired a fresh earnings update with higher full year revenue guidance, putting the focus on how growing sales and ongoing losses are shaping the stock’s risk profile.
Recent trading reflects that tension between growth and losses. Arteris shares have climbed 29.6% year to date based on share price return, while the 3 year total shareholder return is very large, which suggests that investors have been willing to price in execution risk as guidance and revenue increase.
Compare Arteris’ guidance driven move with other chip and software plays that screen for resilient balance sheets and fundamentals by scanning our curated list of solid balance sheet and fundamentals (23 results) today.
That move leaves Arteris trading well below the average analyst target and at a steep gap to some intrinsic value estimates. Is the current price already fair, or is the market misreading that spread?
Most Popular Narrative: 46% Undervalued
Arteris is framed as undervalued in the analyst consensus Narrative on Simply Wall St, which places fair value at $37.29 versus the last close at $20.19. This view is anchored on AI, chiplet adoption and security focused design activity.
Accelerating adoption of AI and high performance computing workloads in enterprise computing and automotive continues to drive demand for Arteris system IP and NoC interconnects, supported by enterprise computing averaging 29% of ACV plus royalties over the past four quarters and contributing to future licensing and royalty revenue.
See why 6 investors see Arteris as 46% undervalued.
Result: Fair Value of $37.29 (UNDERVALUED)
Still, the Arteris story can change quickly if GAAP losses persist or if volatility and insider selling continue to undermine confidence in the recent guidance reset.
Find out about the key risks to this Arteris narrative.
Another View: What Arteris’ Price-To-Sales Is Telling You
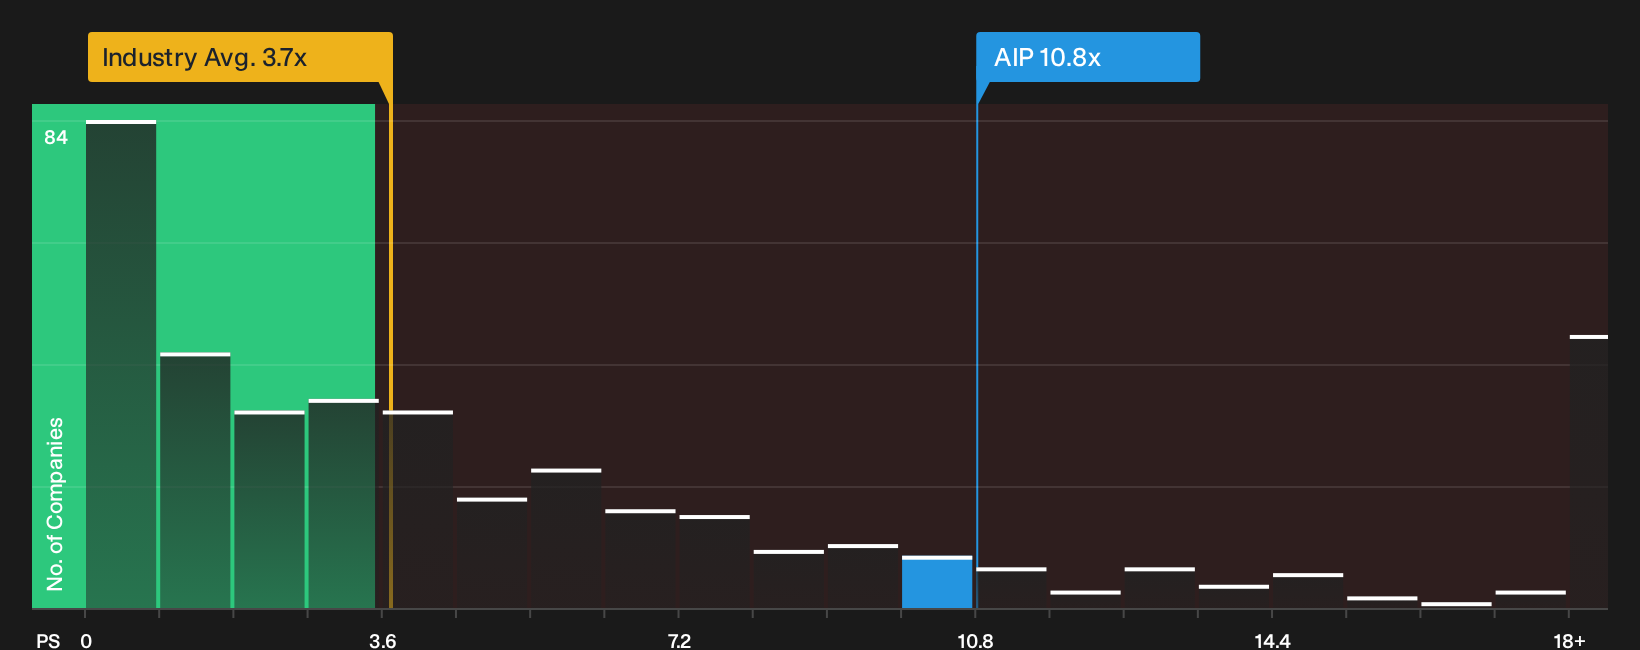
The SWS DCF model points to Arteris trading at a steep discount to estimated future cash flows, yet the P/S ratio tells a different story. At 10.8x sales, the stock is priced at almost 3x the US Software average of 3.7x and over 4x the peer average of 2.5x, while the fair ratio is 4.9x. That gap suggests investors need to weigh upside from growth expectations against the risk that sentiment eventually shifts closer to that lower fair ratio.
To stress test that spread between discounted cash flow value and revenue based pricing, review the valuation breakdown through See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There have been mixed messages so far on Arteris’ valuation and risk profile. If you want to form your own view, you can go directly to the 2 key rewards and 3 important warning signs by checking the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Arteris?
If Arteris has sharpened your thinking on valuation and risk, do not stop here. New opportunities often show up where markets are not paying close attention.
- Zero in on quality at a discount by scanning companies that pass tough fundamentals checks with the 31 high quality undervalued stocks.
- Prioritise resilience by reviewing stocks that score well on stability metrics through the 29 resilient stocks with low risk scores.
- Hunt for potential future leaders by focusing on underfollowed businesses in the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com