
Can Hims & Hers Health (HIMS) Stay Cheap After Its Obesity Deal?
Hims & Hers Health has been a volatile ride for shareholders recently, which puts a fresh spotlight on a simple question for new money coming in. With all the attention on its telehealth model and recent moves in the share price, the real issue is whether the current valuation can be explained by its sales.
- Over the past 5 years, Hims & Hers Health has delivered a total return of 166.3%, which makes it important to ask how much of that journey is now already reflected in what investors are paying for each dollar of revenue today.
- The recent agreement with Eli Lilly to offer branded obesity drugs through the Hims & Hers platform can influence how quickly sales scale in that category and how investors think about the durability of future revenue tied to weight management treatments.
- There is a second opinion on Hims & Hers Health worth weighing. See what analysts think Hims & Hers Health's shares could be worth.
The issue now is whether the current share price, after recent declines and a long run up, is adequately supported by Hims & Hers Health's sales when measured against the Fair Ratio benchmark.
To see how this same question about paying for sales plays out across other healthcare names, compare Hims & Hers Health with a wider set of 35 healthcare AI stocks
Does Hims & Hers Health Look Undervalued on Sales?
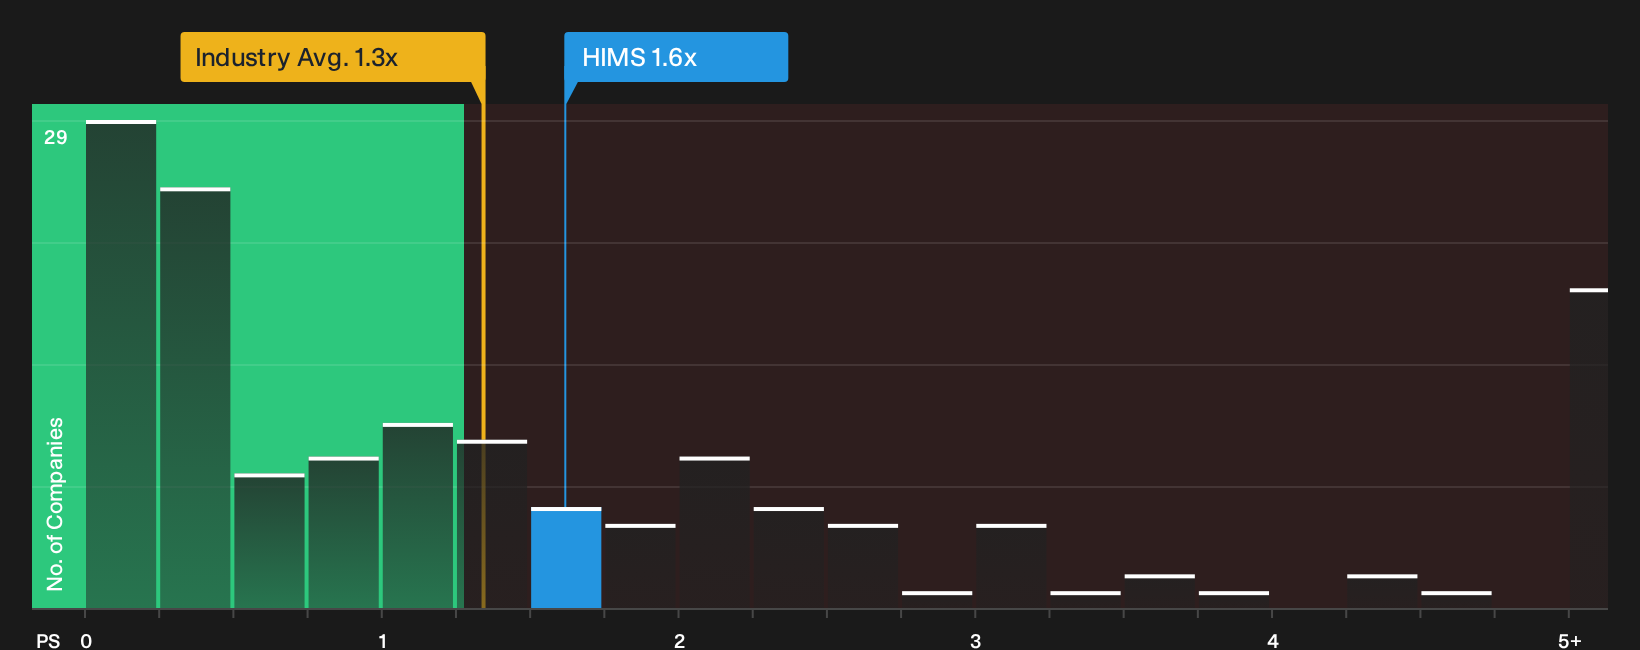
P/S is a useful lens for Hims & Hers Health because investors are primarily paying for its revenue footprint rather than current profits. The stock trades on a P/S ratio of 1.6x, which is slightly above the broader healthcare sector average of 1.3x and well below the 7.5x figure seen across its closer telehealth and digital health peers.
On this framework, the Fair Ratio model, which looks at Hims & Hers Health's growth profile, margins, scale and risk, suggests the current P/S multiple sits below the level implied by those fundamentals, so the shares screen undervalued on sales. Because the recent partnership with Eli Lilly has sharpened attention on the weight management offering and revenue mix, the fact that the P/S ratio remains at a discount to this tailored benchmark may indicate investors are still applying a cautious filter to that opportunity set. Explore the numbers behind Hims & Hers Health's P/S valuation.
The Hims & Hers Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Hims & Hers Health valuation puzzle leaves off and explain which specific paths for growth, margins and earnings would need to occur for the stock to be worth materially more or materially less than it is today on the market. Each narrative ties its number to a concrete view of where growth, profitability and risk could go next, which gives you something to track as fresh information comes through.
One of the top community narratives on Hims & Hers Health: 88% undervalued
According to Deep_Insights, a Simply Wall St Community investor, Hims & Hers Health is building something broader than a single weight loss story.
"The important point is not simply entering new countries. Hims is bringing different categories and both brands to international markets, using its platform…"
Discover why this Narrative puts Hims & Hers Health at 88% undervalued.
One more Hims & Hers Health piece that could change how you see the stock
Before you anchor on any view of Hims & Hers Health, it is worth knowing that Simply Wall St's broader checks have flagged specific risks that deserve a closer look alongside the valuation work you have just read. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com