
UPS Stock And Other Trade Compliance Winners From Mexico Tariff Risk
Tariffs on Mexican imports are back in the headlines, and this time the threat to double duties has real potential to reshape how cross-border trade works. That kind of shock can punish some companies while opening doors for others that help businesses manage customs, compliance and shifting trade rules. This article walks through three stocks exposed to that tariff story and explains why each could matter for your portfolio decision making.
The stocks covered below are just a sample of the tariff and trade-compliance angle. The full screen surfaced 13 more North American customs and trade services companies with equally compelling narratives that are not discussed here. To identify and analyze those additional opportunities directly, head straight into the North American Trade-Compliance and Customs Services screener.
C.H. Robinson Worldwide (CHRW)
C.H. Robinson Worldwide is one of the clearest links between tariff volatility and real-world logistics, and the analyst consensus Narrative on Simply Wall St frames it as a customs-heavy freight broker that could benefit when trade complexity pushes more shippers toward larger, tech-enabled partners.
"Expansion into higher value services, such as secure, high value freight through the DeSpir Logistics acquisition, combined with the Lean AI cost to serve model that targets operating margins similar to NAST, can support future mix improvement, higher gross profit per load and stronger overall earnings."
What happens if a single assumption about how effectively that AI-led model converts tariff-driven complexity into higher quality earnings starts to shift?
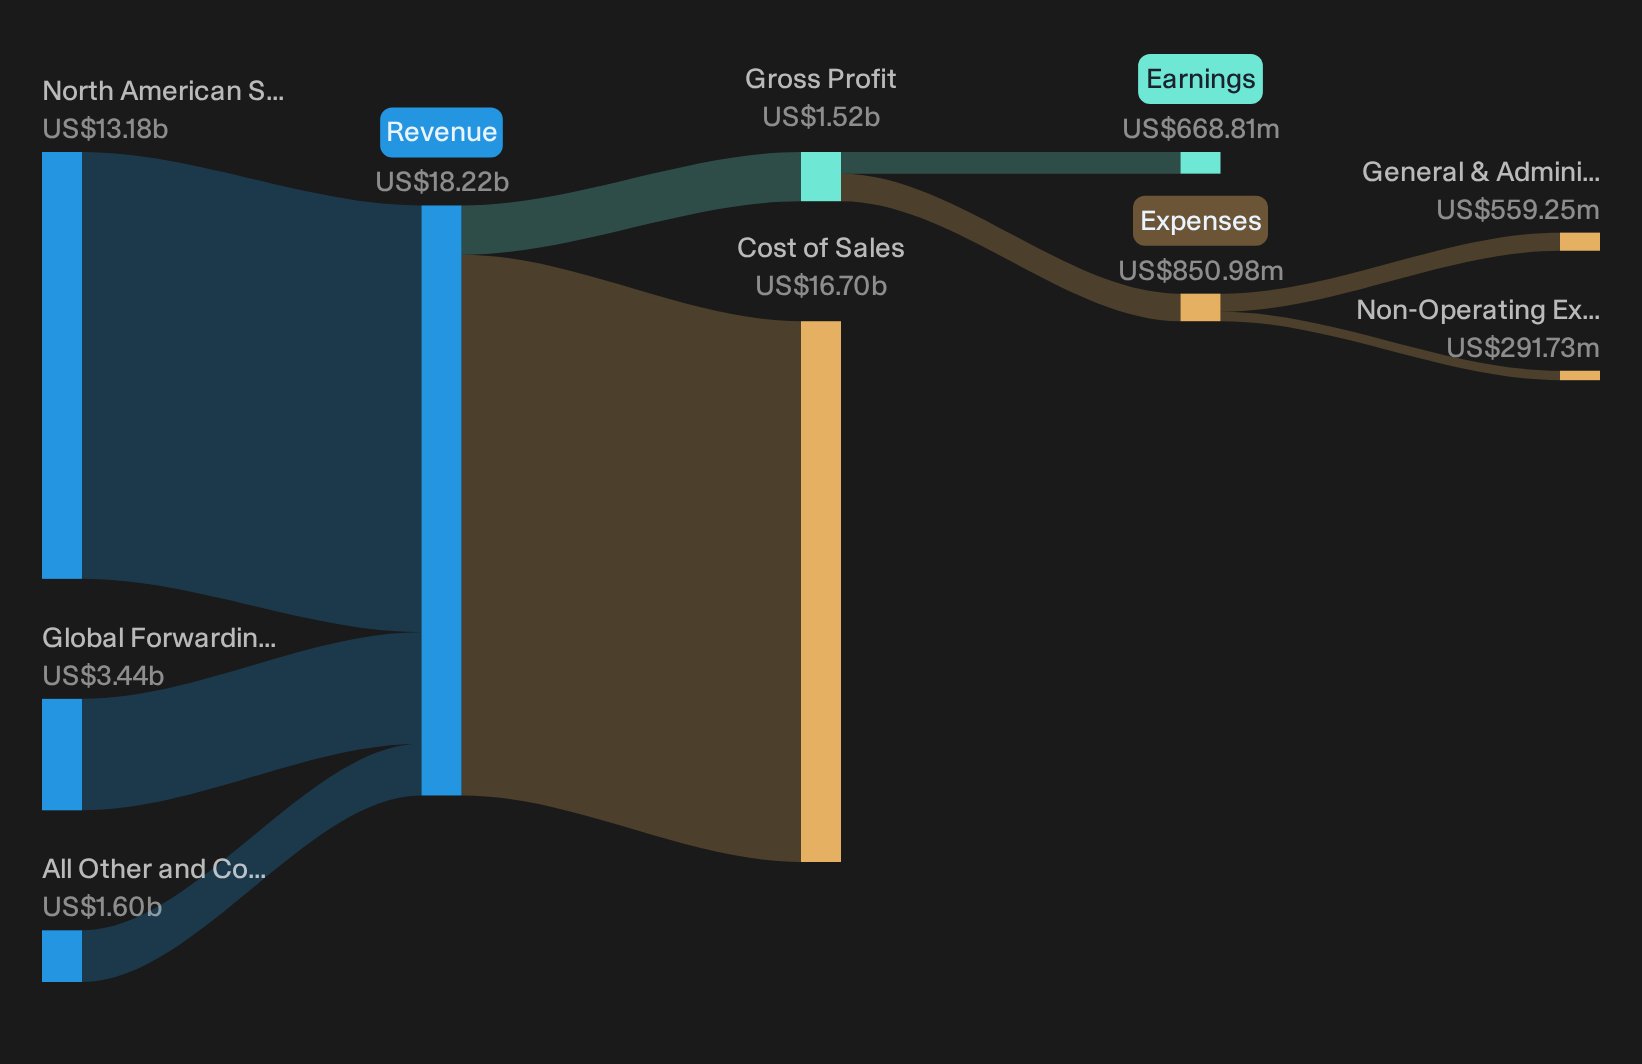
C.H. Robinson Worldwide runs a broad freight and customs brokerage platform that fits cleanly with the trade-compliance screener, with about US$13.2b of revenue from North American Surface Transportation, US$3.4b from Global Forwarding, US$1.6b from other activities, and a market value near US$15.5b.
If that conversion risk is on your mind, read the full narrative for C.H. Robinson Worldwide to see how tariff complexity, mix shift and capital discipline might be decoupling beneath the surface.
United Parcel Service (UPS)
United Parcel Service plugs directly into the trade-compliance theme, since its parcel network is wrapped around customs brokerage, freight forwarding and tariff planning that become more valuable when U.S.–Mexico rules shift. The analyst consensus Narrative on Simply Wall St captures how management is trying to tilt that network toward richer, more resilient flows.
"United Parcel Service is moving further away from low-yield Amazon volumes after completing the Amazon glide down that removed about 2 million low-quality pieces per day and reduced related expenses by about US$4.5b, which directly supports higher net margins and operating profit."
What really matters now is how one unresolved cost and pricing pressure shapes the payoff from that higher quality volume mix.
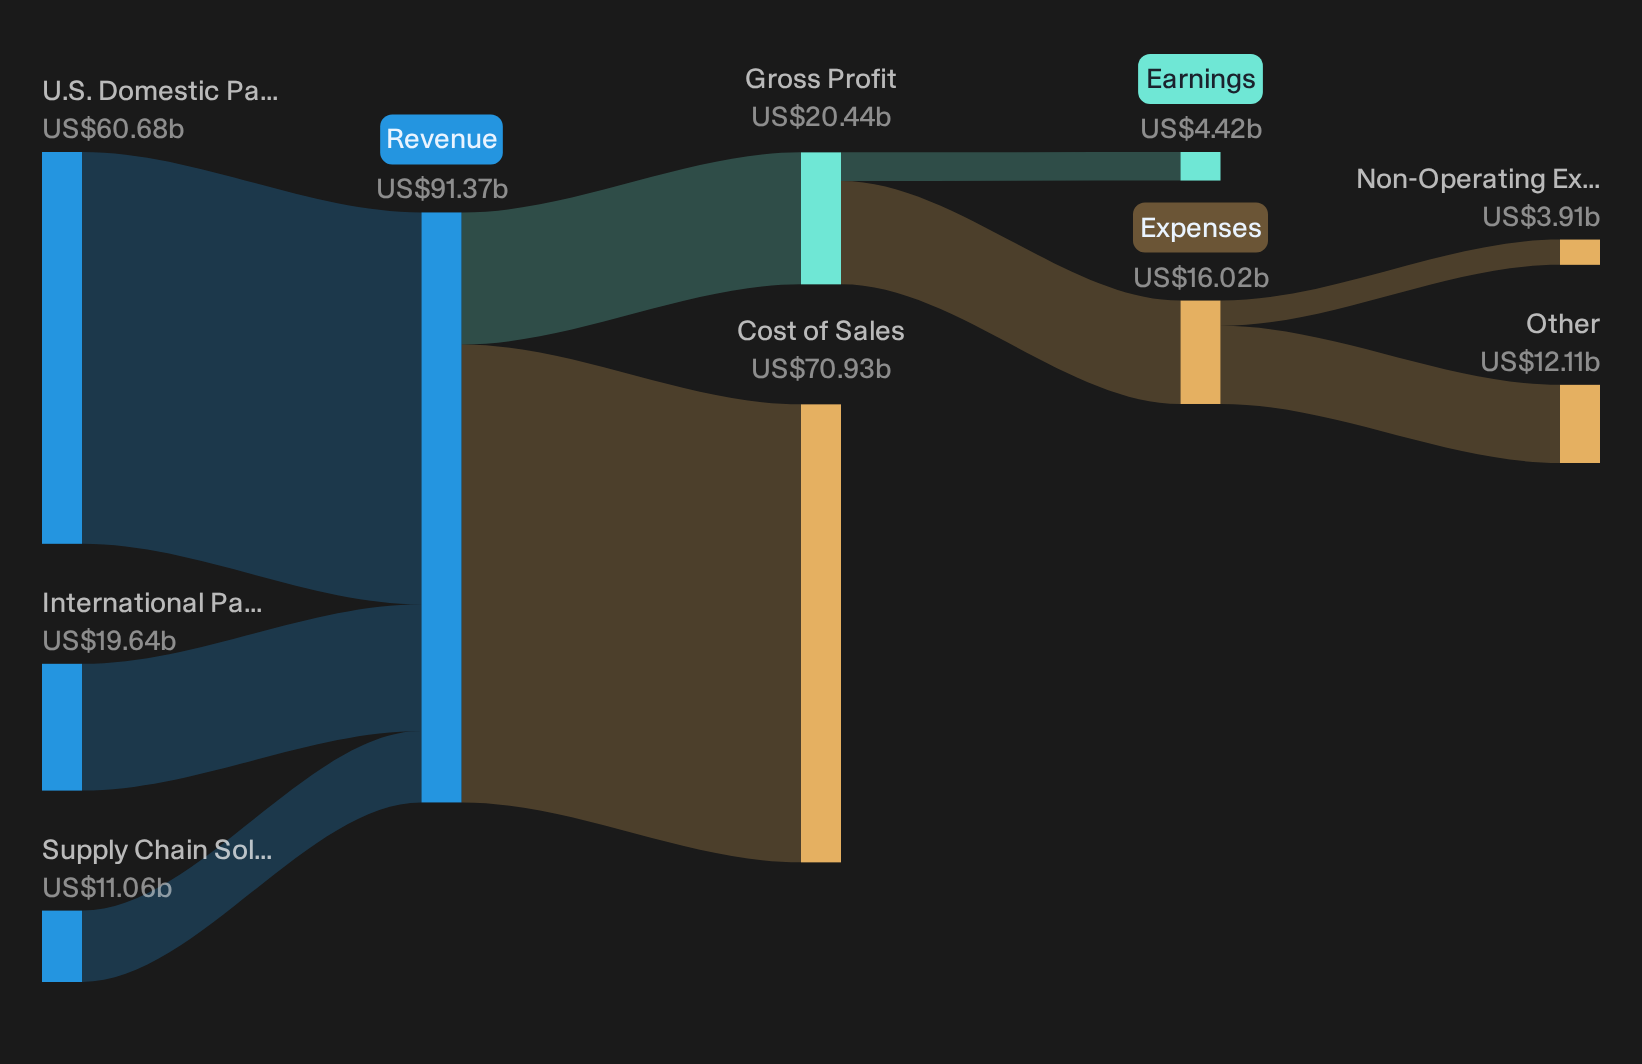
United Parcel Service runs a global delivery and logistics network that handles everything from domestic parcels to cross-border freight, customs brokerage and post-sales services, with most revenue from U.S. Domestic Package at about US$60.7b, plus US$19.6b from International Package and US$11.1b from Supply Chain Solutions, and a market value around US$95.7b.
That cost and pricing pressure is exactly where the story gets interesting, so read the full narrative for United Parcel Service to see whether UPS is quietly rebuilding earnings power.
Landstar System (LSTR)
Landstar System plugs straight into the customs and trade-compliance story, because its asset light freight network leans heavily on U.S.–Mexico and U.S.–Canada cross-border shipments where tariff changes can quickly shift routing decisions. The analyst consensus Narrative on Simply Wall St argues that one freight niche is already starting to reshape that opportunity.
"Robust growth in infrastructure related and data center freight, supported by heavy haul revenue of about US$134 million in Q1 2026 and US$164 million in Q2 2026 with double digit year over year gains in both quarters and a rising share of unsided and platform freight, continues to support the case that Landstar System can lift revenue per load and future earnings."
What happens if a single assumption about how efficiently that heavy freight engine supports margins under a more protectionist tariff regime starts to move?
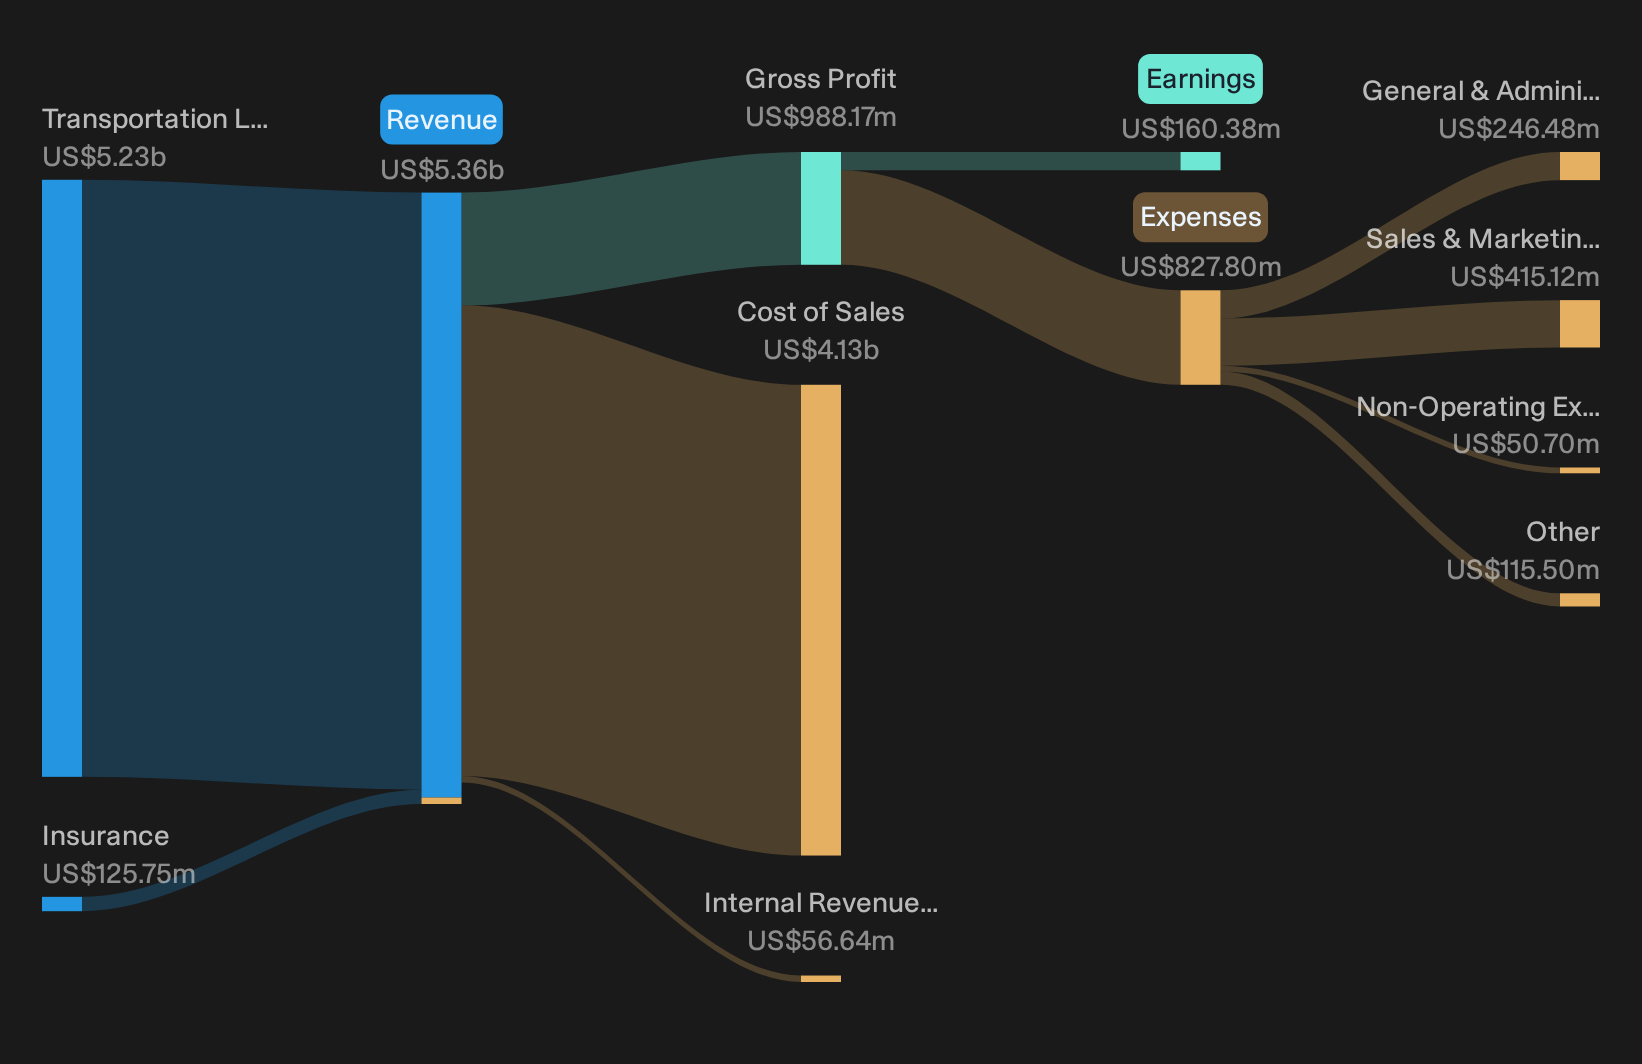
Landstar System runs transportation management and related insurance services across North America, with customs-linked cross-border freight built into its offering. It generates about US$5.2b from Transportation Logistics and roughly US$126 million from Insurance, and carries a market value near US$5.0b.
If that tariff shock scenario is on your radar, read the full narrative for Landstar System to see whether Landstar System is quietly building an accelerating cross border earnings engine.
Curious About What You Might Be Missing?
Fresh opportunities can move from quiet to flying fast. Use that first mover advantage before these ideas get fully caught by the crowd and priced in, and consider acting early.
- Explore early momentum shifts in smaller companies that already generate profits by scanning the 41 profitable AI stocks that aren't just burning cash while they are still under the radar.
- Review the 6 dividend fortresses to find ideas focused on cash flow and payouts before yields change and more capital moves into the same names.
- Screen the list of solid balance sheet and fundamentals (23 results) to identify companies with resilient balance sheets that are designed to handle shocks while current valuations and expectations remain in place.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com