
JD.com (JD) Stock May Trade Below Fair Value As EU Deal Nears Close
JD.com has seen its stock travel a long and uneven path, and that record now puts a sharper spotlight on whether today's share price is adequately supported by the company's earnings power. With fresh headlines on acquisitions and new technology tools, investors are increasingly asking how much of JD.com’s current valuation is justified by what the business actually earns.
- Over the past 5 years the stock has fallen 64.5%, which puts the current valuation debate squarely on whether the earnings profile can support a long term recovery case.
- The conditional EU approval of JD.com’s planned US$2.5b purchase of Ceconomy may reshape how investors think about future profit margins and capital needs in its European expansion.
- Your read on JD.com is one view; the desks covering it have another. See what analysts think JD.com's shares could be worth.
For investors, the debate is whether JD.com's current share price is justified by its earnings when judged against the Fair Ratio benchmark.
If you are considering whether JD.com's current price fairly reflects its earnings strength, it can help to compare that question across 31 high quality undervalued stocks that clear similar quality hurdles.
Does JD.com Look Undervalued on Earnings?
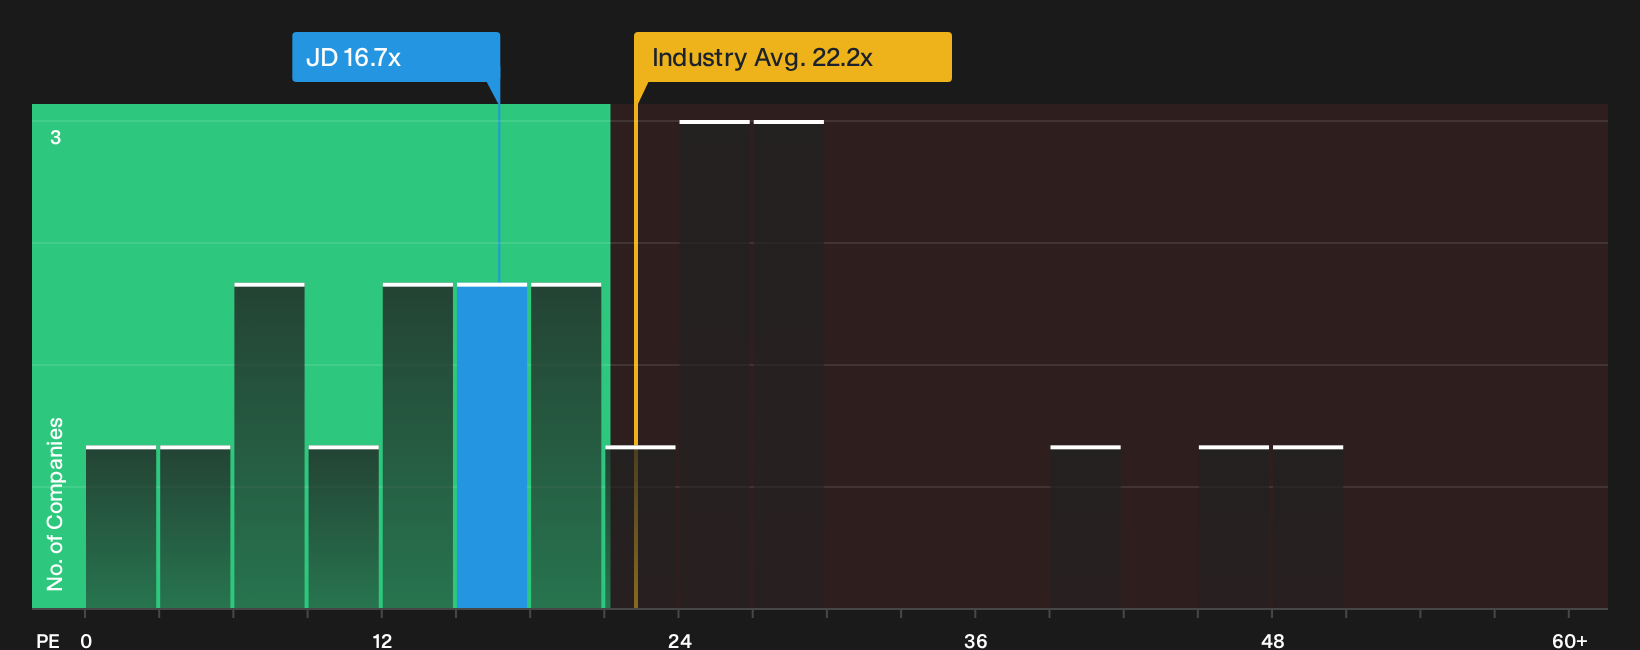
A P/E yardstick fits JD.com because earnings are a key focus for retailers that reinvest heavily while still reporting positive profits. On this measure, the stock trades on a P/E of 16.7x, which sits below the Multiline Retail industry average of 20.0x and also under the broader peer group on about 24.7x. The Fair Ratio, which looks at JD.com’s own growth profile, margins, size and risk, suggests the current P/E is on the low side rather than stretched.
Because the Ceconomy deal adds questions around future capital needs in Europe, the relatively lower earnings multiple means the market is not paying a premium for that expansion story. Despite headlines around AI tools and international partnerships lifting interest in JD.com, the P/E still prices the stock at a discount to both its industry and peers, which points to investors needing to weigh whether the concerns that explain that gap are fully justified. Explore the numbers behind JD.com's P/E valuation.
The JD.com Narrative: What Would Justify Today's Price?
Simply Wall St Narratives picks up where the JD.com valuation puzzle leaves off by spelling out which expectations for future growth, profitability and earnings would need to prove right for the stock to be worth materially more or less than it is today. Each storyline links its implied number to a clear view on where JD.com's expansion, margin profile and risk balance could go next, and gives you something you can return to as fresh information comes through.
Bulls see JD.com as underappreciated for its margin and AI ambitions, while bears focus on execution risk and pressure on new business profitability.
Bull case: 29% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which ties JD.com’s upside to earnings power and disciplined investment.
"The main thing that has to go right is that JD.com continues to expand margins in JD Retail and newer services such as logistics and food delivery..."
Discover why this Narrative puts JD.com at 29% undervalued.
Bear case: 5% overvalued
The bearish analyst Narrative on Simply Wall St argues that JD.com’s heavier spending and competition could limit the payoff from those same projects.
"JD.com's heavy investment in food delivery and other new businesses is leading to widening operating losses in these segments, with non-GAAP operating loss in new business reaching RMB 14.8 billion this quarter..."
Explore why this Narrative puts JD.com at 5% overvalued.
One more crucial piece for the JD.com puzzle
Valuation only tells you what the market is willing to pay today, while analyst projections sketch where the business could be several years from now and give you a completely different lens on JD.com. Explore where analysts expect JD.com to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com