
Will Strong Earnings Results Change Parex Resources Stock Narrative
- Parex Resources reported third quarter 2026 revenue of US$549.07 million and net income of US$75.26 million, with basic earnings per share from continuing operations of US$0.78.
- Across the first nine months of 2026, Parex Resources recorded US$1.15 billion in revenue and US$524.14 million in profit, highlighting how recent operations converted into higher earnings per share from continuing operations.
- This article examines how Parex Resources' year-to-date earnings per share may influence the investment narrative investors had previously considered.
Parex Resources Investment Narrative Recap
To own Parex Resources, you need to be comfortable with a Colombia focused oil producer that is trying to turn a larger reserve base into steady cash generation. The analyst consensus narrative on Simply Wall St assumes the business keeps converting Ecopetrol partnerships, LLA-111 drilling and the Frontera deal into sustainable output while holding cost pressure in check. The latest earnings show strong accounting profits, yet the short term hinge still looks operational, with the focus on keeping production on track without letting unit costs creep higher.
The biggest risk right now remains margin pressure in Colombia. Higher operating costs, El Niño related effects, currency strength or wider Vasconia differentials could quickly bite into those earnings. Nonrecurring charges and a dividend that is not well covered by free cash flow add another layer of risk. The new results do not remove these issues, they instead give management a little more room to work with if conditions worsen.
The most relevant recent data point for this story is the nine month 2026 result. Parex Resources booked US$1.15b in revenue and US$524.14 million in net income over that period, with basic EPS from continuing operations of US$5.45. That level of profitability, on the back of Colombian assets, connects directly to the catalysts around reserve growth, Ecopetrol partnerships and low cost drilling inventory.
This earnings print also sits beside a share count that has already been reduced materially over six years and a dividend yield around 6.5%, according to John Stephenson’s comments. Together, these factors frame the near term debate. Strong cash generation and a high payout can support the current shareholder story if production guidance and reservoir recovery plans keep working. Any sustained squeeze on margins or capital needs could put that balance under strain.
What The Current Forecasts Assume For Parex Resources
Parex Resources' analyst narrative ties together several moving parts. Revenue is assumed to rise at about 14.5% a year over the next three years, while profit margins compress from 43.6% today to 12.2% in 2029. On that view, earnings are projected to be US$251.9 million by 2029 compared with US$599.0 million today, with a spread of expectations that runs from US$213.4 million at the low end to US$292.2 million at the high end.
Parex Resources is also modeled to retire a small amount of equity, with the share count expected to edge down 0.06% a year. To make sense of those earnings against today’s valuation, analysts apply a discount rate of about 6.6% and land on a future P/E multiple of 9.8x on the 2029 earnings estimate. That compares with an indicated 2.2x P/E today and a sector reference point of 17.5x for the wider Canadian oil and gas group.
For anyone tracking the story, the gap between current and projected profitability is important. Profit margins are expected to be much thinner even if revenue moves higher, which means more volume and more activity would convert into a smaller slice of net income. That tilt puts more weight on operational discipline around costs, differentials and nonrecurring items if the analyst path is to hold.
Parex Resources' current analyst framework points to revenues of US$2.1b and earnings of US$251.9 million by 2029, built on an assumed 14.5% yearly revenue growth rate and an earnings decline of US$347.1 million from US$599.0 million today.
Uncover how Parex Resources' fair value indicates a 44% potential upside to its current price before the discount closes.
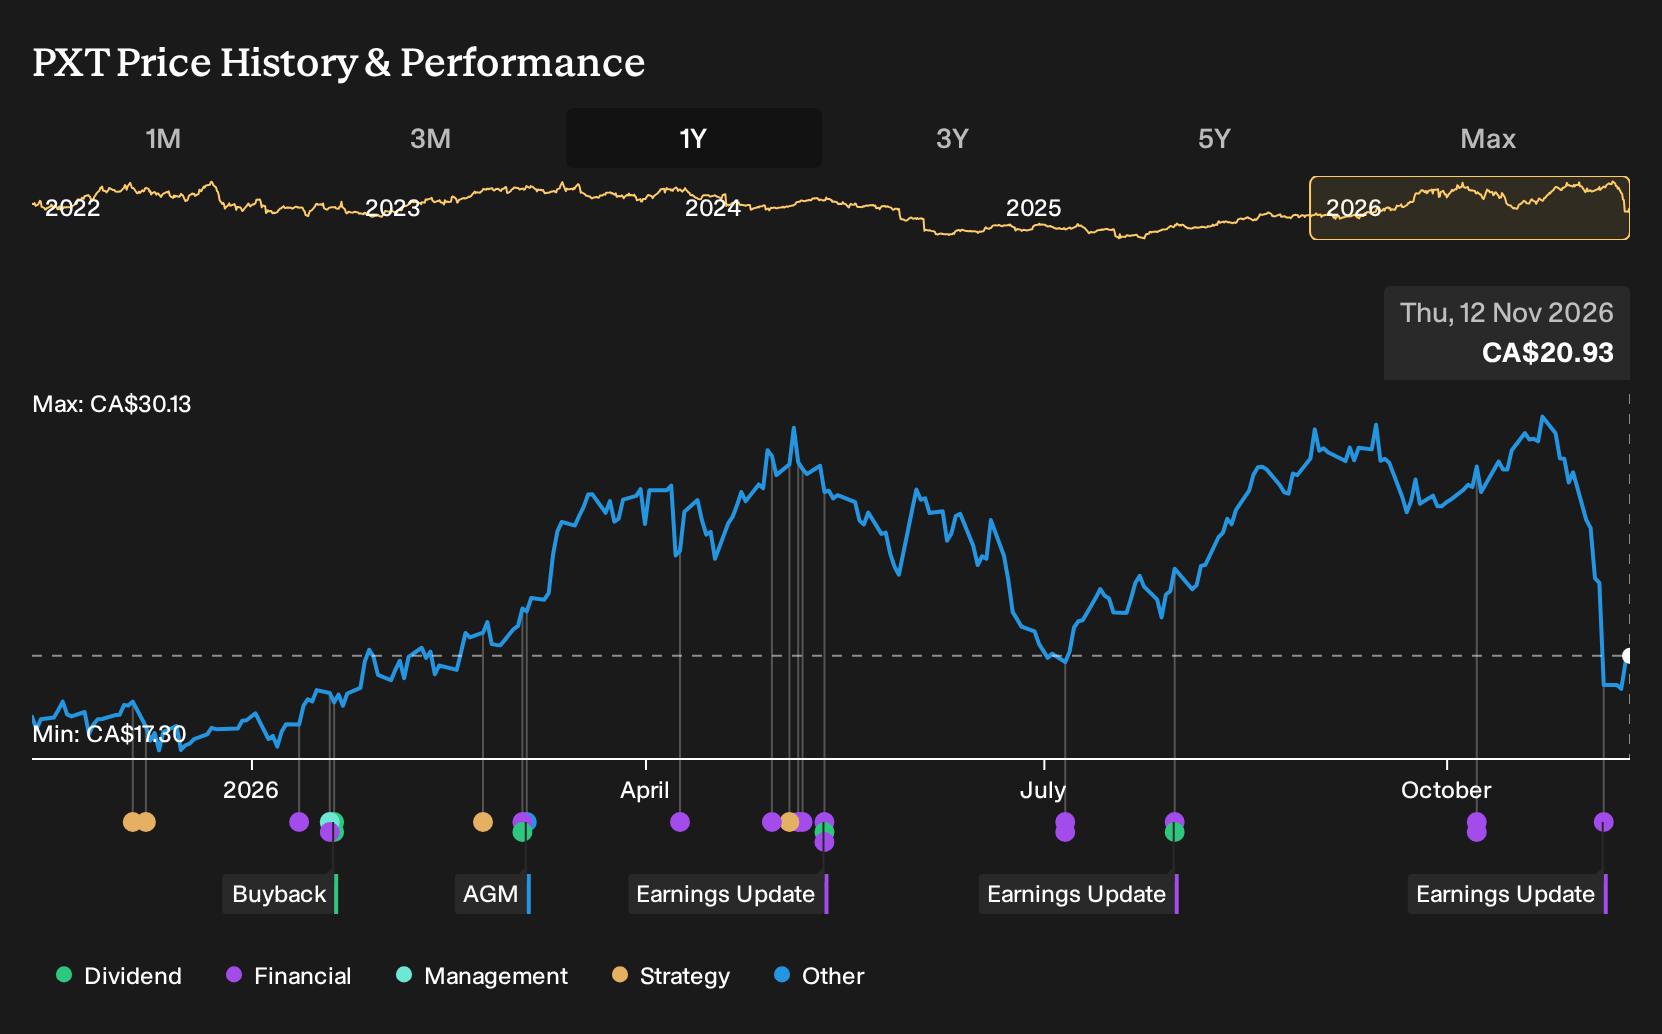
Exploring Other Perspectives
You might see the latest Parex Resources earnings and focus on headline profit, but the more bearish analysts lean hard on integration risk from the Frontera deal. They were pencilling in about US$2.0b of 2029 revenue and US$204.1 million of earnings. That is far below consensus and could shift again as you reassess these new numbers.
Explore 5 other Parex Resources fair value estimates, including one that suggests it could be worth just CA$25.50!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Parex Resources research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Parex Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Parex Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond Parex Resources?
If Parex Resources has sharpened your focus on cash generation and balance sheet strength, it can be useful to compare it with other potential opportunities. The Simply Wall St screener helps you quickly filter for different types of businesses so you can build a watchlist that matches your own approach rather than relying only on consensus views.
- For investors who care about resilient balance sheets and solid fundamentals, start with this curated list of solid balance sheet and fundamentals (5 results) to see which companies align with that profile.
- If you want income potential backed by robust financials, scan the 3 dividend fortresses and see which payouts might fit your risk tolerance.
- Those hunting for underfollowed opportunities with strong metrics can review the 8 high quality undiscovered gems and compare them against what you see in Parex Resources.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com