
Why Is Prologis (PLD) Rewriting The Economics Of New Warehouse Development?
- Prologis (NYSE:PLD) research argues industrial rents must rise materially for new warehouse development to make financial sense.
- The report cites expanding demand from data center and advanced manufacturing tenants, beyond traditional logistics users.
- Prologis researchers point to ongoing supply constraints and project tighter vacancies and higher rents through 2027.
- The new finding that rents must climb for projects to pencil in only covers part of what matters for Prologis. Our analysis turns up 2 warning signs (1 major) for Prologis as well.
Broader demand for logistics, data center and advanced manufacturing facilities is reshaping warehouse economics and puts related real estate and infrastructure stocks in focus through 53 AI infrastructure stocks.
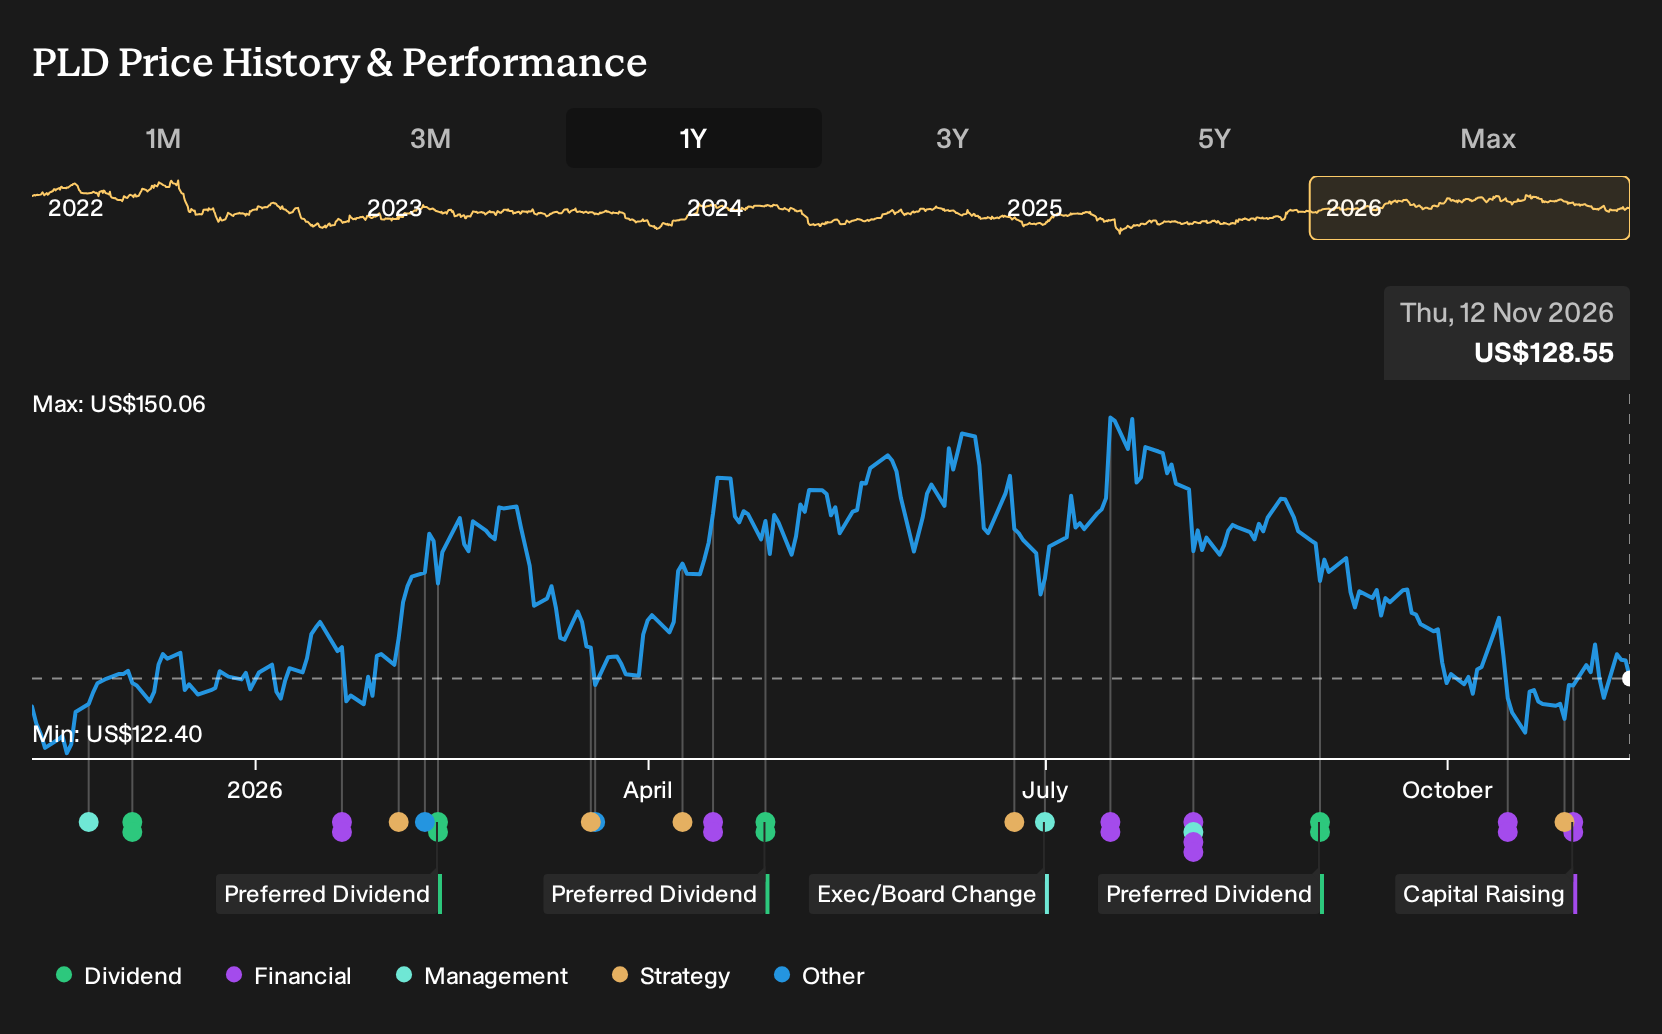
Prologis is a US-based industrial REIT with a reported market value of about $126.1 billion that focuses on large-scale warehouse and logistics facilities, which are increasingly intersecting with demand from data center and advanced manufacturing users that need similar power, location, and space characteristics.
See which insiders are buying and selling Prologis following this latest news.
Rising replacement rents cut both ways for the Prologis story
The Narrative around Prologis is built on the idea that constrained supply and replacement-cost gaps let the REIT harvest higher rents while feeding an integrated development and data-center platform. This new rent research goes straight at that premise because it spells out how much pricing power future projects may need.
"Limited new construction relative to pre COVID levels, a roughly 17% in place lease mark to market and a further gap to replacement cost rents position Prologis to benefit as leases reset over time..."
See how the full story points towards a $153 fair value for Prologis.
This research directly supports the catalyst that Prologis can capture embedded rent uplift as older leases reset closer to replacement levels. It also lines up with the Narrative’s focus on data centers and advanced manufacturing as extra demand, alongside peers like Rexford Industrial and Segro, that can justify more power-heavy, infrastructure-rich warehouses.
There is pressure on a different part of the story though. If new development only works at materially higher rents, the at-the-market equity program and any large projects need to clear a higher hurdle, or dilution risk becomes more visible relative to the rewards. Analysts have already flagged that equity issuance is a key risk and this research keeps that front and center.
To make sense of news like this, you need a clear view on which long-term path you think Prologis is actually on, which is exactly what a structured Narrative is trying to map out.
What picture do long range forecasts paint for Prologis a few years from now?
Short term headlines only cover rent debates and project math. In contrast, the longer range models point to a very different destination for this REIT a few years out. See where analysts expect Prologis to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com