
Is Kainos Group (LSE:KNOS) Cheap As Earnings Beat And Guidance Hold Up?
Why Kainos Group’s latest earnings and guidance matter for investors
Kainos Group (LSE:KNOS) just paired a first half earnings beat with fresh guidance that points to revenue in the second half of fiscal 2027 tracking in line with market expectations.
That backdrop helps explain why Kainos Group’s share price has climbed 13.71% over the past 90 days, yet still sits 13.56% lower on a 1 month share price return basis, with a 1 year total shareholder return of 16.26% and a 5 year total shareholder return that is down 32.14%.
Scan how Kainos Group compares with other software and IT service stocks by hunting through a hand-picked set of 5 high quality undiscovered gems after this earnings beat and guidance update.
Kainos Group has just paired a sharp half year earnings beat with a pullback in the share price over the past month. Does that set up a better entry now, or is patience on valuation still the smarter move?
Most Popular Narrative: 10.7% Undervalued
The analyst consensus Narrative on Simply Wall St puts Kainos Group’s fair value at £12.35 per share, compared with the latest close at £11.03. This implies a discount in the valuation model based on a 9.79% discount rate and analyst growth and margin forecasts.
Deepening product collaboration with Workday, including exclusive resale of Pay Transparency and participation in the Clear Skies initiative, is described as expanding addressable markets and supporting sustained double digit ARR growth, which in turn is expected to drive higher software led revenue and operating leverage.
See why 22 investors see Kainos Group as 11% undervalued.
Result: Fair Value of £12.35 (UNDERVALUED)
Still, parts of the Kainos Group story could flip the current undervalued narrative if Workday related products scale faster than expected or if North American growth materially reshapes margins.
Find out about the key risks to this Kainos Group narrative.
Another view on Kainos Group’s valuation
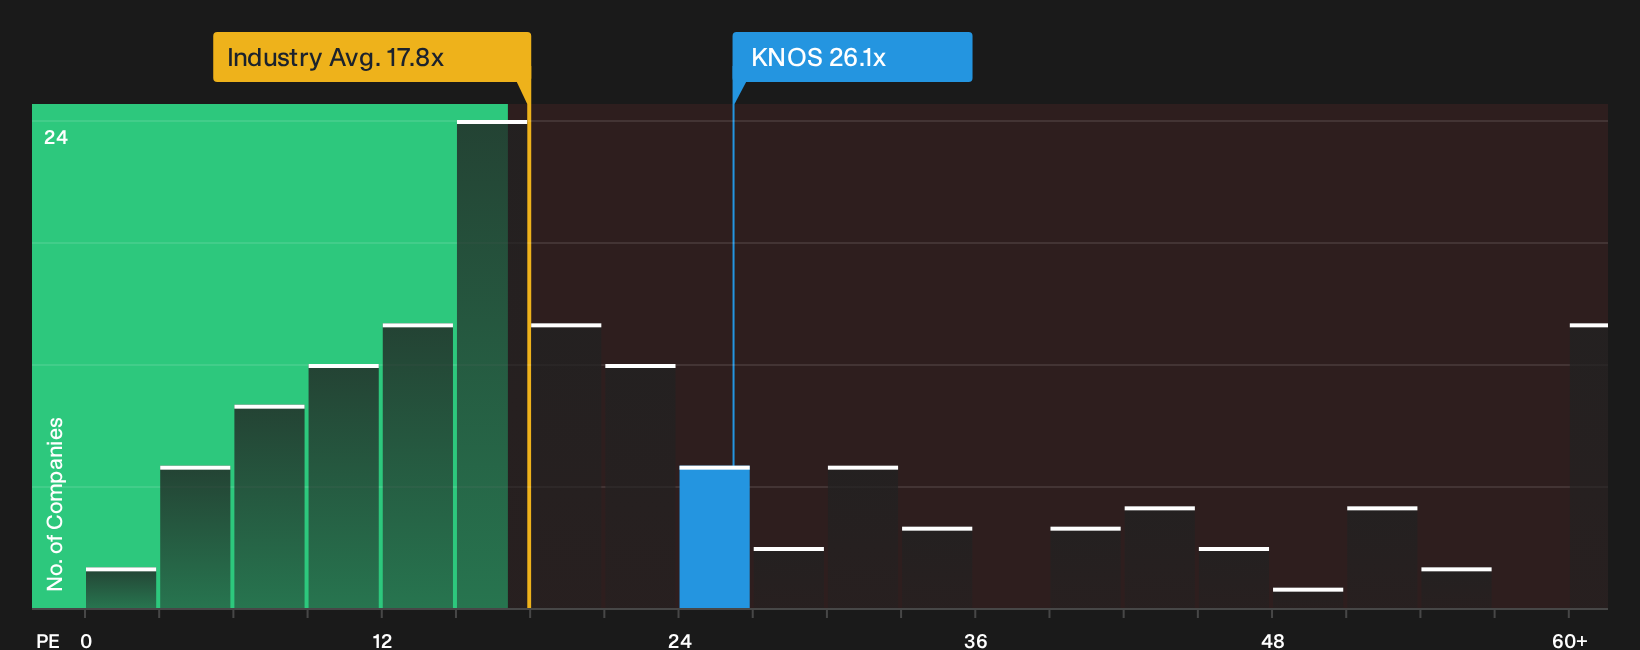
The fair value narrative paints Kainos Group as undervalued, yet the current 26.1x P/E tells a more cautious story. That multiple sits above the European IT sector on 17.8x, although it sits below both the peer average of 30.6x and a fair ratio estimate of 32.2x.
In practice, that mix suggests investors are already paying a premium to the wider industry, while still leaving headroom if sentiment moved closer to peers or the fair ratio. The key question is whether you see that gap as a valuation cushion or as extra risk if growth expectations fade.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages across valuation, price moves and guidance do not need to leave you on the fence. Act while the numbers are fresh and build your own stance, then pressure test that view against the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Kainos Group?
If Kainos Group has sharpened your focus on quality, keep that momentum going by scanning other opportunities that match your risk tolerance, time horizon and income needs.
- Target resilient balance sheets and solid fundamentals by running your own filter across a list of solid balance sheet and fundamentals (9 results).
- Hunt for mispriced opportunities with strong financial quality by checking out a curated set of 15 high quality undervalued stocks.
- Build a portfolio that aims for income plus staying power by reviewing a focused group of 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com