
Amcor (AMCR) Reported Mixed First Quarter Results, Is The 12% Upside Still There?
What Amcor’s Mixed Quarter Means For Shareholders
Amcor (AMCR) just posted first quarter results with sales of US$6,129 million and net income of US$242 million, while also lifting its quarterly dividend to US$0.66 per share.
Investors have seen some swings around Amcor recently, with the 1 day share price return declining 1.77% and the 7 day share price return down 8.47%. This comes even though the 30 day share price return is up 6.76% and the 1 year total shareholder return sits at 11.98%.
Capitalize on the mixed reaction to Amcor’s results by comparing it with packaging peers that combine resilient cash flows and sturdier balance sheets in our hand picked list of solid balance sheet and fundamentals (23 results).After Amcor’s choppy share price reaction and a longer term record that is not one way up, the key issue now is simple: Is most of the easy upside already priced in, or is there still meaningful value on the table?
Most Popular Narrative: 12% Undervalued
On Simply Wall St, the analyst consensus Narrative estimates Amcor’s fair value at $50.18, above the last close of $44.39. This frames the current price as leaving some headroom if those assumptions hold. That view rests on a detailed set of revenue, margin and cash flow forecasts that are discounted at 7.69%.
The plan to recover more than US$500 million of working capital over the next 12 months and to use a portion of an expected US$2.5b of free cash flow in the following 12 month period for roughly US$1b of debt reduction supports lower interest expense and more flexibility for earnings accretive capital allocation.
Refinement of Amcor’s commercial model, including the ability to pass through around US$280 million of resin inflation within shortened pricing lags and with only 4% to 5% of resin sourced from more volatile regions, can continue to protect net margins and earnings from raw material swings.
See why 43 investors see Amcor as 12% undervalued.
Result: Fair Value of $50.18 (UNDERVALUED)
Still, if organic volumes stay weak or Berry integration synergies fall short of the US$650 million target, the current Amcor narrative could come under pressure.
Find out about the key risks to this Amcor narrative.
Another View: What Multiples Say About Amcor
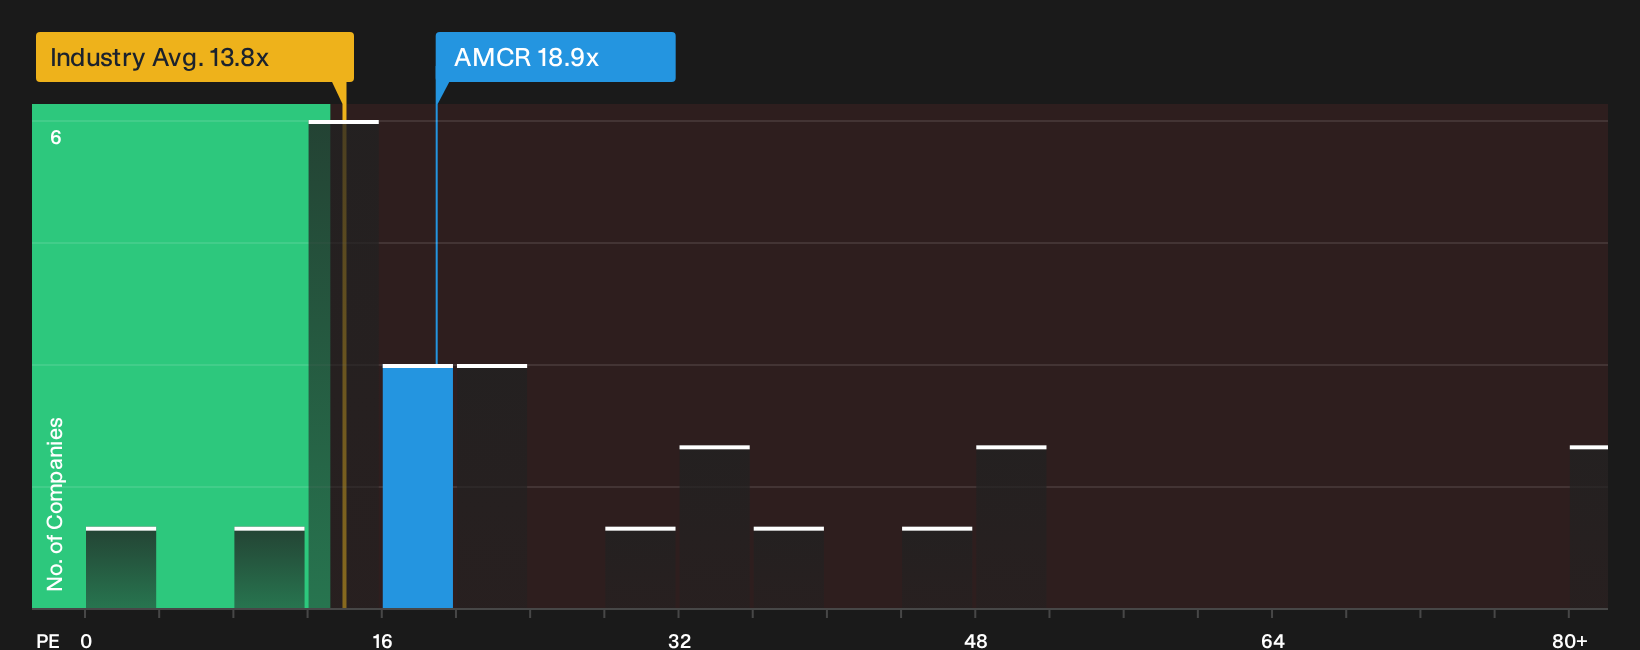
Amcor might look 12% undervalued against the $50.18 fair value in the analyst narrative, yet its 18.9x P/E is higher than the 13.8x Packaging industry average and below the 20.1x fair ratio. That mix can mean less room for error. Which signal should carry more weight for you?
See what the numbers say about this price in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages around Amcor’s valuation and fundamentals can either paralyze you or push you to look closer at the data yourself and move quickly. To weigh both the concerns and the potential upside directly, start with the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Amcor?
Do not stop at Amcor. Fresh ideas often come from comparing it with other businesses that have different strengths, dividend profiles, and risk levels.
- Hunt for mispriced opportunities that combine solid fundamentals with appealing valuations through our curated set of 32 high quality undervalued stocks.
- Focus on income by shortlisting companies that aim to offer stronger yield support and more consistent payouts using the 6 dividend fortresses.
- Dial down potential downside by filtering for companies that score better on financial resilience and risk using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com