
Does Raised 2026 Guidance Change The Bull Case For BioCryst Pharmaceuticals (BCRX)?
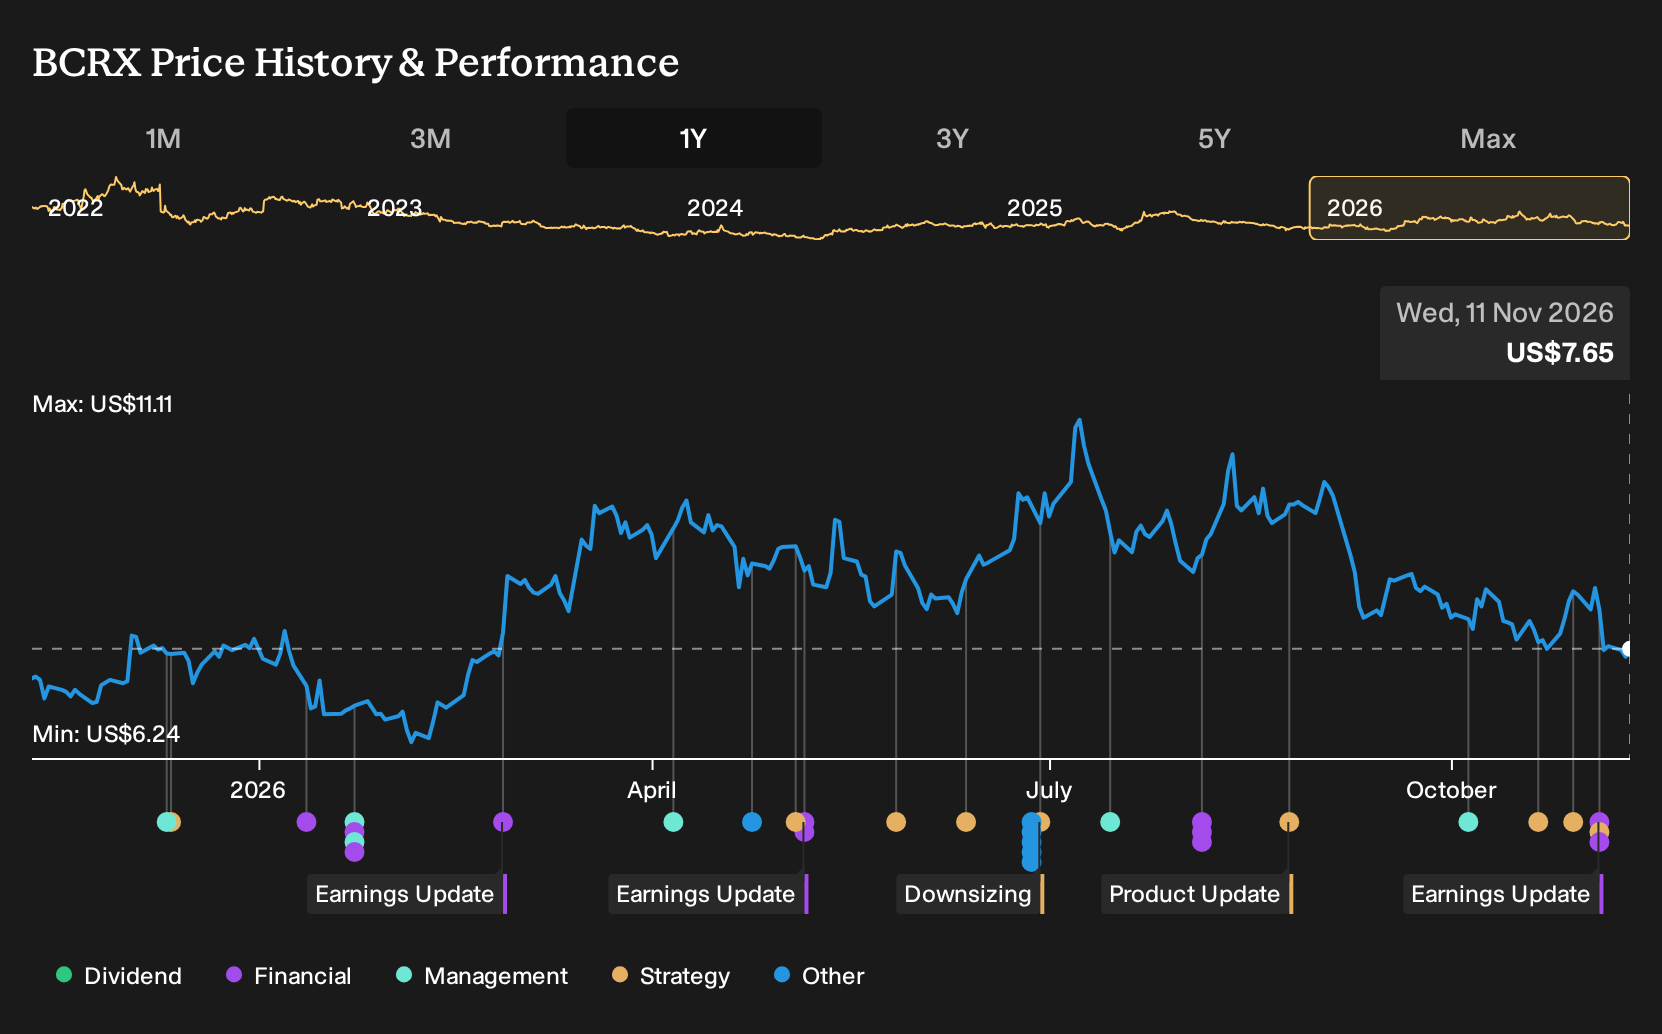
- BioCryst Pharmaceuticals raised its full year 2026 total revenue guidance to a range of US$715 million to US$730 million, alongside reporting third quarter revenue of US$180.29 million, net income of US$37.92 million, and a US$9.54 million long lived asset impairment.
- The higher outlook, supported by Orladeyo driven commercial performance, increased international partner orders, and licensing revenue, comes as BioCryst prepares to showcase new hereditary angioedema data for Orladeyo and investigational navenibart at the 2026 ACAAI meeting.
- This article examines how BioCryst Pharmaceuticals' raised 2026 revenue guidance may influence the investment narrative around its hereditary angioedema franchise.
Scan beyond BioCryst Pharmaceuticals and compare its hereditary angioedema story with other potential breakout healthcare plays on our curated list of 37 healthcare AI stocks.
BioCryst Pharmaceuticals Investment Narrative Recap
To stay on board with BioCryst Pharmaceuticals, you need to believe in the hereditary angioedema plan laid out in the analyst consensus Narrative on Simply Wall St, with Orladeyo as the commercial engine and navenibart as the potential second pillar. The raised 2026 revenue guidance and profitable third quarter support that operating story in the near term.
The biggest short term swing factor is execution around hereditary angioedema, including continued paid uptake and clean safety and efficacy readouts for navenibart. The long lived asset impairment and reliance on less repeatable items like license revenue highlight the key risk that profitability could soften as those one off supports normalise.
The most relevant recent update is that BioCryst Pharmaceuticals is presenting four hereditary angioedema abstracts at the 2026 ACAAI meeting in Phoenix. These cover real world Orladeyo outcomes, switching patterns from other prophylactic therapies, pediatric dosing experience, and long term data for injectable navenibart.
These presentations matter because they tie directly to potential future catalysts. Real world Orladeyo data and pediatric use relate to the durability of the current guidance, while the ALPHA SOLAR navenibart poster feeds into expectations for a possible second hereditary angioedema revenue stream and helps frame the risk from potential future oral competition flagged in the consensus narrative.
BioCryst Pharmaceuticals' current analyst narrative points to US$939.5 million in revenue and US$318.6 million in earnings by 2029, with earnings expected to move from a loss of US$359.7 million today to that 2029 forecast, an increase of roughly US$678 million.
Uncover why BioCryst Pharmaceuticals' fair value indicates a 169% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses on the Astria Therapeutics deal as the real catalyst rather than BioCryst Pharmaceuticals' raised guidance. The most optimistic analysts were already modelling about US$1.0b of revenue and US$723.7 million of earnings by 2029 before this ACAAI data and guidance change. That is a far more upbeat story than the consensus. If you are curious how far opinions can stretch, it may be worth comparing those bullish forecasts with more cautious scenarios and asking whether this latest news pushes your own expectations closer to either side.
Explore 3 other BioCryst Pharmaceuticals fair value estimates, including one that suggests as much as 995% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own well-researched view.
- A great starting point for your BioCryst Pharmaceuticals research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BioCryst Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate BioCryst Pharmaceuticals' overall financial health at a glance.
Looking for more investment ideas beyond BioCryst Pharmaceuticals?
If the BioCryst Pharmaceuticals story has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you quickly surface other candidates that fit very different risk and return profiles.
- For investors who care most about balance sheet strength and resilience, start with our list of solid balance sheet and fundamentals (23 results) to see which businesses might better handle tough conditions.
- If you prefer lower volatility and potential downside protection, filter the market using our 30 resilient stocks with low risk scores and see which companies align with that profile.
- Hungry for under-the-radar opportunities that the market may not be paying close attention to yet? Scan our 20 high quality undiscovered gems and build a shortlist worth deeper research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com