
We Think meerecompany (KOSDAQ:049950) Can Afford To Drive Business Growth
There's no doubt that money can be made by owning shares of unprofitable businesses. For example, although software-as-a-service business Salesforce.com lost money for years while it grew recurring revenue, if you held shares since 2005, you'd have done very well indeed. But the harsh reality is that very many loss making companies burn through all their cash and go bankrupt.
So should meerecompany (KOSDAQ:049950) shareholders be worried about its cash burn? For the purposes of this article, cash burn is the annual rate at which an unprofitable company spends cash to fund its growth; its negative free cash flow. The first step is to compare its cash burn with its cash reserves, to give us its 'cash runway'.
When Might meerecompany Run Out Of Money?
A company's cash runway is the amount of time it would take to burn through its cash reserves at its current cash burn rate. As at June 2026, meerecompany had cash of ₩29b and no debt. Looking at the last year, the company burnt through ₩6.6b. So it had a cash runway of about 4.4 years from June 2026. There's no doubt that this is a reassuringly long runway. The image below shows how its cash balance has been changing over the last few years.
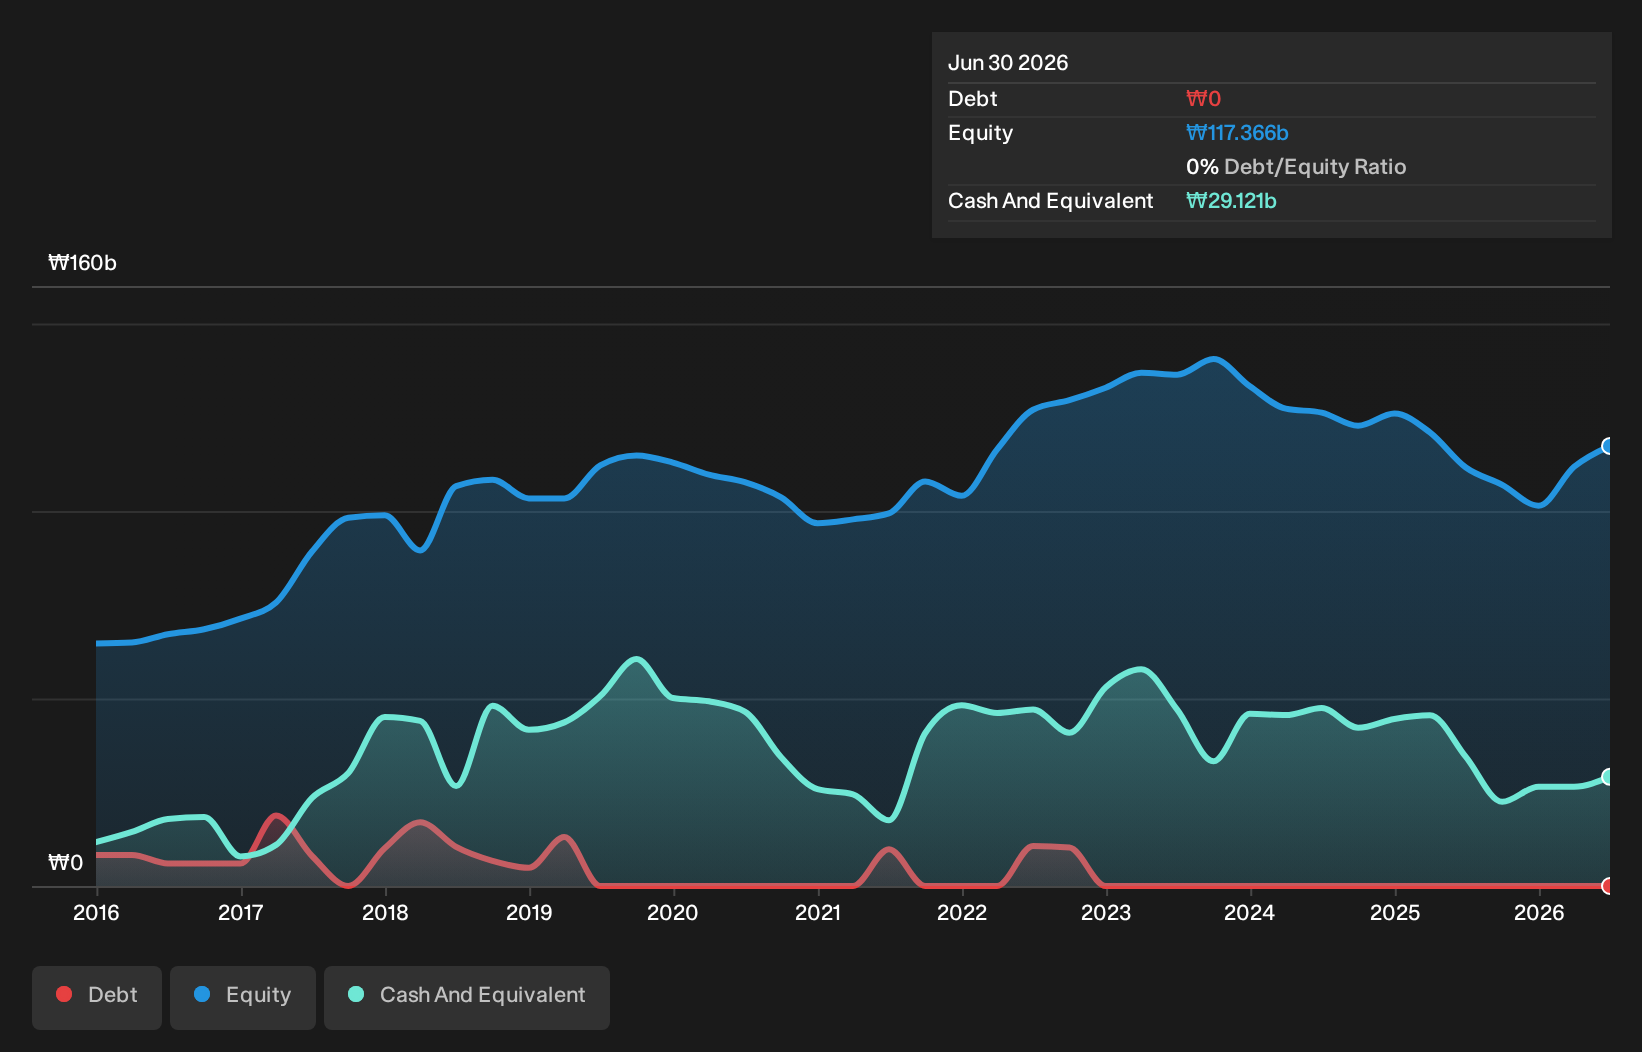
See our latest analysis for meerecompany
How Well Is meerecompany Growing?
We reckon the fact that meerecompany managed to shrink its cash burn by 22% over the last year is rather encouraging. And operating revenue was up by 5.9% too. On balance, we'd say the company is improving over time. Of course, we've only taken a quick look at the stock's growth metrics, here. This graph of historic earnings and revenue shows how meerecompany is building its business over time.
Can meerecompany Raise More Cash Easily?
While meerecompany seems to be in a decent position, we reckon it is still worth thinking about how easily it could raise more cash, if that proved desirable. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. Commonly, a business will sell new shares in itself to raise cash and drive growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
meerecompany's cash burn of ₩6.6b is about 8.2% of its ₩81b market capitalisation. Given that is a rather small percentage, it would probably be really easy for the company to fund another year's growth by issuing some new shares to investors, or even by taking out a loan.
Is meerecompany's Cash Burn A Worry?
As you can probably tell by now, we're not too worried about meerecompany's cash burn. For example, we think its cash runway suggests that the company is on a good path. Its weak point is its revenue growth, but even that wasn't too bad! Based on the factors mentioned in this article, we think its cash burn situation warrants some attention from shareholders, but we don't think they should be worried. On another note, meerecompany has 2 warning signs (and 1 which is a bit unpleasant) we think you should know about.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of interesting companies, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.