
Trade Desk (TTD) Beat In Q3, Where Does Fair Value Sit?
Trade Desk (TTD) moved back into focus after its third quarter 2026 update, where management paired softer profit figures with new fourth quarter guidance and a larger share buyback plan.
Recent trading shows how quickly sentiment around Trade Desk can swing. The stock logged a 1-day share price return of 3.63% and a 7-day share price return of 20.79%, with a 30-day share price return of 33.84%. Yet the year-to-date share price return is still down 57.59% and the 5-year total shareholder return has declined 85.13%. This points to a short-term rebound in momentum on the back of the earnings beat, new guidance and the expanded US$1b buyback rather than a completed recovery story.
Capitalize on Trade Desk’s swing in sentiment by comparing it with hand-picked advertising and media platforms in the 32 high quality undervalued stocks. These platforms pair solid balance sheets with current market pessimism.Trade Desk’s share price has sprinted ahead of its own analyst target yet still screens as roughly 21% below one cash flow estimate. Where does fair value really sit between that optimism and the recent rebound in price?
Most Popular Narrative: 45% Undervalued
Trade Desk last closed at $15.98, while the most followed narrative on Simply Wall St assigns a fair value of $29.24. This implies a wide gap between recent pricing and that estimate, according to matttttt, an investor in the Simply Wall St Community who wrote the narrative.
Recently they’ve experienced a slower rate of growth with revenue slowing and lower than expected guidance which has seen their price drop significantly. Lets see how this stacks up:
See why 34 investors see Trade Desk as 45% undervalued.
The fair value in that narrative is built from a 10% revenue growth rate, a 14.57% profit margin and a 7.11% discount rate. Those inputs sit alongside a view that Trade Desk still benefits from partnerships in streaming, AI driven tools and a predominantly US revenue base that accounts for 82% of sales.
At the same time, the narrative flags headwinds that readers need to weigh against that 45.3% discount to fair value. Competition from Amazon, Alphabet and Meta, softer recent growth and higher infrastructure costs linked to AI are all presented as reasons why growth expectations could moderate.
Readers comparing this narrative to current market data can also see that analysts collectively have a lower 1-year price target of $14.17, while Simply Wall St’s separate cash flow estimate points to a value of $20.16 and the stock trades roughly 20.7% below that figure. Those reference points sit either side of the narrative fair value and highlight how wide the valuation debate is around Trade Desk today.
Result: Fair Value of $29.24 (UNDERVALUED)
Still, the Trade Desk story can be knocked off course if competition from Amazon, Alphabet and Meta intensifies, or if AI driven infrastructure costs bite harder than expected.
Find out about the key risks to this Trade Desk narrative.
Another View on Trade Desk’s Valuation
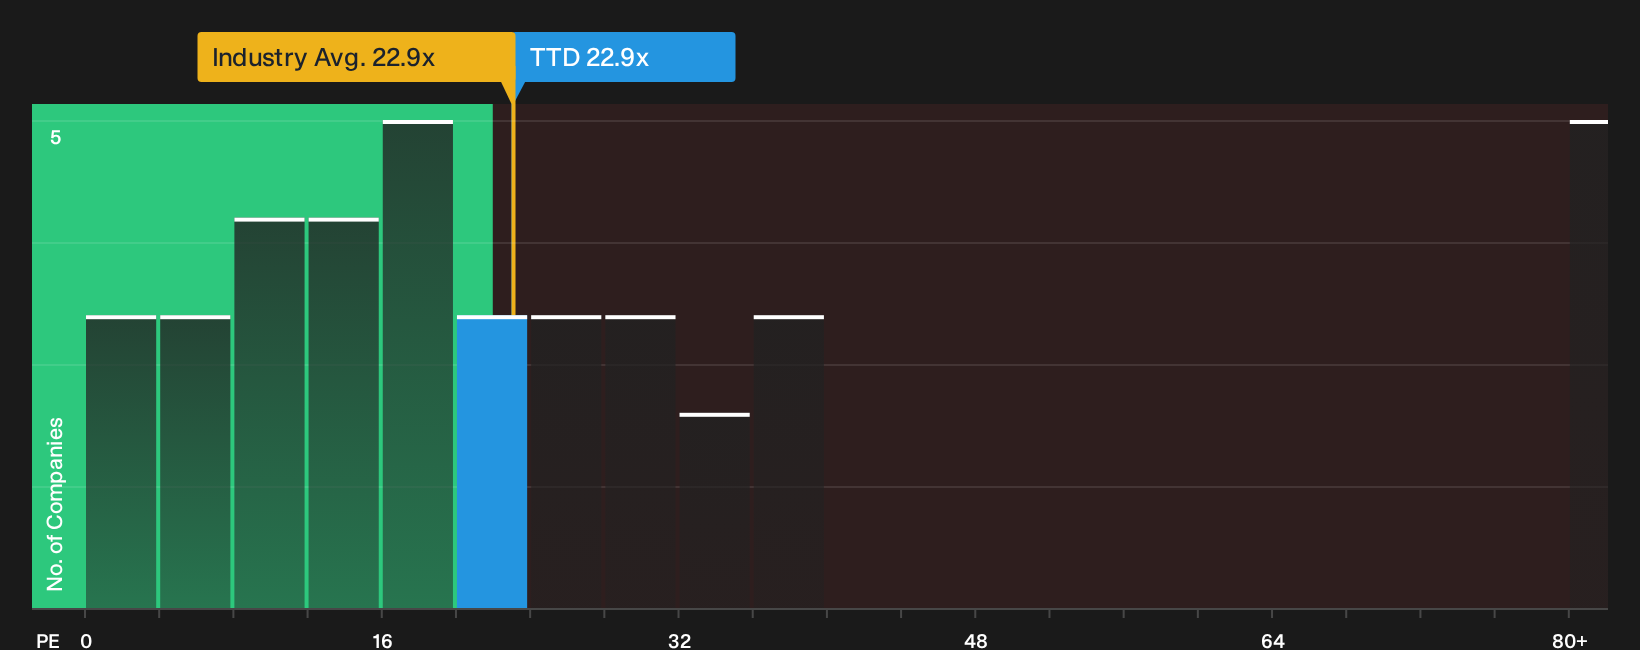
The earlier community narrative leans on revenue growth, margins and discount rates to argue Trade Desk is materially undervalued. A different lens tells a cooler story. On P/E of 22.9x, the stock trades exactly in line with the US Media average, yet above a fair ratio of 16.8x that our model suggests the market could move toward.
That mix points to a company that looks cheap versus faster growing peers with an average 44.6x P/E, while still carrying some valuation risk if sentiment weakens and the market gravitates closer to that lower fair ratio. The real question is which crowd you think will set the tone next: the peers, or the regression line.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether Trade Desk’s recent swing in sentiment lines up with your own reading of the numbers? Act quickly, review both the risks and the potential upsides, then pressure test your view against the 2 key rewards.
Looking for more investment ideas beyond Trade Desk?
If Trade Desk has sharpened your thinking, do not stop there. Broader context across other businesses can help you pressure test every assumption in your portfolio.
- Target potential mispricings by scanning companies that combine strong fundamentals with weaker sentiment using the 20 high quality undiscovered gems.
- Sharpen your focus on financial resilience by filtering for companies with sturdy balance sheets through the list of solid balance sheet and fundamentals (23 results).
- Stack your watchlist with income candidates by reviewing a curated set of high yield payers in the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com