
Bilt Partnership Could Be A Game Changer For Lowe's Stock (LOW)
- Lowe's Companies announced a new partnership with Bilt Technologies that links MyLowe's Rewards with Bilt's platform for over 8 million members, enabling point earning on eligible Lowe's purchases and access to Lowe's HomeCare+ home maintenance subscriptions.
- The collaboration plugs Lowe's products and services directly into Bilt's AI powered Neighborhood OS and broad merchant network, which could deepen loyalty engagement around ongoing home upkeep rather than one off projects.
- The focus now turns to how Lowe's tie up with Bilt's 8 million member network could influence the broader investment narrative.
Scan how Lowe's Companies' push into recurring home services compares with other retailers leaning into resilient cash flows through list of solid balance sheet and fundamentals (23 results).
Lowe's Companies Investment Narrative Recap
To own Lowe's Companies, you need to be comfortable with a home improvement chain leaning hard into Pro customers, services, and omnichannel while carrying high debt and negative shareholders equity. According to Andrei_Niculescu, an investor in the Simply Wall St Community, the story rests on integrating acquisitions like FBM and ADG and scaling the Total Home strategy. The Bilt partnership edges that thesis toward more recurring home maintenance, but the near term operating swing factor still looks tied to how Pro and services offset softer discretionary DIY demand.
The short term catalyst many holders will watch is the upcoming Q3 2026 earnings, where management has already framed conditions as pressured but still investing for growth platforms. Any surprise around comps or margins near the guided 11.6% adjusted operating level, as well as traction in Pro and online, could move sentiment. The biggest risk remains prolonged housing and DIY weakness on top of high leverage and negative equity, which would keep comps sluggish and margins sensitive if costs or integration issues flare up.
The Bilt tie in connects directly with Lowe's push into home services like HomeCare+ and the broader Total Home ambition Andrei_Niculescu described. It slots real customers into recurring maintenance, two in home visits per year and product discounts, which can keep traffic and engagement alive even when big ticket remodels are on pause. The operational test is whether Bilt's 8 million member pool actually converts into meaningful subscription volume and higher loyalty without straining service capacity.
Against the coming Q3 2026 earnings call on 18 November, the Bilt announcement sits as a supporting catalyst rather than the main event. The conference call will likely still revolve around Pro trends, integration progress on FBM and ADG, and how guidance around roughly US$92b in sales and flat comps holds up. If HomeCare+ uptake builds and digital tools already in place, such as AI material list support, mesh well with Bilt's Neighborhood OS, it would strengthen the case that Lowe's is quietly wiring in more durable, service linked cash flows on top of its existing retail base.
On Andrei_Niculescu’s numbers, Lowe's Companies reaches a fair value of US$255.00 if sales compound at roughly 12.8% a year and the business settles at a 7.3% profit margin, which together support higher earnings power driven by Pro focused growth and services.
Discover how Lowe's Companies' fair value indicates a 10% potential upside to its current price that may not last much longer.
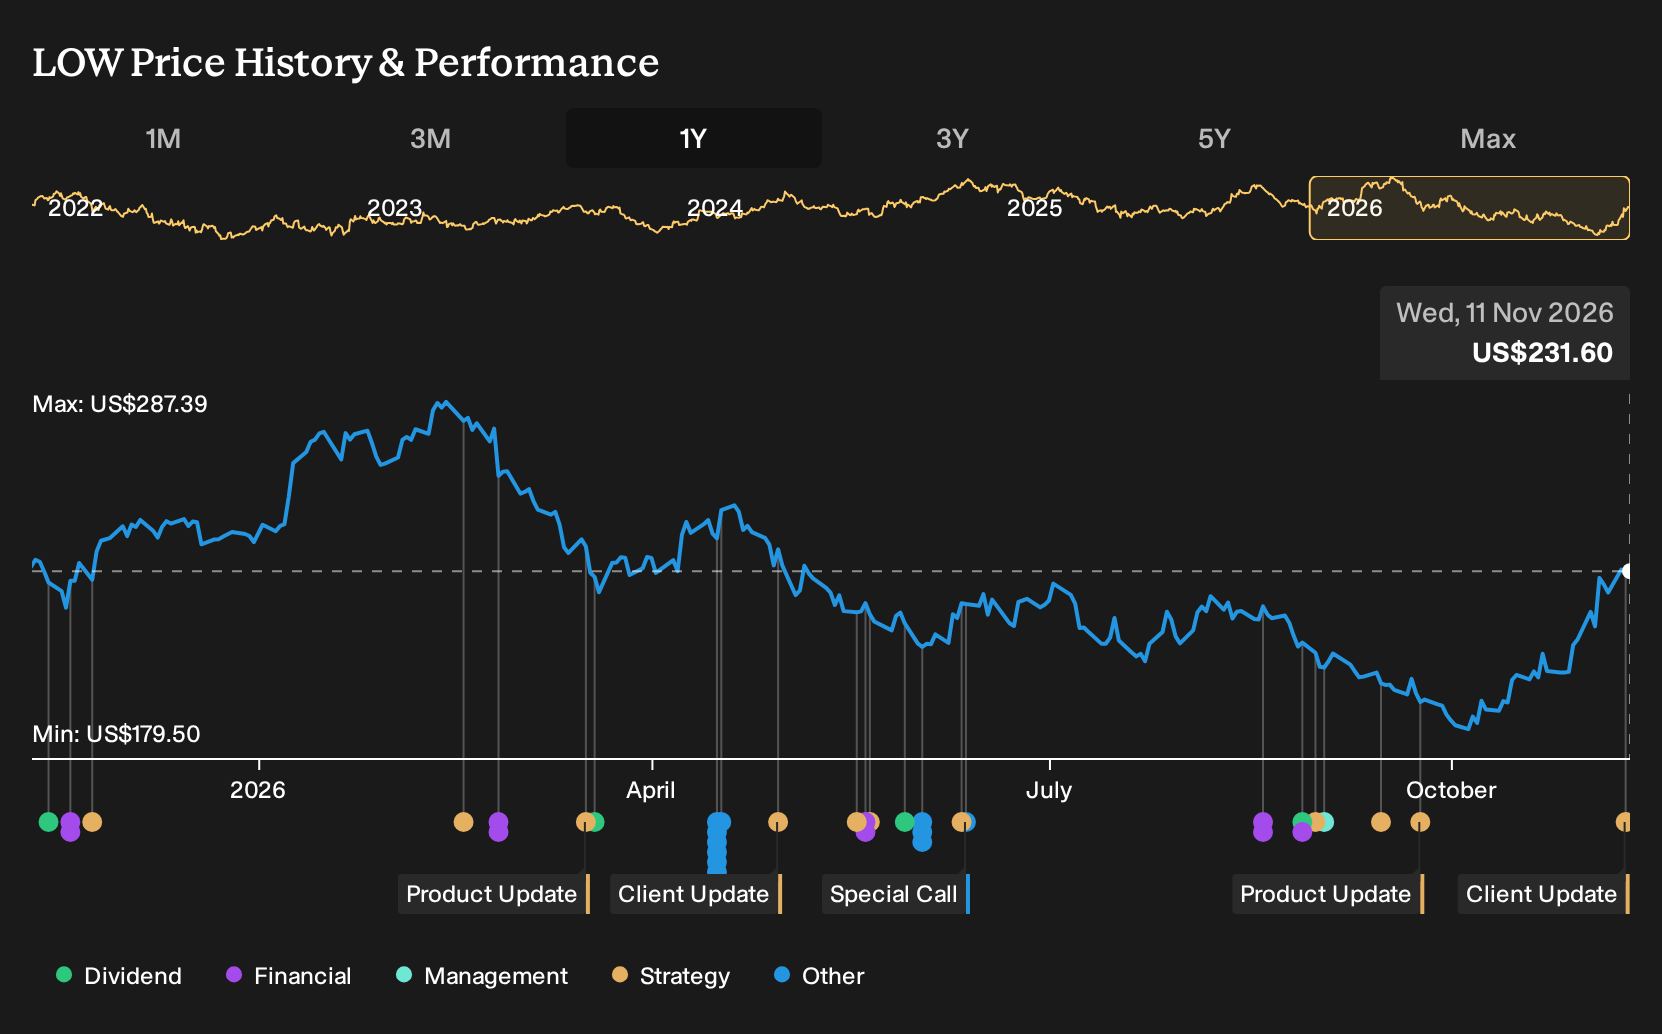
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between about US$230.90 and US$255, with only one at the very top of that band. You are seeing retail investors disagree at the margin rather than on direction. With the fresh Bilt partnership and an approaching Q3 call, it makes sense to explore these contrasting views before deciding how Lowe's Companies fits into your own expectations for earnings resilience and loyalty driven cash flows.
Explore 3 other Lowe's Companies fair value estimates, including one that suggests it could be worth just $230.90.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Lowe's Companies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lowe's Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lowe's Companies' overall financial health at a glance.
Looking for more investment ideas beyond Lowe's Companies?
Once you have a handle on Lowe's Companies and the role home improvement can play in your portfolio, it helps to scan a broader set of opportunities that match the kind of balance sheet strength, income potential, or upside profile you prefer. The Simply Wall St Screener can narrow that universe to a focused shortlist that fits your own risk tolerance and time horizon.
- If you want resilient balance sheets and solid fundamentals, start with our list of solid balance sheet and fundamentals (23 results) to see which businesses currently clear those hurdles.
- For investors hunting for mispriced quality, use the 32 high quality undervalued stocks to surface companies where fundamentals and valuation screens currently line up.
- If consistent income is your priority, filter for stocks offering stronger yields through the 6 dividend fortresses and build a watchlist around potential cash return candidates.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com