
Gas Generator Deal Could Be A Game Changer For Caterpillar (CAT)
- Caterpillar and Phoenix Service Partners reported field trial results for a large gas compression system that reduced methane emissions by up to 73% and other exhaust pollutants by up to 91% in remote Permian Basin operations without grid power.
- The ultra low emission, off grid compression setup ties directly into Caterpillar's Power & Energy backlog by addressing methane intensity concerns for gas powered data centers and pipeline customers.
- The next area of focus is how Caterpillar's investment narrative is affected by this low methane compression milestone in Power & Energy.
Scan for other industrials riding similar cleaner-energy demand by checking the hand picked 43 power grid technology and infrastructure stocks alongside Caterpillar’s off grid methane cutting compression work.
Caterpillar Investment Narrative Recap
Caterpillar shareholders need to believe the record US$78b backlog in Machinery, Power & Energy can translate into sustained equipment shipments and solid margins as capacity ramps. The methane cutting compression trial fits that thesis. It supports the analyst consensus Narrative on Simply Wall St that Power & Energy demand, including gas and data center projects, can support earnings as new capacity comes online.
The near term swing factor remains execution on large engine and turbine expansion while carrying around US$2.2b in 2026 tariff costs and higher spending on AI, autonomy and plant upgrades. The bigger risk is customers slowing AI, gas power or oil and gas buildouts, which could leave Caterpillar with underused capacity and softer segment profitability.
The Anthropic gas generator deal, worth about US$3.4b, is the clearest companion announcement to this methane reduction work. It shows Caterpillar already converting AI power interest into large orders that sit inside that US$78b backlog and tie directly to its engine and turbine footprint, where management plans to lift capacity sharply by 2030.
Taken together, the Anthropic agreement and low methane compression trial highlight both sides of the same catalyst. Power & Energy projects linked to AI data centers and gas infrastructure could support high utilization if customers follow through on long dated commitments. The operational challenge is balancing that opportunity against tariff headwinds, higher manufacturing costs and the risk of slower data center or energy spending.
Caterpillar Forecasts Behind the Low Methane Story
Caterpillar's low methane compression work plugs into a much larger set of analyst expectations around Power & Energy and the rest of the group. The current stock narrative leans heavily on forecasts that assume the backlog in engines, turbines and construction equipment can convert into higher earnings over time while cleaner gas projects, such as this methane cutting system, keep gas power acceptable for infrastructure and AI customers.
Analysts in the Simply Wall St report frame it in clear numbers. Revenue is modeled to grow at about 10.6% a year for the next three years, with profit margins rising from 15.2% today to 18.7% by around 2029 as new capacity fills and services contribution increases. Earnings are expected to move from US$11.8b today to a consensus of US$19.7b by 2029, while more cautious forecasts sit closer to US$16.1b. That gives a sense of the debate around how fully Power & Energy projects, including low methane compression, will run.
On those projections, the analyst group expects Caterpillar to support a P/E of 25.5x in 2029 compared with 24.2x today and with the wider GB Machinery industry referenced at 24.2x. That multiple implies investors would be paying more for each dollar of earnings than they are currently if the Power & Energy expansion, AI related demand and methane cutting gas projects all land close to plan. It also underlines how much weight the market is placing on long dated orders like the Anthropic gas generator agreement and associated off grid compression work to convert cleanly into future profit.
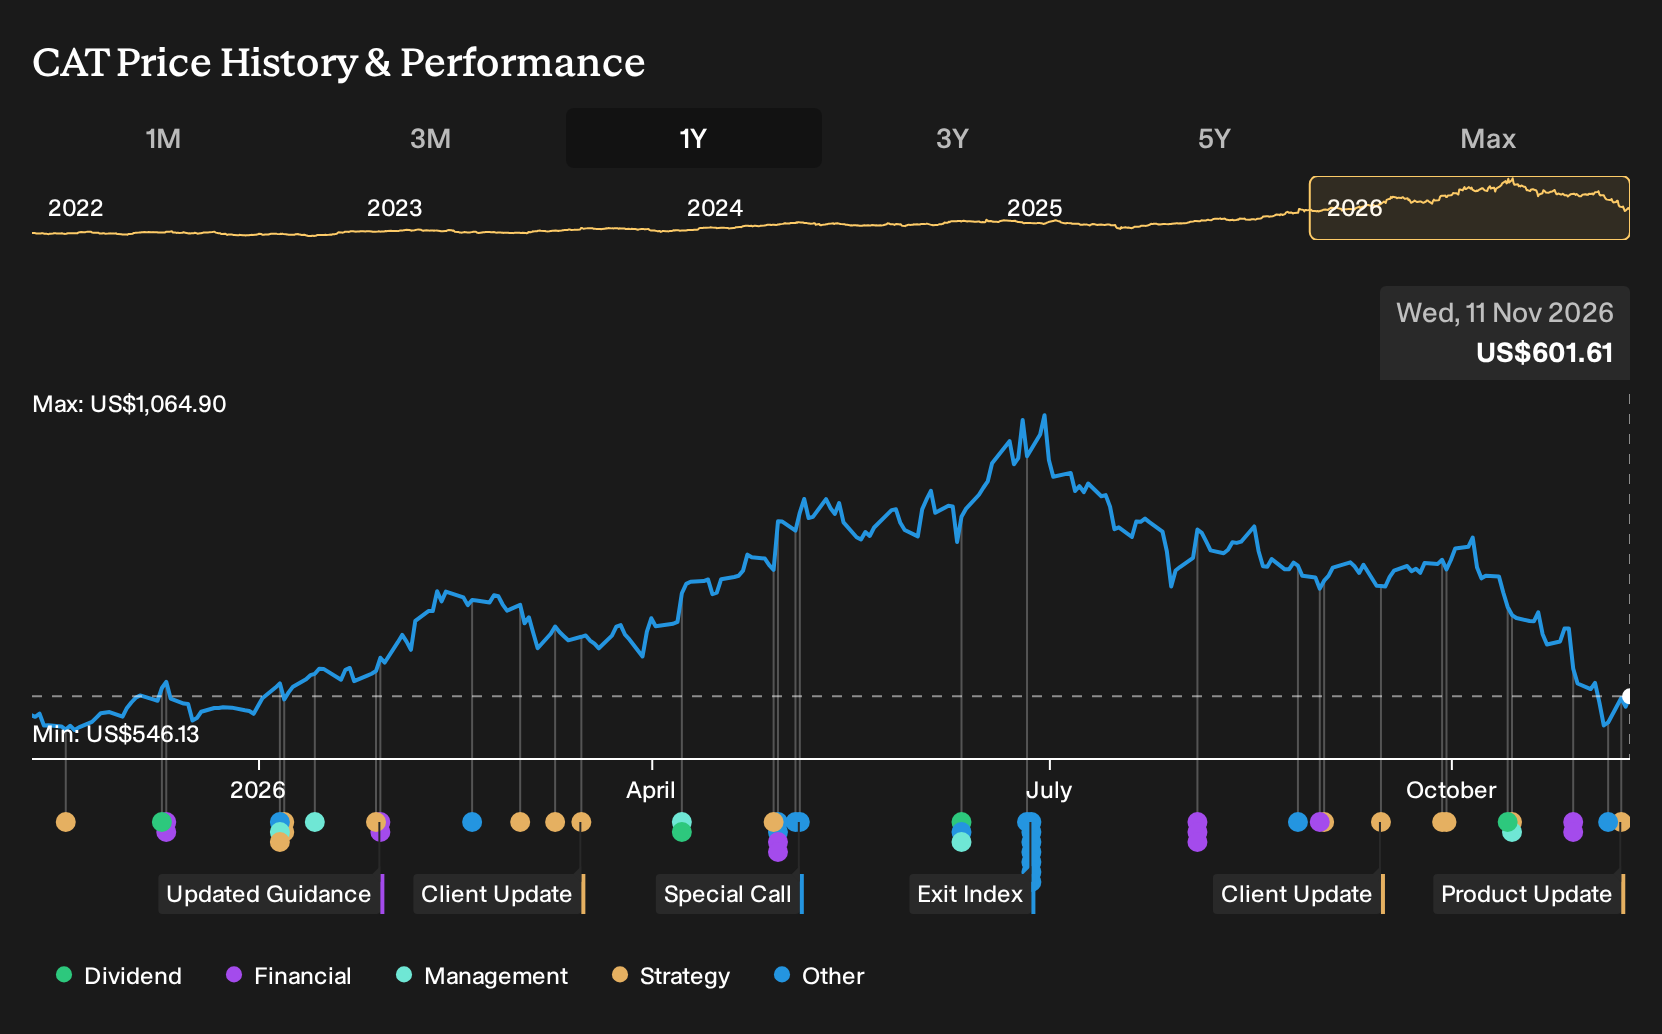
Against this backdrop, the consensus price target of US$902.34 compares with a current share price around US$622.75, with the most bullish analysts up at US$1,150 and the most cautious closer to US$575. Those figures rest on revenues reaching about US$105.2b and earnings of US$19.7b in 2029, discounted back using a rate around 8.6% to 8.62%. For you as an investor, the low methane trial is one visible proof point to weigh against those assumptions because it shows Caterpillar trying to answer methane intensity concerns that could otherwise limit gas engine, pipeline and data center orders sitting inside that forecast.
Caterpillar's narrative projects US$105.2b revenue and US$19.7b earnings by 2029. This setup assumes revenue growth of 10.6% per year and an earnings increase of about US$7.9b from current earnings of US$11.8b.
Uncover why Caterpillar's fair value indicates a 50% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view puts the big risk not on tariffs, but on future pricing power in data center and gas engines. The most optimistic analysts were already baking in about US$115.5b of revenue and US$21.5b of earnings by 2029 before this Caterpillar methane trial, so they may revisit those assumptions if cleaner compression reshapes contract terms and service potential. You should treat that as an invitation to compare several narratives instead of relying on a single forecast line.
Explore 7 other Caterpillar fair value estimates, including one that suggests as much as 62% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Caterpillar research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Caterpillar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Caterpillar's overall financial health at a glance.
Looking for more investment ideas beyond Caterpillar?
If Caterpillar's low methane compression work has sharpened your interest in cleaner energy and infrastructure themes, you can use that curiosity as a springboard to scan the wider market with the Simply Wall St Screener.
- If you want to focus on potential mispricing, you can start with companies that combine quality fundamentals with room for a re rating through the 32 high quality undervalued stocks.
- If capital preservation and steadier profiles matter most to you, you can narrow your search to businesses flagged for stronger resilience using the 30 resilient stocks with low risk scores.
- If you care most about balance sheet strength and durable cash generation, you can concentrate on companies with healthier finances through the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com