
Earnings Guidance Raised Might Change The Case For Investing In Ameren (AEE)
- Ameren Corporation reported third quarter 2026 revenue of US$2,882 million and net income of US$676 million, alongside raised full year 2026 earnings guidance and new 2027 earnings targets.
- The utility paired higher per share earnings for the quarter and year to date with updated multi year guidance that signals how management currently views demand, costs and regulatory conditions across its regulated businesses.
- The impact of Ameren’s higher 2026 earnings guidance on the company’s investment narrative and long term setup remains to be seen.
Scan how Ameren frames its earnings guidance, then broaden your watchlist with a curated 43 power grid technology and infrastructure stocks that echoes similar regulated infrastructure themes.
Ameren Investment Narrative Recap
To own Ameren, you need to be comfortable with a regulated utility that is leaning into very large capital spending, especially around data center load and grid upgrades, while relying on constructive regulation in Missouri and Illinois. The analyst consensus Narrative on Simply Wall St highlights that execution on more than US$71b of planned projects and timely approvals are central to the story.
The raised 2026 guidance and new 2027 earnings range matter most if you see the near term catalyst as proof that big capex and new large load customers can flow through to per share earnings. The biggest near term risk still appears tied to regulatory decisions and any slowdown, delay or downsizing in those large data center projects.
The clearest announcement for this setup is Ameren’s move to lift 2026 earnings guidance to US$5.35 to US$5.55 per diluted share and to outline a 2027 range of US$5.70 to US$5.90. That is directly connected to how management is sizing the payoff from its investment pipeline of more than US$71b and the ramp in large load customers.
For you as a shareholder, the raised guidance and fresh 2027 range frame the upcoming EEI Financial Conference and future rate case outcomes as key moments to check on execution. They also sit alongside the ongoing risks flagged around debt coverage by operating cash flow and the need to issue equity while keeping credit metrics in line.
Ameren's current analyst narrative points to revenues of US$10.8b and earnings of US$2.0b by 2029, based on assumed yearly top line growth of 8.6% and an earnings increase of US$400m from US$1.6b today.
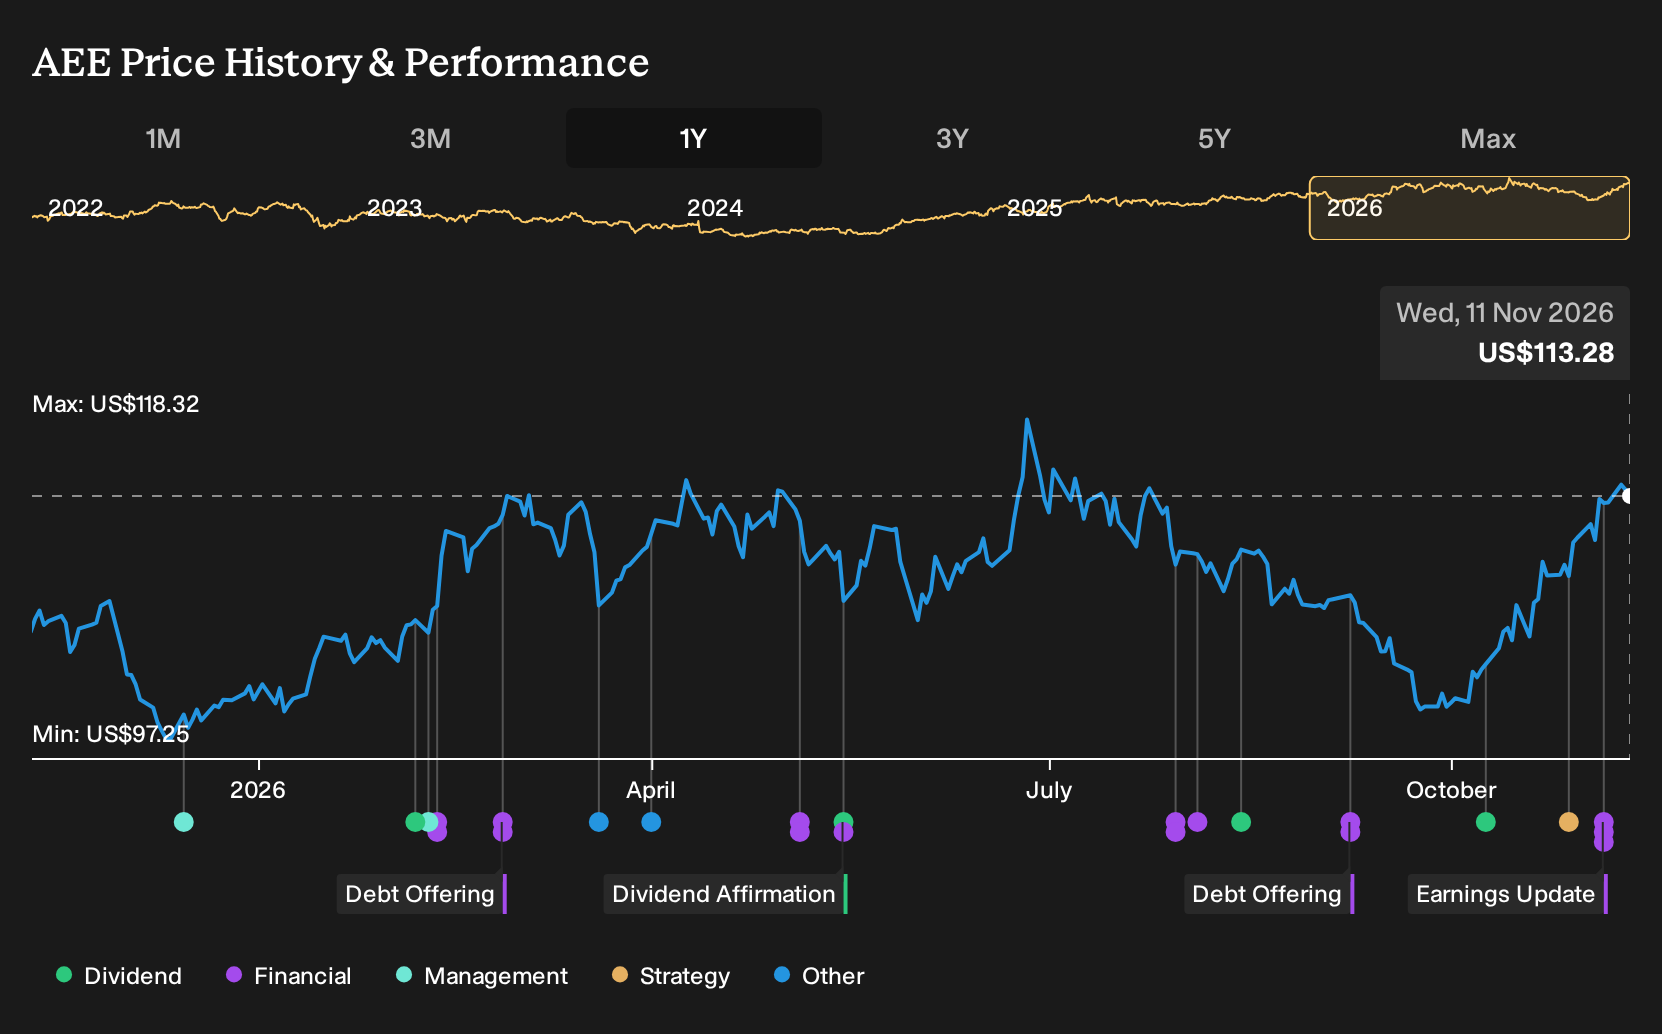
Discover how Ameren's fair value indicates a 3% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community bracket Ameren between roughly US$95 and US$117 per share, showing how far private estimates can stretch. Those opinions were formed before the latest guidance upgrade and the upcoming EEI Financial Conference, so it is important to factor in that fresh information and compare several contrasting viewpoints before leaning on any single number.
Explore another Ameren fair value estimate, including one that suggests it could be worth as much as $116.81.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ameren research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ameren. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ameren's overall financial health at a glance.
Looking for more investment ideas beyond Ameren?
Once you have weighed Ameren against your own risk tolerance and income needs, it can be useful to line it up against other opportunities using the Simply Wall St Screener. That way you see where this regulated utility fits on your broader shortlist rather than treating it in isolation.
- If capital preservation is high on your list, compare Ameren with a 30 resilient stocks with low risk scores that screens for resilience and lower risk scores.
- For income focused investors, set Ameren alongside a 6 dividend fortresses that surfaces companies offering yields of 5% or more.
- If you prefer to hunt for quality at a reasonable price, weigh Ameren against a 20 high quality undiscovered gems that highlights under followed stocks with strong fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com