
How Investors May Respond To Transcat (TRNS) Strong Quarterly Earnings
- Transcat reported second quarter fiscal 2027 revenue of US$97.09 million and net income of US$2.41 million, with leadership highlighting calibration services, operational execution, and recent M&A such as Southeastern Biomedical Associates as key contributors.
- Management described service activities as a long runway opportunity, citing a healthy acquisition pipeline, a focus on accretive deals with synergies, and an emphasis on expanding higher margin rental offerings.
- The focus now is on how Transcat's calibration-driven quarter and ongoing M&A activity might influence the current investment narrative.
Scan beyond Transcat and explore other service-driven operators with similar momentum in our hand-picked 20 high quality undiscovered gems list.
Transcat Investment Narrative Recap
To be comfortable owning Transcat, you need to believe that its calibration services, rentals, and M&A program can convert a large regulated customer base into steadier earnings over time. The latest quarter showed strong top line and service performance, but net income for the first half of fiscal 2027 still sat below the prior year, so margin progress remains a key watchpoint.
The analyst consensus Narrative on Simply Wall St leans on service productivity gains, higher margin rentals, and continued deal flow as the main near term catalyst. The biggest risk is still integration and margin pressure from acquisition led expansion, especially with a relatively new management team and recent one off items in the financials.
The second quarter fiscal 2027 earnings release is the most useful reference point against this story. Revenue for the quarter was US$97.09 million with net income of US$2.41 million, while the six month figures showed higher sales but lower profit than the prior period, which keeps the margin debate very alive for Transcat.
Management commentary linked that performance to calibration services, operational execution, and recent deals such as Southeastern Biomedical Associates, which ties directly into the M&A heavy catalyst path analysts are watching. For you as a shareholder, the question is whether that deal activity and rental expansion can offset integration risk, gross margin pressure, and a valuation already flagged as expensive on several P/S metrics.
Transcat's current analyst narrative points to forecast revenue of US$427.5 million and earnings of US$16.9 million by 2029. These projections are built on an assumed 7.1% yearly revenue growth rate and an increase in projected earnings of US$13.5 million from US$3.4 million today.
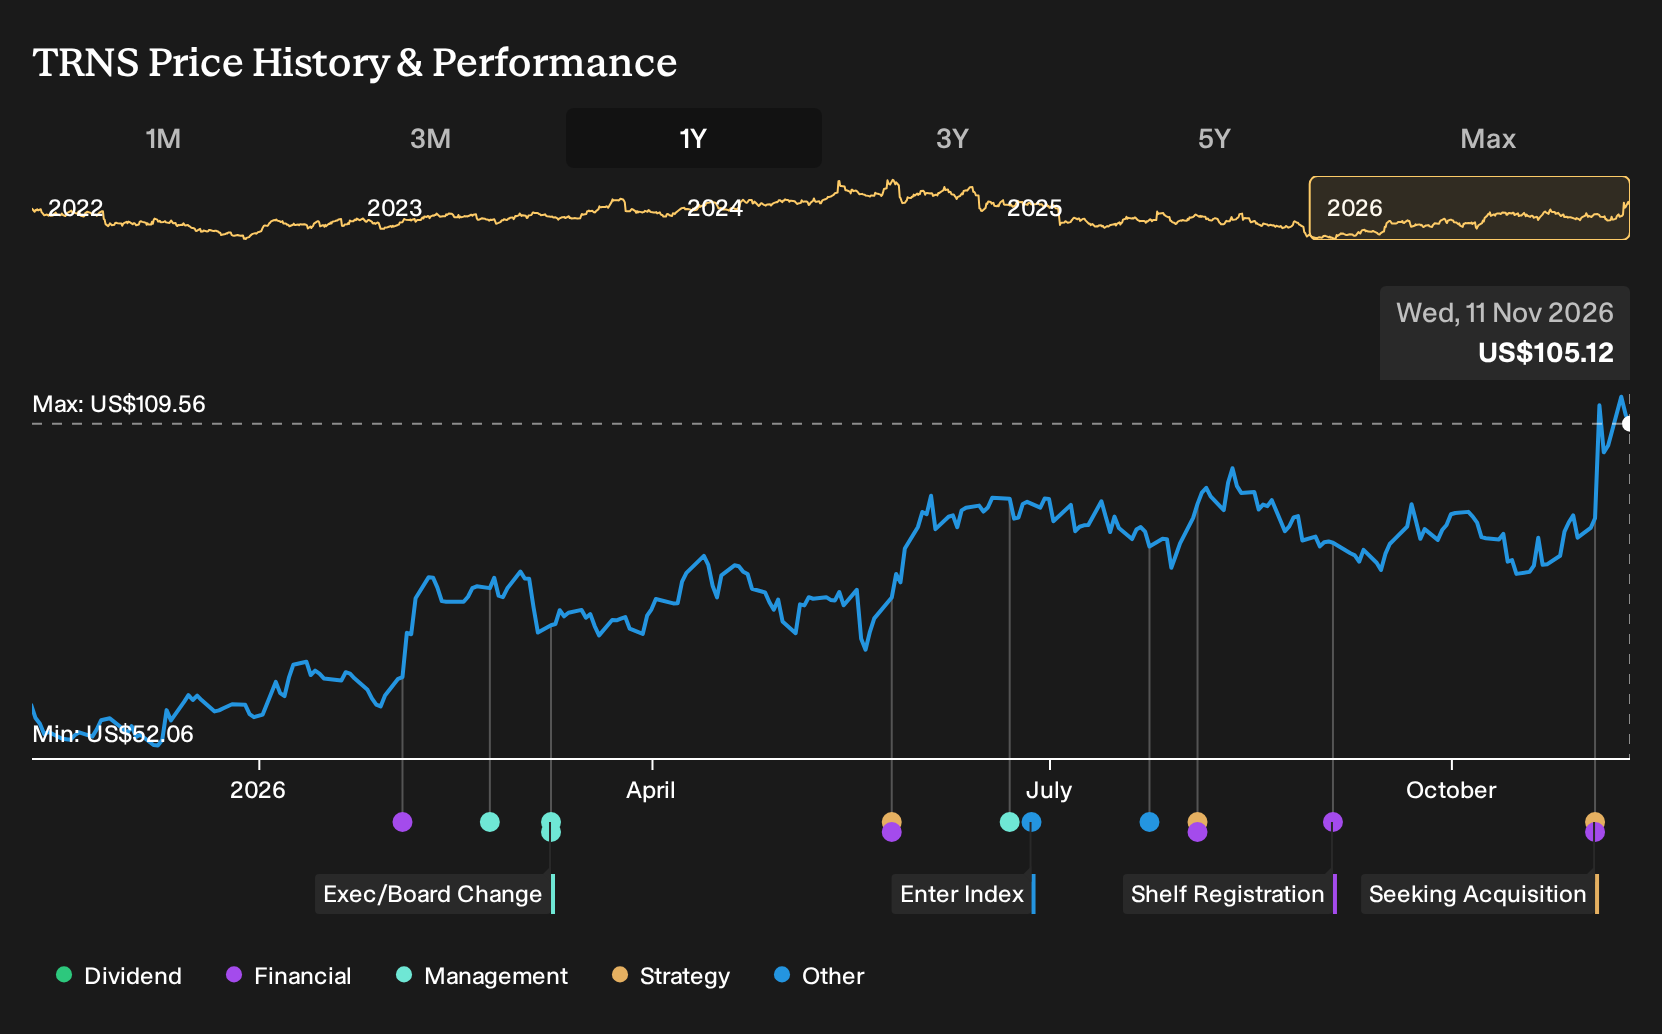
Discover why Transcat's fair value appears to be broadly consistent with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts see Transcat’s M&A push as the real swing factor. Before this quarter’s update, the bullish camp was already modeling revenue of about US$433.6 million and earnings near US$17.9 million by 2029. You can now ask whether this fresh acquisition commentary nudges those upbeat views even higher or forces a rethink.
Explore 2 other Transcat fair value estimates, including one that suggests it could be worth as much as $104.33.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Transcat research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Transcat. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Transcat's overall financial health at a glance.
Looking For More Ideas Beyond Transcat?
If the Transcat story has sharpened your thinking around services, margins, and acquisition pipelines, it can help to put that in context by scanning a wider set of potential opportunities. The Simply Wall St Screener lets you apply the same kind of filters across the market so you can focus on businesses that fit your risk, income, and valuation preferences.
- For investors who care most about quality at a reasonable entry point, start with a curated set of companies trading on appealing fundamentals through the 32 high quality undervalued stocks.
- If capital preservation and balance sheet strength matter to you, narrow the field to businesses with stronger financial footing via the list of solid balance sheet and fundamentals (23 results).
- Income focused investors can quickly focus on higher yielding opportunities by scanning the 6 dividend fortresses that clear a 5% threshold and aim for more dependable payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com