
The Bet Behind Gerdau's Rally
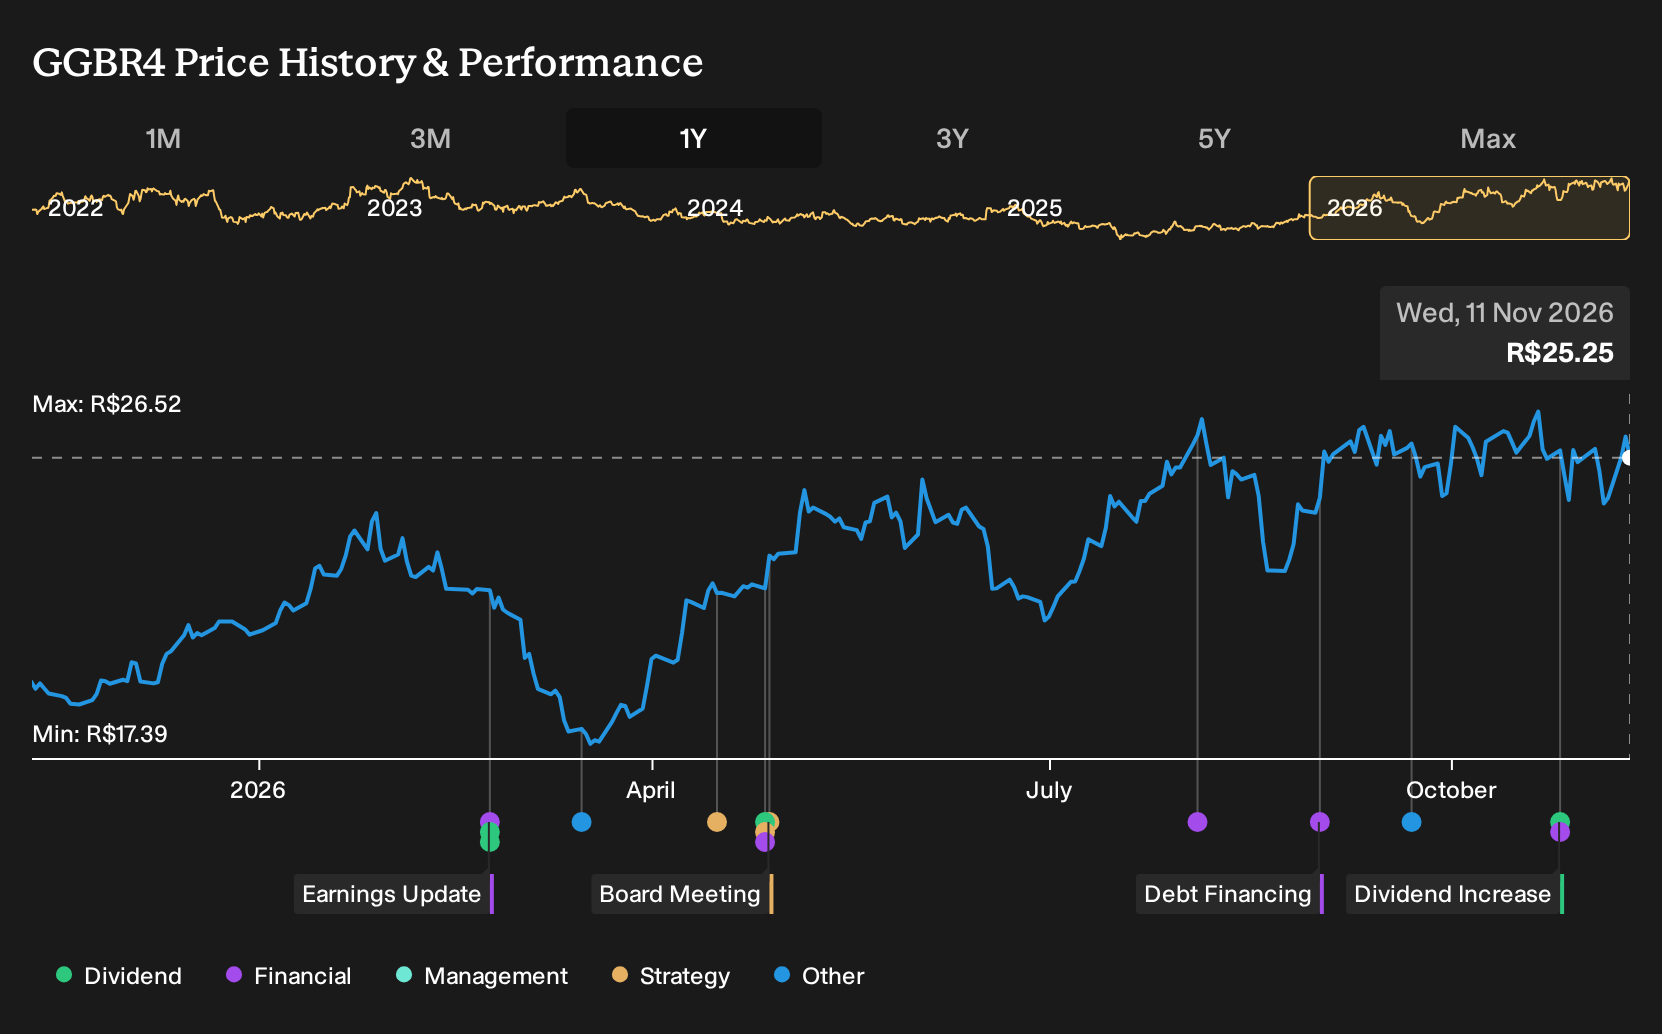
Gerdau just delivered a result many investors might not have expected from a cyclical steel producer facing trade and policy headwinds in Brazil. Investors who held Gerdau over the past year are up 37.5%, including dividends. If you had been weighing the bullish call that North American demand could lift margins against the bearish worry that imports and protectionism would cap long term returns, what exactly in the record back in November 2025 made this payoff look plausible or too risky?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The move put Gerdau in the middle of this trade. Scan 16 top copper producer stocks for other companies exposed to it.
The Two Stories Investors Had To Weigh On Gerdau
The shares cost R$19.01 at the start of the period, and Gerdau sat between two sharply different but credible stories about where value might sit.
On the bullish side, one narrative argued that accelerating North American demand could justify a fair value of R$22.26. That view leaned on assumptions such as revenue growing 6.2% a year and margins reaching 7.2%, helped by projects such as Miguel Burnier and investment in value-added steel.
The bearish narrative pointed to global trade frictions and imports, especially into Brazil, and set fair value at R$17. It relied on more cautious assumptions, including 3.0% annual revenue growth and margins rising only to 6.0%, with persistent overcapacity and protectionism seen as key threats.
What The Results Changed For The Gerdau Thesis
The key development was Gerdau’s Q3 2026 report, which showed revenue at R$18,690.5m and net income at R$1,554.2m versus R$17,983.1m and R$1,079.4m a year earlier. Net margin moved from 6.0% to 8.3%. That outcome supported the optimistic case that higher profitability was possible, although it did not erase the longer term trade and policy concerns in Brazil.
The lesson is simple. When a bullish story rests on better margins, it is important to test it against reported net margin, segment contribution, and EBITDA, not just headline growth or P/E expectations.
What Gerdau’s 37% Run Already Prices In
Today Gerdau trades at R$25.25, with this cautious Narrative’s Fair Value sitting below the current price. The bearish analyst Narrative on Simply Wall St frames the stock as pricing in robust North American EBITDA, disciplined spending and steady cash returns after a 37.5% gain over the past year.
On that view, anyone paying today’s price is effectively assuming North America carries group profits while Brazilian weakness stays contained. The question is how that assumption holds up if project delays, softer U.S. pricing or limited room to add leverage play out as the Narrative fears.
"The main thing that has to go right is that North America continues to carry roughly three quarters of EBITDA while projects like Miguel Burnier, the Pindamonhangaba scrap center and the Midlothian expansion together add around BRL 1.4 to 1.5b of annual EBITDA after delays, without further deterioration in Brazil."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Which Company Could Surprise You Next?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 33% below our estimate - leverages higher direct-to-consumer trade-in volumes and AI recycling logistics to support profitability.
- Company 2 - 34% below our estimate - connects AI data center expansion with subscription and usage pricing across existing customers.
- Company 3 - 29% below our estimate - tightens turbine pricing while shifting earnings mix toward higher margin service contracts.
That is three of the list. See every one of the 194 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com