
How ASIC Fee Lawsuit At CBA Has Changed Its Investment Story
- ASIC has launched civil court action against Commonwealth Bank of Australia over allegedly overcharging tens of thousands of CommBiz business users and failing to fully disclose certain transfer fees, with the regulator seeking declarations, penalties and other orders for what it views as long running misconduct.
- The case highlights how fee transparency and disclosure on core transaction products can directly affect compliance spend, remediation risk and longer term trust in Commonwealth Bank of Australia’s business banking franchise.
- We will now look at how this ASIC action over alleged undisclosed CommBiz fees could reshape Commonwealth Bank of Australia's investment narrative.
Commonwealth Bank of Australia Investment Narrative Recap
To own Commonwealth Bank of Australia, you need to be comfortable with a large retail and business lender that leans on technology, a strong deposit base and recurring dividends in a tightly regulated system. The immediate catalyst is how effectively Commonwealth Bank of Australia can keep net interest income and costs steady while competition in digital deposits and payments pressures fees.
The ASIC case over alleged CommBiz overcharging mainly sharpens focus on compliance risk rather than the core earnings engine. The bigger near term swing factor is whether heavy technology and AI spend and higher wage commitments can be offset by productivity gains. The key risk is that rising compliance, staff and tech bills outpace revenue growth.
The ASIC action makes earlier commentary on Commonwealth Bank of Australia’s conduct and compliance track record feel more urgent. The analyst consensus Narrative on Simply Wall St already highlighted regulatory and ESG scrutiny, including New Zealand issues, deforestation concerns and a Senate inquiry into mortgage offset errors, as a meaningful drag through remediation costs and margin pressure.
That broader pattern now intersects directly with the CommBiz allegations. For you as a shareholder, the catalyst to watch is whether management can contain new remediation and legal costs inside existing technology and compliance budgets while still delivering on its A$2.4b a year tech investment plan and dividend ambitions, without eroding return on equity further.
What The CommBiz Case Means For The Numbers
On the current analyst view, Commonwealth Bank of Australia is still framed as a large, profitable lender with moderate top line expansion and only a slight squeeze on profitability, not a broken earnings story. That is important context for the ASIC CommBiz action, because it means most of the existing forecasts already assume higher ongoing compliance and technology spend even without quantifying any new penalties or remediation linked to this case.
The Simply Wall St consensus pulls these threads together into a fairly specific earnings path. Analysts expect Commonwealth Bank of Australia to lift earnings from A$10.9b today to A$11.9b by around 2029, which is roughly a A$1.0b increase over that period. Revenue is projected to rise to about A$33.4b on the back of 4.4% yearly growth and a modest reduction in profit margins from 37.2% to 35.6%.
This forecast profile matters when you think about the ASIC allegations over CommBiz fees. Rising compliance and legal bills related to fee disclosure and remediation would land on top of a cost base that is already expected to be heavy because of technology and AI programs, cyber spending and pre agreed wage increases. Any extra hit therefore risks compressing those forecast margins faster than the 35.6% level analysts currently embed.
Valuation assumptions lean on that same earnings path. The analyst models referenced in the Simply Wall St report imply that by 2029, with A$33.4b in revenue and A$11.9b in profit, Commonwealth Bank of Australia would trade on a P/E of 22.2x versus 25.1x today. This still sits above the current AU banks sector P/E of 13.7x and suggests the market is expected to keep paying a premium for its balance sheet strength and franchise despite ongoing regulatory scrutiny.
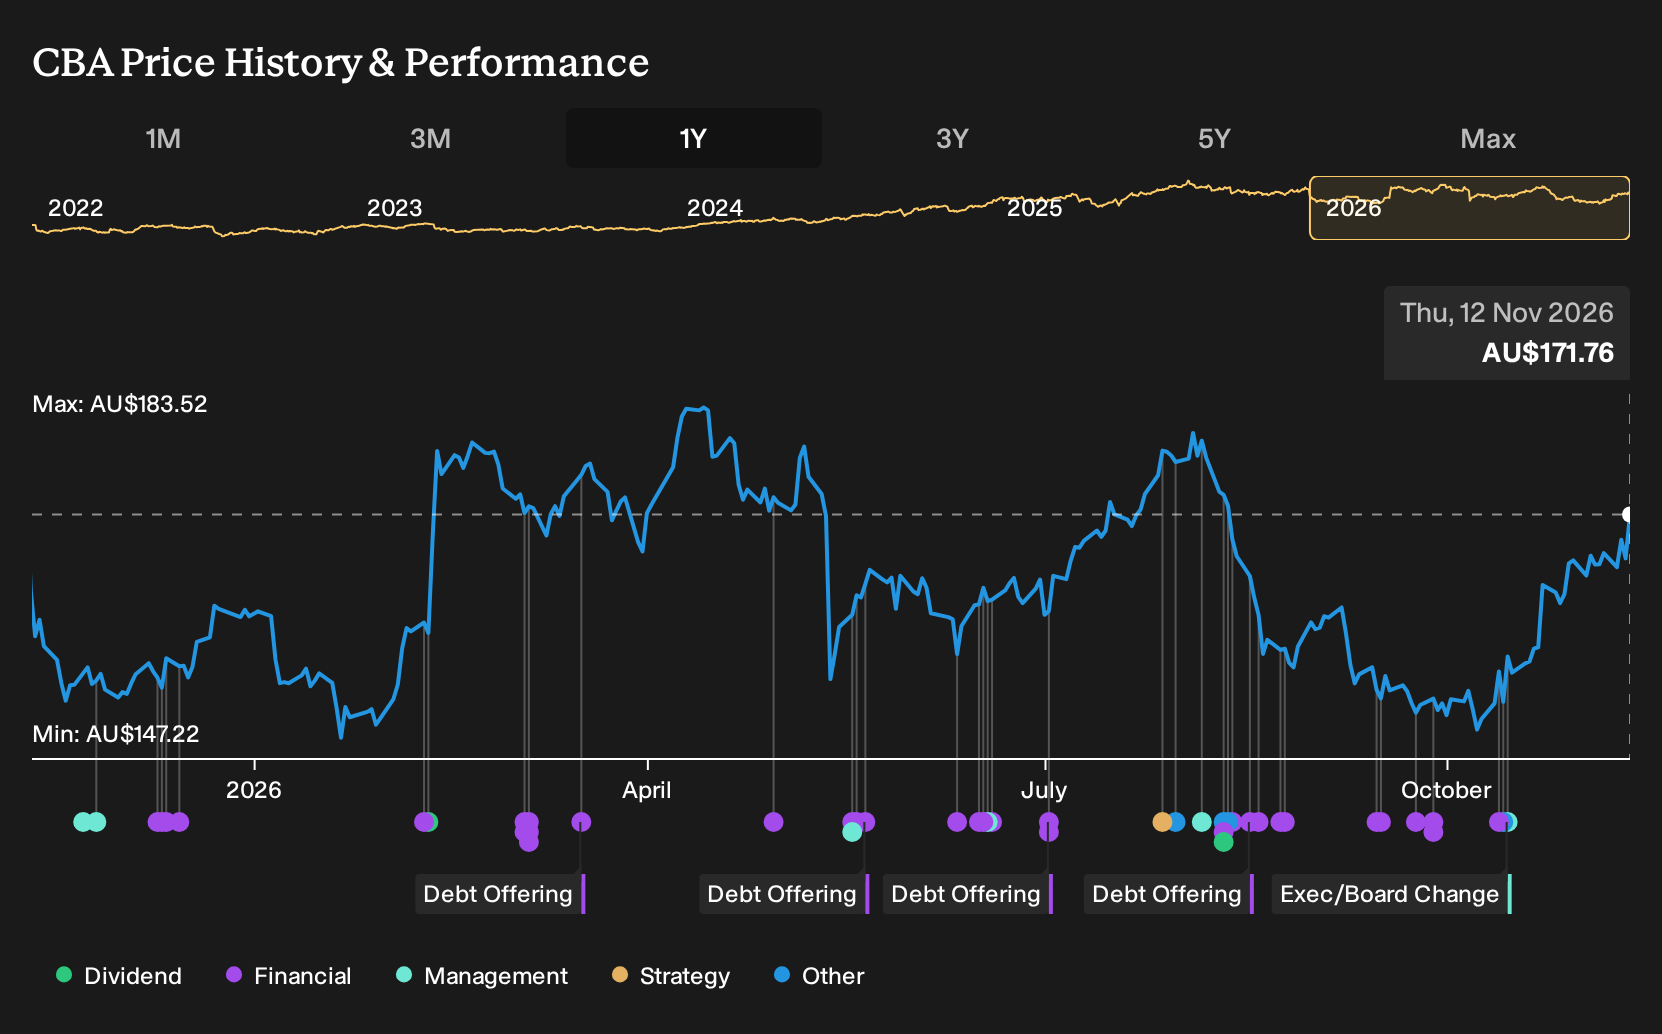
Overlay the ASIC case on that picture and you get a clear tension. The consensus price target of A$125.55 sits 30.6% below the recent A$164.0 share price, even though analysts factor in higher earnings and a larger revenue base by 2029. This indicates that the central question is not whether Commonwealth Bank of Australia can stay profitable but whether that profitability is rich enough to justify today's valuation once compliance, legal and ESG risks like the CommBiz action are fully priced in.
Commonwealth Bank of Australia's narrative projects A$33.4b revenue and A$11.9b earnings by 2029. This implies 4.4% yearly revenue growth and about A$1.0b earnings increase from A$10.9b today.
Uncover how Commonwealth Bank of Australia's fair value indicates a 27% potential downside to its current price, suggesting that this premium may not hold.
Exploring Other Perspectives
One optimistic angle on Commonwealth Bank of Australia leans on the bullish AI and productivity story instead of compliance risk. The most upbeat analysts were modelling revenue of A$34.8b and earnings of A$12.3b by 2029 before this ASIC case surfaced. You can treat those as one possible path that might be revised as the CommBiz allegations play out and compare them with more cautious views.
Explore 5 other Commonwealth Bank of Australia fair value estimates, including one that suggests it could be worth as much as A$144.99.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Commonwealth Bank of Australia research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Commonwealth Bank of Australia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Commonwealth Bank of Australia's overall financial health at a glance.
Looking for more investment ideas beyond Commonwealth Bank of Australia?
If this ASIC action has you reassessing how much single stock risk you want to carry with Commonwealth Bank of Australia, it can help to line it up against other businesses with different balance sheet strength, payout profiles and valuation setups using the Simply Wall St Screener.
- If capital preservation and a smoother ride matter most to you, compare Commonwealth Bank of Australia with 6 resilient stocks with low risk scores that aim to pair steadier fundamentals with lower measured risk.
- If income is your priority, size up its dividend profile against 5 dividend fortresses that combine higher yields with robust cash generation.
- If you are hunting for mispriced opportunities, set Commonwealth Bank of Australia beside 14 high quality undiscovered gems that couple solid quality scores with less crowded ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com