
Top 3 Undervalued Stocks To Watch In November 2026
Central banks keep talking tougher on inflation, and the latest comments from key Federal Reserve officials have markets bracing for higher interest rates and pricier borrowing. When money costs more, investors often rethink what they are willing to pay for each dollar of future cash. That is where companies generating solid cash flow yet priced below estimated fair value can appeal. This article highlights three such stocks from our cash flow value screener.
The three stocks featured below are only a small slice of the opportunity, as the same screen surfaced 431 more companies with cash flow stories that look just as compelling but are not covered here. To see the full list and quickly identify ideas that fit your own return and risk preferences, head straight to the Undervalued Stocks Based On Cash Flows screener.
MINEBEA MITSUMI (TSE:6479)
Overview: Minebea Mitsumi manufactures precision bearings, motors, sensors, access hardware and electronic components that feed into automotive, industrial, aerospace and home security equipment worldwide.
Operations: Minebea Mitsumi generates ¥510.3b from Motor, Lighting & Sensing, ¥624.0b from Semiconductors & Electronics and ¥320.0b from Precision Technologies, with smaller contributions from Access Solutions and Other segments.
Market Cap: ¥1.19 trillion
Minebea Mitsumi matters for this cash-flow-focused screen because its precision motors and sensors generate recurring cash that the analyst consensus Narrative on Simply Wall St believes the market is not fully recognising, particularly where those components plug directly into fast-growing computing and automotive end markets.
"MinebeaMitsumi is expanding monthly ball bearing capacity from roughly 404 million units to over 460 million by late 2028 to serve AI server and data center demand, which could lift group revenue and support operating margin leverage as higher value bearings scale."
What happens to Minebea Mitsumi’s cash-flow story if one key pressure on costs and pricing moves sharply in the wrong direction?
If that risk is front of mind, read the full narrative for MINEBEA MITSUMI to see how Minebea Mitsumi’s cash flows could still accelerate or stall from here.

NSK (TSE:6471)
Overview: NSK manufactures bearings, automotive components, precision machine parts, motors and digital condition monitoring services that support recurring industrial and automotive cash flows.
Market Cap: ¥495.4 billion
For the Undervalued Stocks Based On Cash Flows theme, NSK matters because its bearings, precision components and maintenance services generate long-life replacement cash flows that the bullish analyst Narrative on Simply Wall St sees as underappreciated by the market.
"Faster than planned progress on operational improvements, with around ¥10b of the targeted ¥15b already realized over FY2024 to FY2025, gives NSK extra room to extend its structural reform program beyond the current plan and potentially convert recurring cost savings into higher operating margins than currently assumed in many models."
What happens to NSK’s valuation gap if one less visible competitive pressure stops management from turning those richer margins into durable free cash flow?
If that quiet threat worries you, read the full narrative for NSK to see how NSK’s margin reform story could decouple cash generation from that risk and potentially lead to a re-rating of expectations.
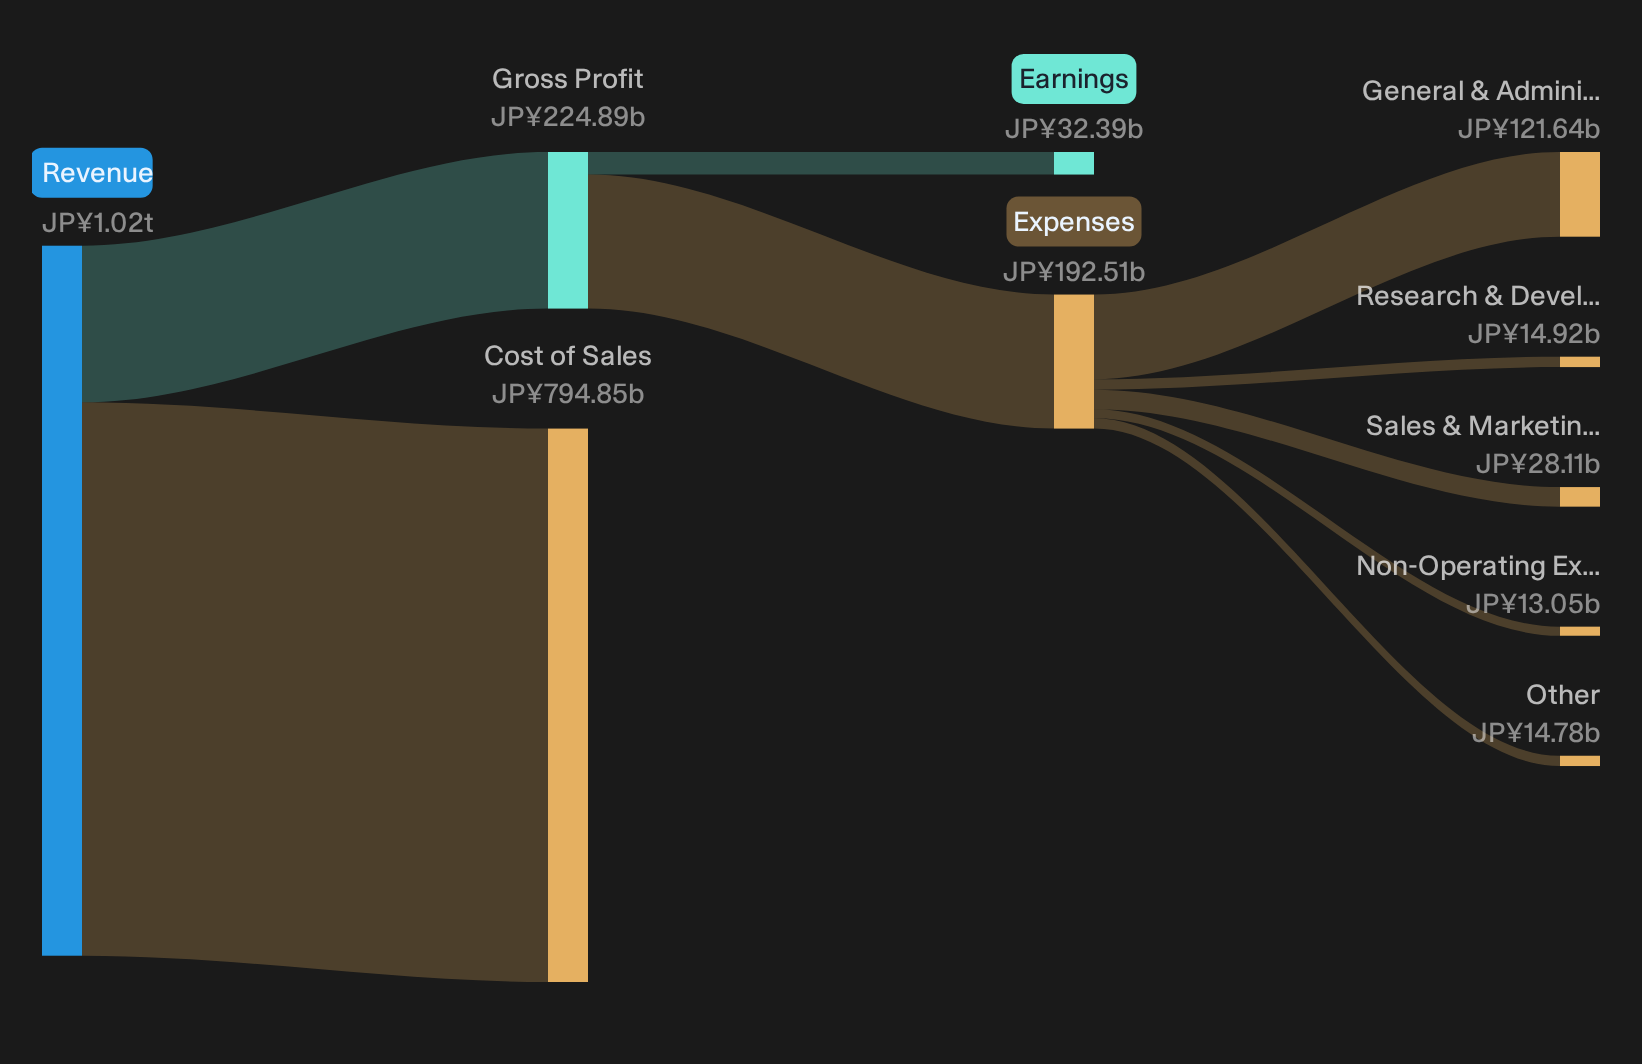
Oracle (ORCL)
Overview: Oracle delivers cloud applications, database technology, and infrastructure services. Oracle Cloud and NetSuite generate recurring subscription cash flows.
Operations: Oracle earns most of its revenue from Cloud and software at US$62.8b, with US$5.8b from Services and US$3.2b from Hardware.
Market Cap: US$367.8b
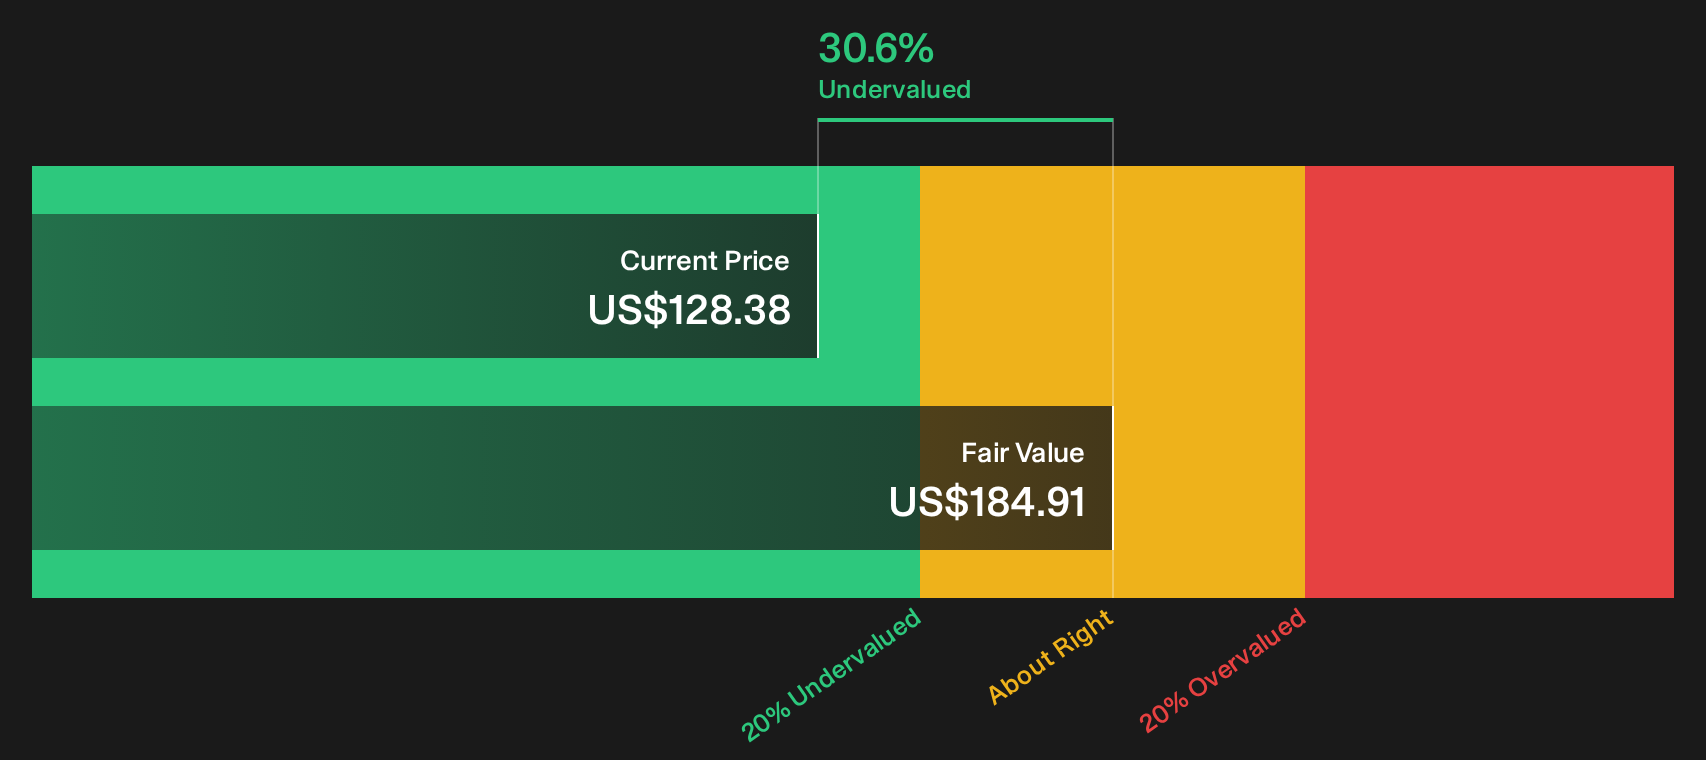
Oracle matters for this cash-flow-focused screen because its cloud software and infrastructure subscriptions convert long-term customer contracts into recurring cash that SWS’s DCF model sees as undervalued, according to TickerTickle, a Simply Wall St Community investor who wrote the Narrative.
"For Oracle, winning this business was more than just a client acquisition; it was a powerful endorsement and validation that its Gen2 AI infrastructure could compete head to head with the largest hyperscalers on both performance and cost-effectiveness."
The real test for Oracle’s cash-flow story may come if one large AI customer changes pace and forces a rethink on demand visibility.
If that shift in demand risk is on your mind, read the full narrative for Oracle to see how Oracle’s AI cash engine could still accelerate or stall in the future.
Seeking Alternatives Before The Crowd?
Fresh ideas tend to move first. By the time momentum is obvious and prices are moving quickly, the easier entry points may have passed. Scan these under the radar for now opportunities and consider them before attention increases.
- Explore higher income potential by tracking companies described as 26 dividend fortresses. Use it to identify yields that could help anchor your portfolio before others focus on the payout story.
- Review businesses highlighted within the 53 AI infrastructure stocks to gain exposure to the hardware and services that support AI activity while interest develops.
- Monitor electrification trends by scanning producers in the 16 top copper producer stocks. Build your watchlist around potential shifts in metals demand while they are still emerging.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com