
VinFast Auto (VFS) Stock Looks Overvalued At Its Current Sales Base
VinFast Auto has seen its share price fall sharply over the past few years, and with fresh headlines around widening losses and legal investigations, the key issue now is how firmly its current US$3.09 price is anchored to its sales base. For anyone looking at the stock today, the practical question is whether the revenue VinFast is generating can carry the valuation the market is placing on it.
- Over the last 5 years, VinFast Auto shares have fallen 68.3%. This puts the focus squarely on whether the remaining market value is still well supported by the company’s sales profile.
- Recent reports of a more than doubled operating loss, a deeply negative gross margin and law firm investigations suggest that scaling its global electric vehicle operations may require heavier spending and slower improvement in profitability. This can affect how investors think about the level and timing of future sales needed to underpin the current price.
- There is a second opinion on VinFast Auto worth weighing. See what analysts think VinFast Auto's shares could be worth.
The issue now is whether VinFast Auto's current share price is adequately backed by the sales it is producing today and is expected to produce in the future.
To put VinFast Auto in context and to stress test your thesis on loss-making EV players, it can help to compare it with our screener containing 20 high quality undiscovered gems.
Has VinFast Auto Run Too Far on Sales?
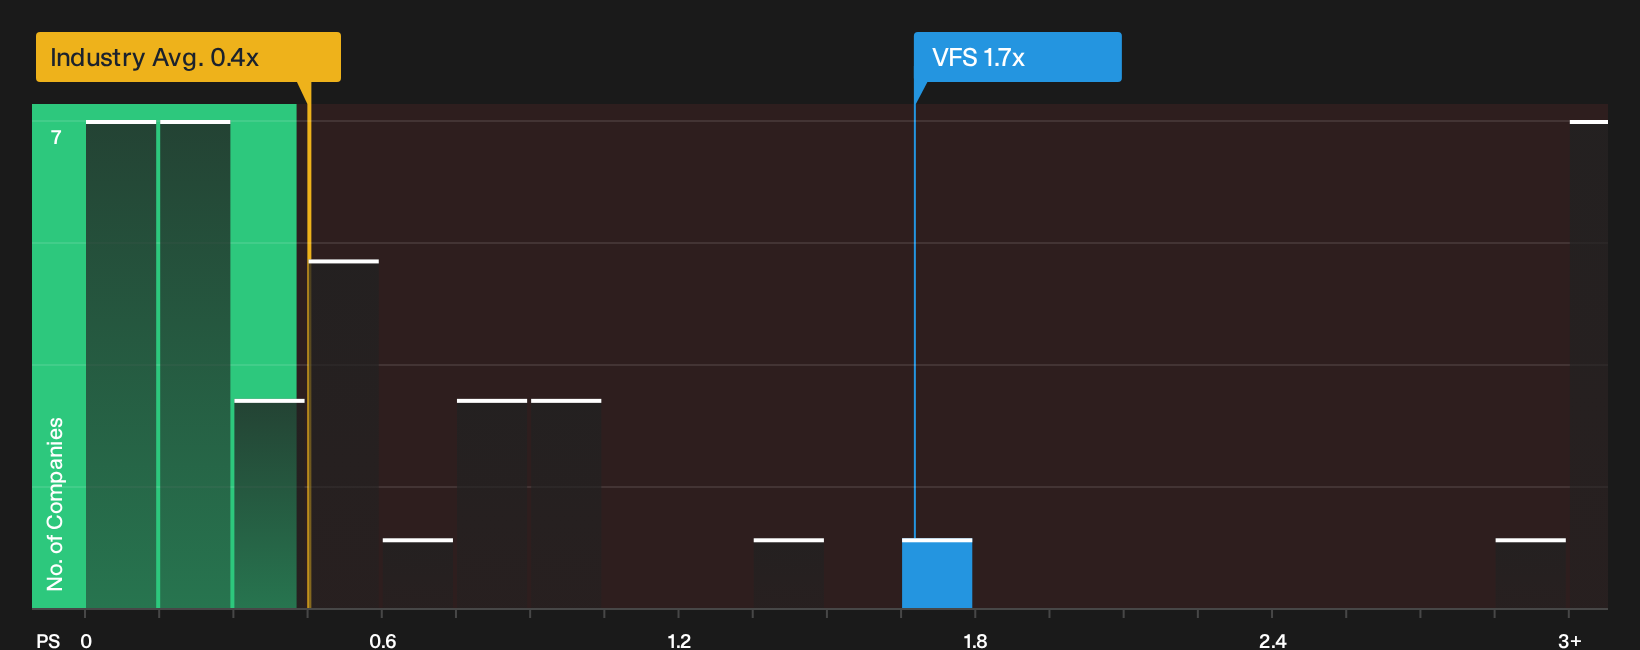
P/S fits VinFast Auto better than P/E because the business is still reporting sizeable losses and sales are the clearest anchor available. Right now the stock trades on a P/S of about 1.7x, compared with roughly 0.45x for the wider auto industry and around 1.3x for closer peers.
The in house fair multiple model points to a much lower ratio once the company’s loss profile, risk and scale are factored in, so the current 1.7x screens as overvalued on this framework rather than merely punchy. Because the model is heavily penalising the ongoing negative free cash flow and weak margins, that gap is best read as a caution flag, not a precise target level for VinFast Auto. After the recent disclosure of a larger operating loss and the start of law firm investigations, the market is still pricing the shares at a premium P/S that assumes the sales base will become much more valuable over time. Explore the numbers behind VinFast Auto's P/S valuation.
The VinFast Auto Narrative: What Would Justify Today's Price?
Simply Wall St's Narratives for VinFast Auto pick up where the valuation puzzle leaves off and set out what sort of future growth, margins and earnings profile would need to play out for the stock to be worth meaningfully more or less than today’s price. Each scenario anchors its number to a clear view on how VinFast Auto's scale, profitability and risk might evolve, giving you something concrete to revisit as new information comes through.
One of the top narratives on VinFast Auto: 44% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is VinFast Auto successfully executing its shift to an asset light model and GSM ecosystem partnership so that higher vehicle volumes, lower capital intensity and targeted cost reductions can move margins closer to break even..."
Discover why this Narrative puts VinFast Auto at 44% undervalued.
One more VinFast Auto angle worth checking before you move on
Valuation only tells part of the story for VinFast Auto, and Simply Wall St's broader checks have flagged specific risk signals that are important to weigh for yourself. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com