
Siemens (XTRA:SIE) Lifts 2027 Forecasts, Is The Upside Already Priced In?
Siemens (XTRA:SIE) lifted its revenue and earnings growth forecasts for fiscal 2027 after reporting record free cash flow and strong orders, which has put its digital infrastructure and data center exposure firmly in focus for investors.
At a share price of €277.0, Siemens has edged higher over the past week and month, while the 90 day share price return is slightly lower. The year to date share price return of 14.89% sits alongside a 1 year total shareholder return of 12.96% and a very strong 3 year total shareholder return of 114.34%. This signals that longer term momentum has already been powerful and recent gains reflect investors weighing the upgraded 2027 ambitions, the planned Siemens Healthineers spin off and the Lauterbach acquisition against that already strong run.
Scan beyond Siemens and evaluate other industrials with strong automation and infrastructure exposure using our hand picked 42 power grid technology and infrastructure stocks
After that kind of multi year run and the announcement of fresh 2027 targets, Siemens is no longer an obvious under the radar opportunity. Does the current valuation still leave enough upside to justify new money going in?
Most Popular Narrative: 9% Undervalued
On Simply Wall St, the analyst consensus Narrative puts Siemens' fair value at €304.96, which is above the last close of €277. This view uses analysts' combined revenue, earnings and discount rate assumptions to judge whether the current price still lines up with the long term story.
The order book has strengthened since the prior narrative, with group backlog reported at €124b in Q2 FY26 and €132b in Q3 FY26 on book to bill ratios above 1.2, which extends multi year revenue visibility and can support more stable earnings and free cash flow.
See why 187 investors see Siemens as 9% undervalued.
Result: Fair Value of €304.96 (UNDERVALUED)
Still, the Siemens narrative can crack if large project demand softens under trade or tariff pressure, or if Digital Industries growth cools against tougher competition.
Find out about the key risks to this Siemens narrative.
Another View On Siemens: Earnings Multiple Premium
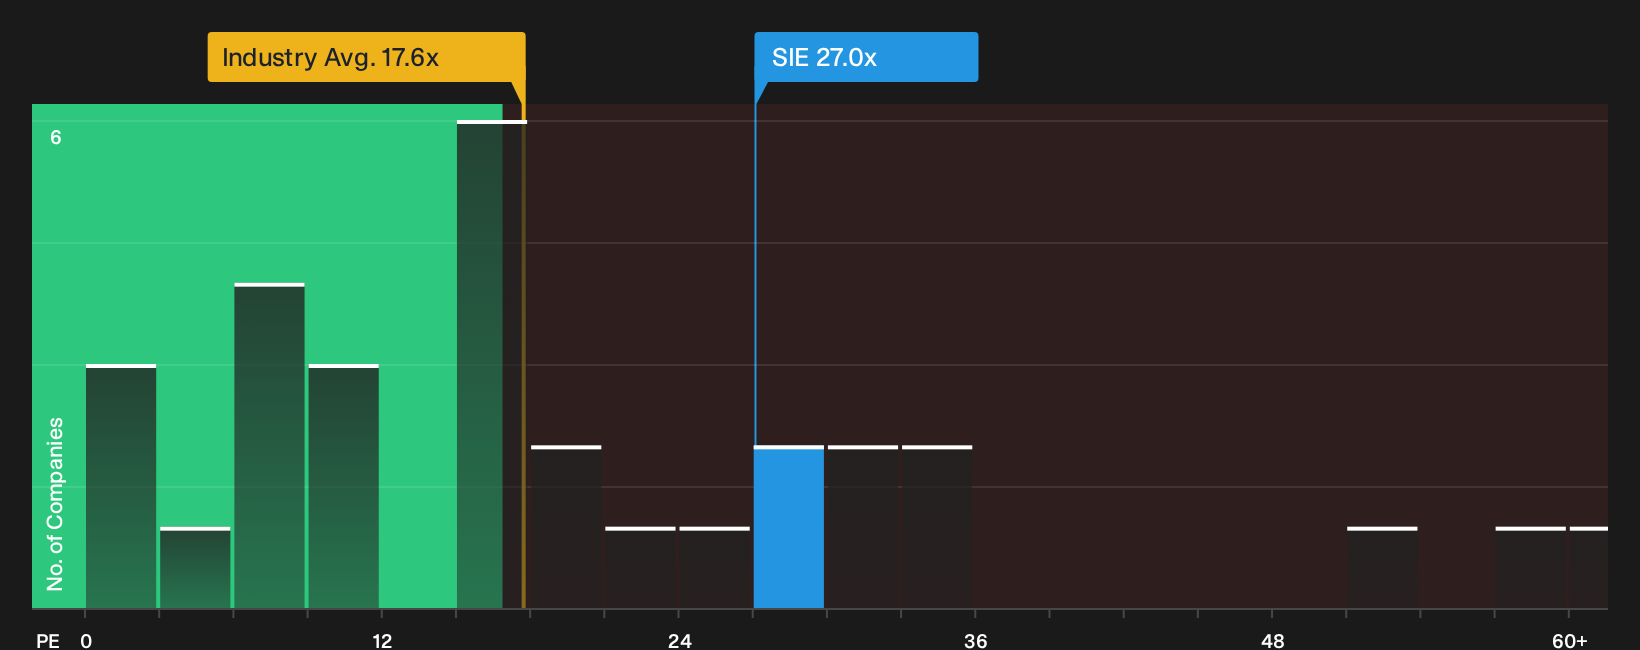
The analyst narrative and SWS DCF work suggest Siemens may have upside from €277, yet the market is already paying about 27x earnings. That compares with 17.6x for the wider European industrials group and 21.1x for closer peers, even though the fair ratio for Siemens is 28.2x.
So the share price sits between peers and the fair ratio, which leaves less room for error if growth or margins fall short. Is that premium a reasonable price for Siemens' digital and infrastructure mix, or is it a signal that expectations are already loaded into the multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted about whether Siemens' premium P/E is justified or stretched? Act while the data is fresh and stress test both sides of the story by weighing 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Siemens?
Do not stop at Siemens if you want a fuller watchlist. Use targeted screeners to surface different types of opportunities that might fit your risk and income preferences.
- Target resilient income by reviewing companies with reliable payouts through the 213 dividend fortresses.
- Hunt for potential mispricing by scanning a curated pool of quality candidates using the 195 high quality undervalued stocks.
- Prioritise capital protection by focusing on businesses with stronger balance sheets and fundamentals via the list of solid balance sheet and fundamentals (198 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com