
AMD Bounced 10% but Is Still Down 32% in a Month. Wedbush Sees $600
Advanced Micro Devices (NASDAQ:AMD) rose 9.7% today to $443.61. Shares are still down 31.69% over the past month. The 24/7 Wall St. price target for AMD sits at $471.81, indicating 6.36% upside. The model rates the stock a buy with high confidence.
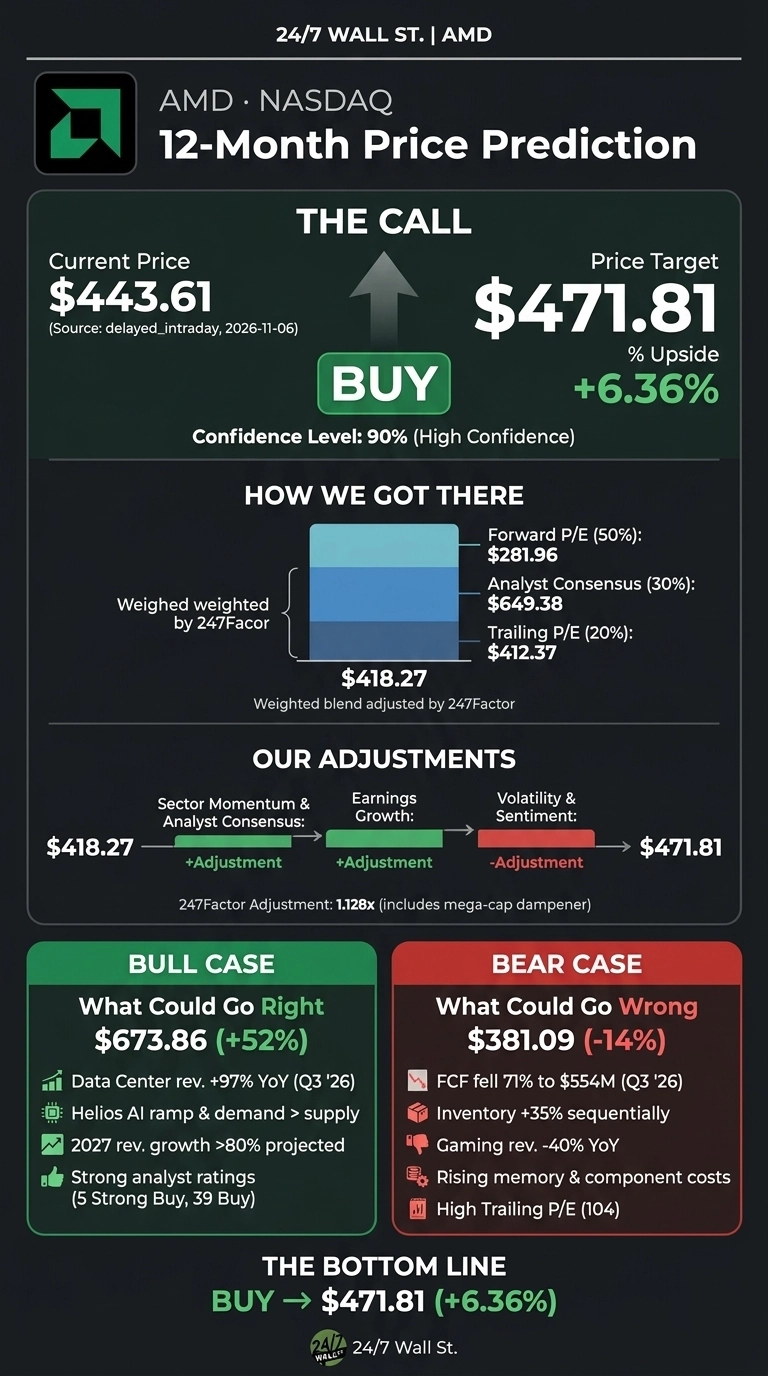 24/7 Wall St. 24/7 Wall St. Price Target Summary Metric Value Current Price $443.61 Price Target from 24/7 Wall St. $471.81 Upside 6.36% Recommendation BUY Confidence Level 90%
Our target is well below the Wedbush figure of $600. It is also below the Wall Street consensus of $648.24. That gap comes from how heavily our model leans on forward earnings. Even so, AMD has a clear path toward the top of our range after its record quarter.
Record Quarter Collides With a Sharp AI SelloffAMD is down 21.68% over the past week but up 107.14% year to date. The stock trades 32.6% below its 52-week high of $658.52. On Thursday, a broad AI selloff gave the NASDAQ its worst day since April 2025. Chip stocks bounced back today.
The selloff came right after strong results. Third-quarter revenue rose 44.68% to $13.377 billion, ahead of the $13.085 billion estimate. Non-GAAP EPS of $2.09 beat the $1.9366 consensus. Data Center sales rose 97% to $8.546 billion. Wedbush analyst Matt Bryson said the results “met the bar.”
Why Bulls See $674 Within ReachAMD expects fourth-quarter revenue of about $17 billion, which would be roughly 66% growth. Management also projects 2027 revenue growth of more than 80%.
Several major AI customers, including Anthropic and OpenAI, have Helios racks running. CEO Lisa Su said on the call that “demand is higher than supply.” Wall Street ratings stand at 5 Strong Buys, 39 Buys and 11 Holds, with no Sells. The bull case reaches $673.86.
Cash Flow Strain Tests the Bulls
Free cash flow fell 71% to $554 million. Inventory grew 35% from the prior quarter. Gaming sales dropped 40%, and AMD expects a double-digit fall in the PC market in 2027. In AMD’s defense, management says the inventory build supports data center demand.
GAAP EPS of $1.46 also includes a non-cash warrant charge. Rising memory costs and a trailing P/E of 104 remain real risks. The bear case sits at $381.09.
How AMD Stacks Up Against Its Peers Company Latest Qtr Revenue Growth Latest Qtr Free Cash Flow AMD 44.68% $554M NVIDIA (NASDAQ:NVDA) 105.85% $21.341B Broadcom (NASDAQ:AVGO) 85.5% $13.665BThe GPU leader that AMD’s Instinct chips compete against directly is NVIDIA. The stock trades at a P/E of 37 with a 75% non-GAAP gross margin. AMD guides to about 55%. At that discount in profitability, a premium multiple for AMD needs the Helios ramp to work.
Broadcom is the custom-chip threat to general-purpose GPUs. Its AI semiconductor revenue rose 221% to $16.70 billion. Both peers turn far more of their revenue into cash, which supports our more conservative target.
Upside Is Real but Modest at Today’s PriceThe 24/7 Wall St. price target of $471.81 comes with a buy rating and 90% confidence. The fourth-quarter guidance is what tips the scale.
I would turn more constructive if Helios shipments drive data center sales up about 50% from the third quarter. I would grow cautious if free cash flow keeps contracting while inventory builds. The fundamentals look stronger than the selloff indicating, at least for now.
Year Price Target from 24/7 Wall St. 2026 $425.48 2027 $483.72 2028 $534.04 2029 $591.60 2030 $635.15AMD needs to keep executing on its current strategy for these projections to hold. The MI500 roadmap may lift results well above these figures. Supply limits or a pullback in AI spending could leave them short. The traits that showed up early in past chip winners are the ones we cataloged in a free playbook on spotting the next Nvidia.