
Is Pelagos Insurance Capital (PLGO) Fully Valued As Earnings Mixed With A Dividend Increase?
Pelagos Insurance Capital (PLGO) is back in focus after third quarter results showed revenue ahead of expectations, while net income and earnings per share declined compared with the same period last year, along with a fresh dividend increase.
The third quarter update and dividend increase landed after a strong run in Pelagos Insurance Capital’s shares, with a 30-day share price return of 13.56% and a 90-day gain of 22.95%. Meanwhile, the 1-year total shareholder return of 50.36% and 3-year total shareholder return of 116.50% point to momentum that has been building rather than fading.
Scan how Pelagos Insurance Capital compares with a curated 30 resilient stocks with low risk scores list that has shown resilience through mixed earnings and shifting dividend signals.
Bulls point to Pelagos Insurance Capital’s strong price run and higher dividend, while bears fixate on the weaker quarterly earnings. Which story does the valuation support next?
Most Popular Narrative: 10.2% Overvalued
Pelagos Insurance Capital closed at $27.97 against a narrative fair value of $25.39, with the analyst consensus Narrative on Simply Wall St tying that gap to how well its capital allocator model and reinsurance approach hold up over time.
Ongoing focus on disciplined underwriting and active use of quota share and whole account reinsurance, including maintaining targeted loss ratios and keeping major catastrophe exposures as a controlled share of shareholders’ equity, can help Pelagos Insurance Capital protect net margins and operating earnings despite softening pricing.
See why 2 investors see Pelagos Insurance Capital as 10% overvalued.
Result: Fair Value of $25.39 (OVERVALUED)
Still, the narrative can crack if weaker pricing pressure feeds through to slimmer underwriting margins, or if large catastrophe losses keep pushing combined ratios toward 100% more often.
Find out about the key risks to this Pelagos Insurance Capital narrative.
Another View: Pelagos Insurance Capital Through Earnings Multiples
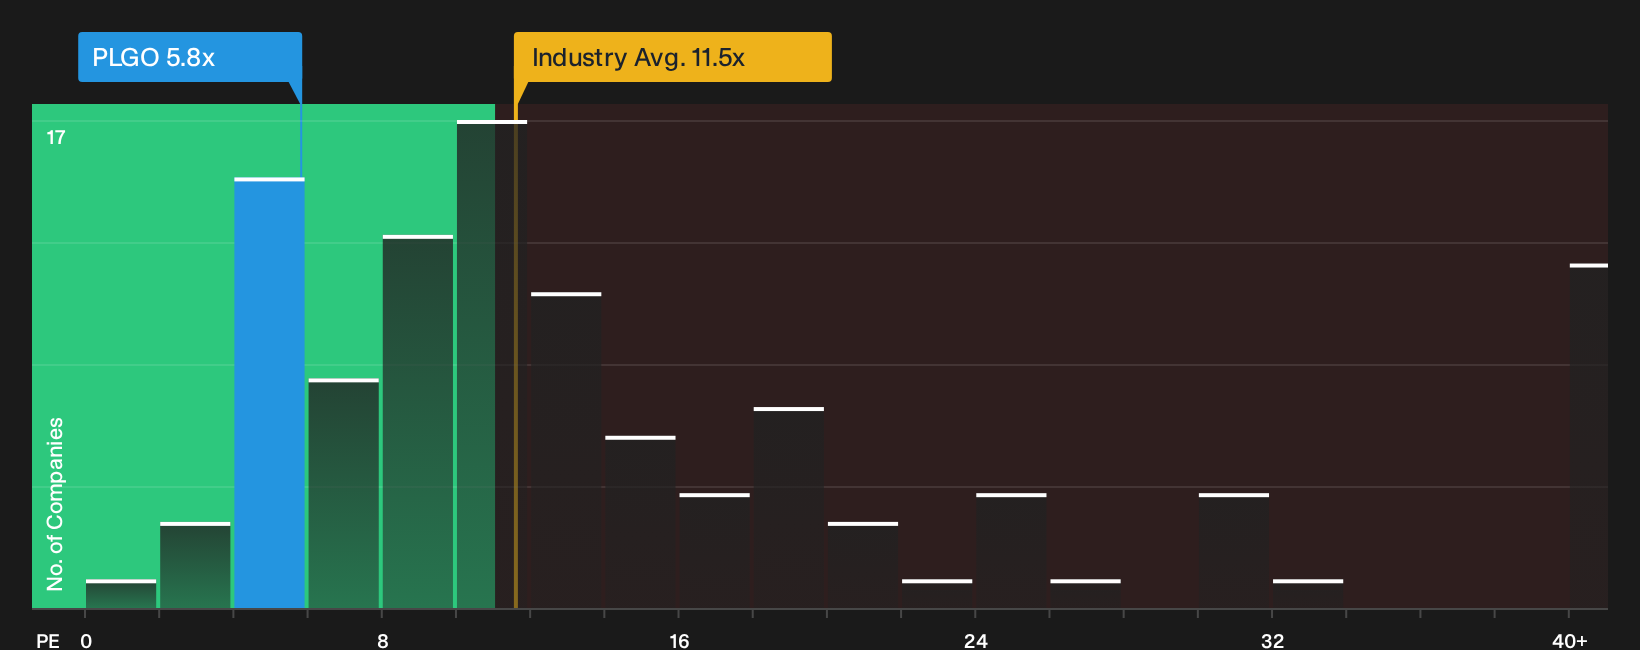
The narrative fair value of $25.39 suggests Pelagos Insurance Capital is 10.2% overvalued, yet the earnings ratios tell a different story. PLGO trades on a P/E of 5.8x, compared with 11.6x for the US Insurance group, peers around 24x, and a fair ratio of 11x based on Simply Wall St regression work.
That gap indicates a wide margin between what the market currently pays for Pelagos Insurance Capital and where the fair ratio suggests the P/E could move. This can cut both ways, because any shift toward the sector or fair ratio would meaningfully change the valuation. The key question is which signal carries more weight at the moment.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Pelagos Insurance Capital can feel confusing, and inertia is a risk on its own, so review both the bullish and bearish angles in light of the 3 key rewards and 1 important warning sign.
Looking for more Pelagos Insurance Capital style ideas?
If Pelagos Insurance Capital has sharpened your focus on valuation and risk, do not stop here. These other angles can help you build a broader watchlist.
- Target resilience first and hunt for businesses that pair sturdy finances with measured risk profiles using the 30 resilient stocks with low risk scores.
- Zero in on value and scan for attractively priced opportunities with solid fundamentals through the 19 high quality undiscovered gems.
- Prioritise income and stability by checking companies with robust payouts and dependable balance sheets via the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com