
Huntsman (HUN) Reports Smaller Losses, Is The Stock Still Undervalued?
Dividend announcement and recent earnings put Huntsman in focus
Huntsman (HUN) is back on investor radars after its board declared a US$0.0875 per share cash dividend and released third quarter results that showed higher sales alongside a smaller net loss.
Recent price action reflects that narrative. Huntsman shares have climbed strongly over the past month, with a 30 day share price return of 21.19% from a starting point that leaves the year to date move still down 4.02%, while the 1 year total shareholder return of 18.86% contrasts with a much weaker 3 and 5 year total shareholder performance. As a result, momentum appears more like a short term rebuild in confidence rather than a full trend change.
Scan Huntsman alongside a hand picked 32 high quality undervalued stocks that also pairs recent earnings shifts with beaten up long term performance to see how this rebound story compares.
The question now is whether Huntsman’s recent rebound reflects improving business fundamentals after smaller losses and steadier dividends, or whether sentiment has simply swung too far ahead of what the valuation supports.
Most Popular Narrative: 6.9% Undervalued
On the latest numbers, Huntsman closed at $9.78, while the analyst consensus Narrative on Simply Wall St puts fair value at $10.50 using a 9.6% discount rate. That gap frames a modest undervaluation story rather than a deep value case.
Expected completion of the all stock merger with Olin in early 2027, with management targeting about $400 million of cost and integration synergies and tighter chlorine linked value chains, could support higher consolidated EBITDA margins and more stable earnings power for Huntsman.
See why 14 investors see Huntsman as 7% undervalued.
Result: Fair Value of $10.50 (UNDERVALUED)
Still, the Huntsman story can change quickly if construction and housing demand stay weak, or if formula based pricing lags any spike in feedstock and energy costs.
Find out about the key risks to this Huntsman narrative.
Another view on Huntsman’s valuation
The analyst fair value of $10.50 suggests Huntsman is modestly undervalued, yet the Simply Wall St DCF model indicates a future cash flow value of $8.11, which places the recent $9.78 price above that estimate. Two frameworks, two very different comfort levels for buyers and holders.
Before leaning on either approach too heavily, it helps to understand how the long term cash flow assumptions are built into the model and where your own expectations differ from them, Look into how the SWS DCF model arrives at its fair value.
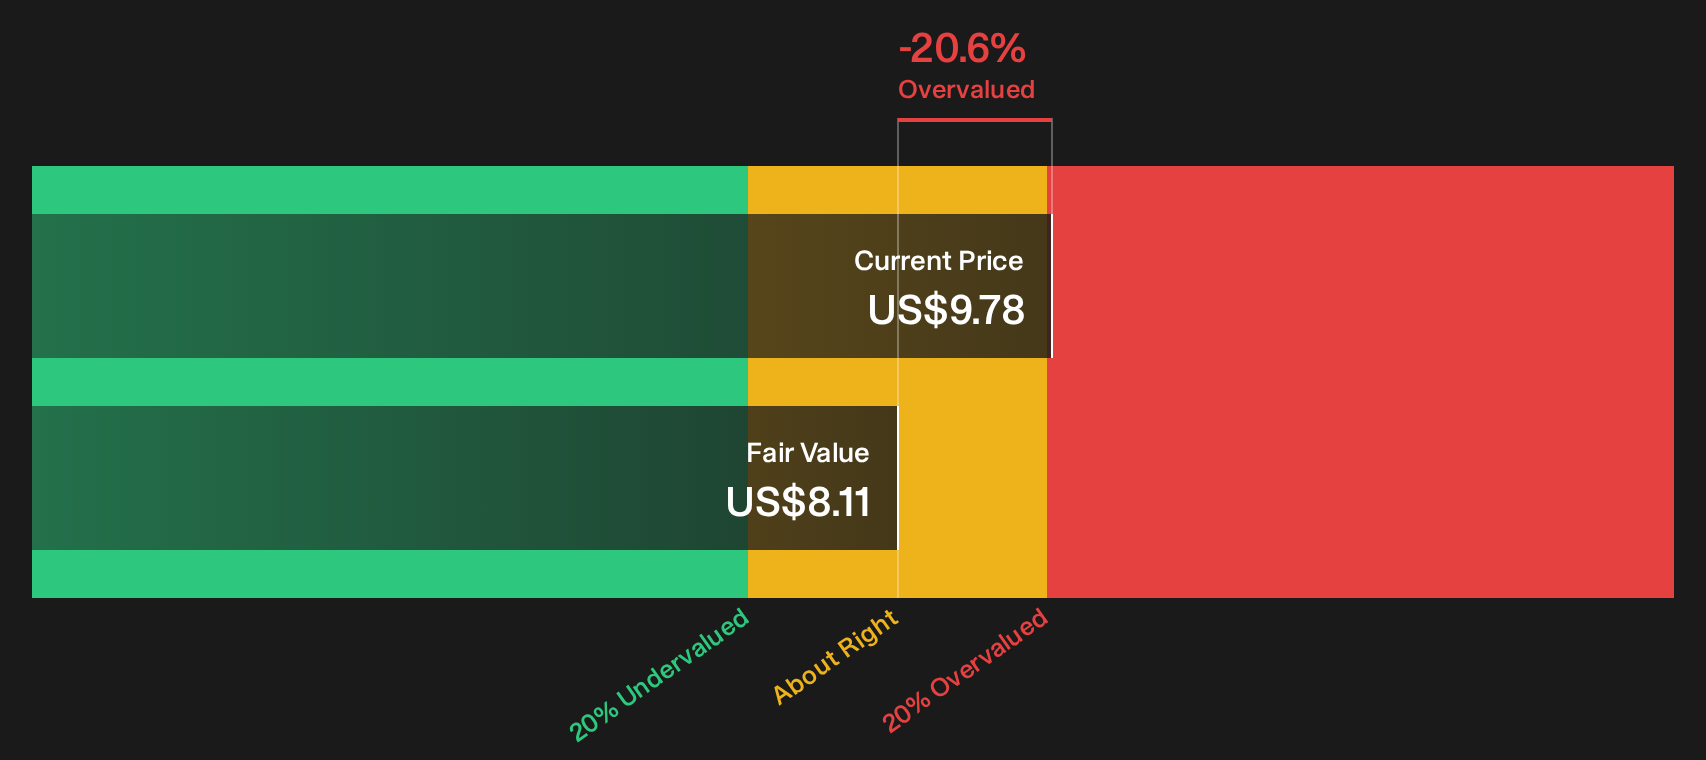
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Huntsman for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If you are sensing a mixed message of rebound and caution around Huntsman and want your own perspective rather than relying on a single model or narrative, take a few minutes to review the full range of risks and potential upsides, starting with 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Huntsman?
Huntsman might be on your radar today, but your next strong opportunity could come from a very different corner of the market. Use the Simply Wall St Screener to pressure test your thinking and avoid leaving potential upside on the table.
- Target resilience by checking a 30 resilient stocks with low risk scores that focuses on businesses with sturdier balance sheets and less volatile risk profiles.
- Hunt for quality at a discount through a 19 high quality undiscovered gems that highlights companies with solid fundamentals that many investors are still overlooking.
- Build a sturdier core to your portfolio by scanning a list of solid balance sheet and fundamentals (23 results) that emphasises financial strength and consistent fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com