
Should Fastly (FSLY) Revisit Fair Value As Sales, Losses And Guidance Shift?
Fastly (FSLY) drew fresh attention after reporting third quarter sales of US$190.19 million, a reduced net loss of US$11.26 million, and issuing new revenue guidance for the fourth quarter and full year 2026.
Fastly shares moved sharply around the announcement, with a 1-day share price return of 6.28% and a 7-day gain of 12.22%. However, the 30-day share price return declined 36.29% and the 90-day return fell 42.33%, leaving year-to-date momentum still positive at 69.38%.
Scan how Fastly compares with other high-momentum tech names by checking stocks in the 19 high quality undiscovered gems that have strong fundamentals and are still flying under most investors’ radar.
Fastly just paired strong year-to-date gains with a sharp pullback and a narrower loss. From this reset level, does the balance of risk and potential reward still support fresh buying, based on the current valuation?
Most Popular Narrative: 39.5% Undervalued
Fastly's last close at $17.26 sits well below the analyst consensus Narrative fair value of $28.55, which implies a sizeable discount based on that framework. The analyst consensus Narrative on Simply Wall St ties that gap directly to specific growth drivers and margin targets rather than a vague optimism story.
The acceleration of edge computing and AI related workloads is still in play and has moved on as Fastly rolls out AI Runtime Control, AI Firewall and API Enforcement on its edge platform. These offerings can add new usage based revenue streams on top of existing delivery contracts while supporting the company’s 2029 revenue range of US$1.1b to US$1.3b.
See why 35 investors see Fastly as 40% undervalued.
Result: Fair Value of $28.55 (UNDERVALUED)
Still, Fastly’s reliance on a small group of large enterprises and intense competition from much bigger cloud and edge providers could quickly challenge that undervalued story.
Find out about the key risks to this Fastly narrative.
Another View: Fastly Through A Cash Flow Lens
Fastly may look undervalued against the analyst Narrative fair value of $28.55, yet the SWS DCF model paints a more cautious picture. On that cash flow view, Fastly at $17.26 trades above an estimated future cash flow value of $13.67, which points to overvaluation instead of a discount.
That gap suggests investors are paying a premium to the SWS DCF model for Fastly's long term revenue and margin ambitions, rather than getting them for free. The question for you is whether those ambitions feel solid enough to justify paying above modeled cash flows, or if patience makes more sense at this price.
Look into how the SWS DCF model arrives at its fair value.
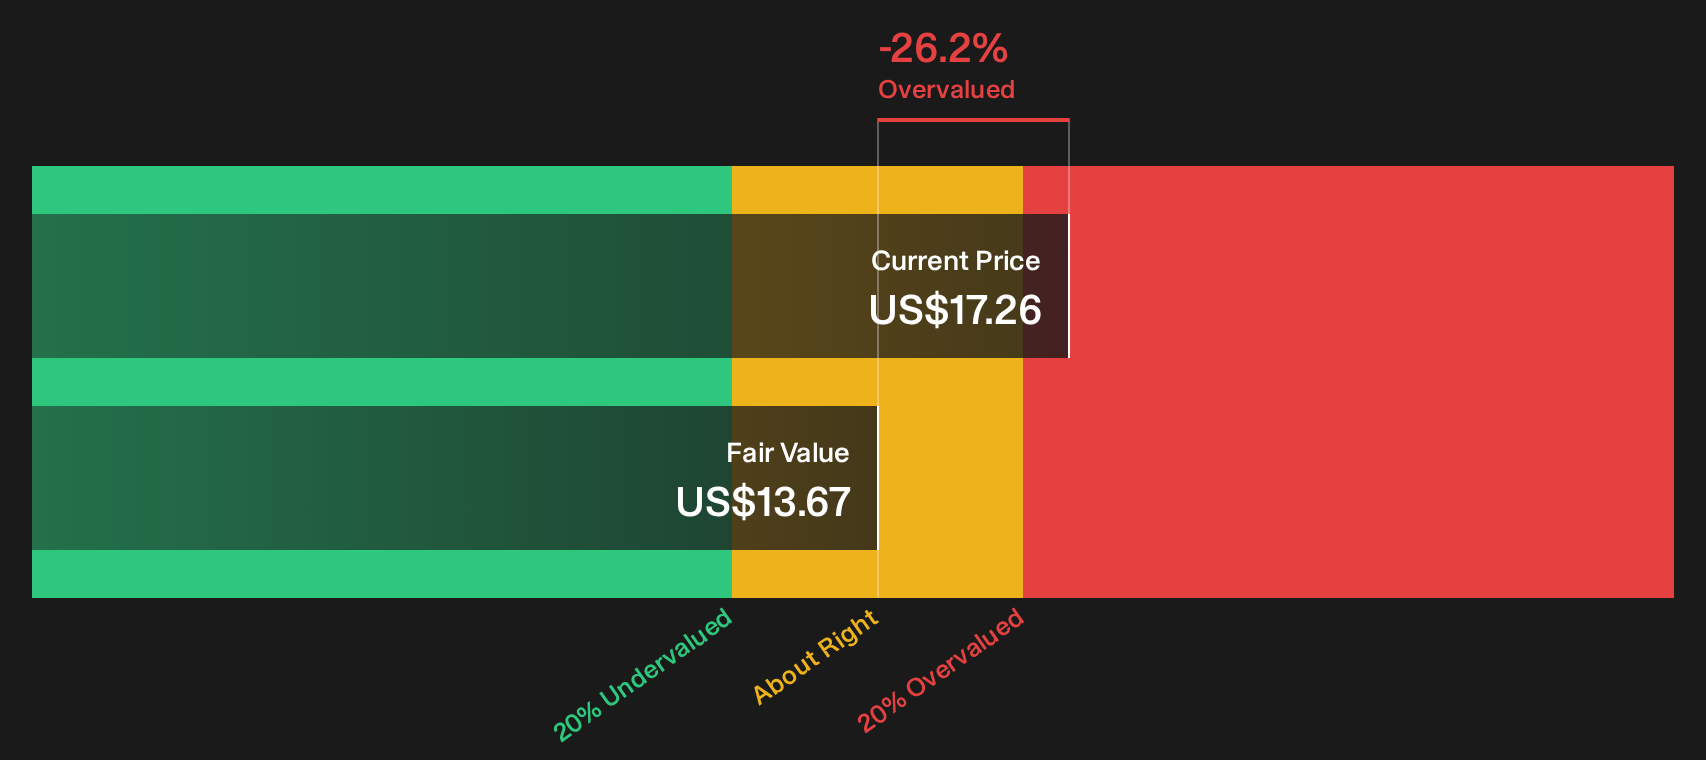
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fastly for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Fastly can either freeze you or push you to check the data yourself and decide quickly where you stand. To weigh both sides of the story, including the upside case and the warning flags others are focused on, review the 2 key rewards and 2 important warning signs
Looking for more Fastly sized investment ideas?
If Fastly has sharpened your focus on risk and reward, do not stop here. The next decision could come from a single well chosen screener result.
- Target steadier opportunities by reviewing the 30 resilient stocks with low risk scores that aim to keep volatility and risk scores in tighter check.
- Hunt for quality at a discount through the 32 high quality undervalued stocks that flag companies with strong fundamentals priced below their estimated worth.
- Build a sturdier core in your portfolio by scanning the list of solid balance sheet and fundamentals (23 results) that highlight financially resilient businesses ready for tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com