
UK AI Infrastructure Stocks With Strong Exposure to Cloud and Data Growth
UK GDP surprising on the upside, with services and AI-linked activity pulling extra weight, has suddenly put the spotlight on cloud and data-driven businesses listed in London. That mix of stronger growth and tighter rates can reward the right kind of tech exposure while punishing the wrong kind. This piece walks through three UK AI and cloud-driven technology and IT services stocks that appear especially exposed to this shift, whether for better or for worse.
The three UK AI and cloud-driven technology and IT services stocks below are just a sample. The full screen surfaced 9 more companies with equally compelling narratives that are not covered here. To identify and analyze those extra opportunities with the same filters applied, head straight to the UK AI and Cloud-Driven Technology & IT Services Stocks screener.
Renishaw (LSE:RSW)
Renishaw taps into the screener theme through its precision hardware and smart manufacturing data platform rather than pure software or cloud, and the analyst consensus Narrative on Simply Wall St argues that this mix is already closely tied to AI related industrial and semiconductor demand.
Renishaw is an engineering and scientific technology group focused on precision measurement, motion control, analytical tools and medical devices, with around £447 million from Industrial Metrology, £261 million from Position Measurement and £107 million from Specialised Technologies, and a market value of roughly £3.7b.
"Renishaw is still seeing AI related semiconductor equipment demand support strong encoder sales in Position Measurement, and the planned increase in encoder manufacturing capacity in FY 2027 with doubled spending on production assets is aimed at turning that demand into higher revenue and operating profit."
What happens to Renishaw’s margin profile if one quiet competitive pressure starts to reshape how much pricing power those higher value systems really have?
If that pricing power really is starting to shift, the full narrative for Renishaw shows how encoder capacity, AI linked demand and competitive pressure could be quietly reshaping Renishaw’s trajectory.

Corero Network Security (AIM:CNS)
Corero Network Security sits close to the heart of this UK AI and cloud-driven theme because its protection tools are wired directly into the pipes that carry data for cloud, telecom and SaaS providers, and the bullish analyst Narrative on Simply Wall St argues that this positioning now matters more as UK services growth leans into AI heavy workloads.
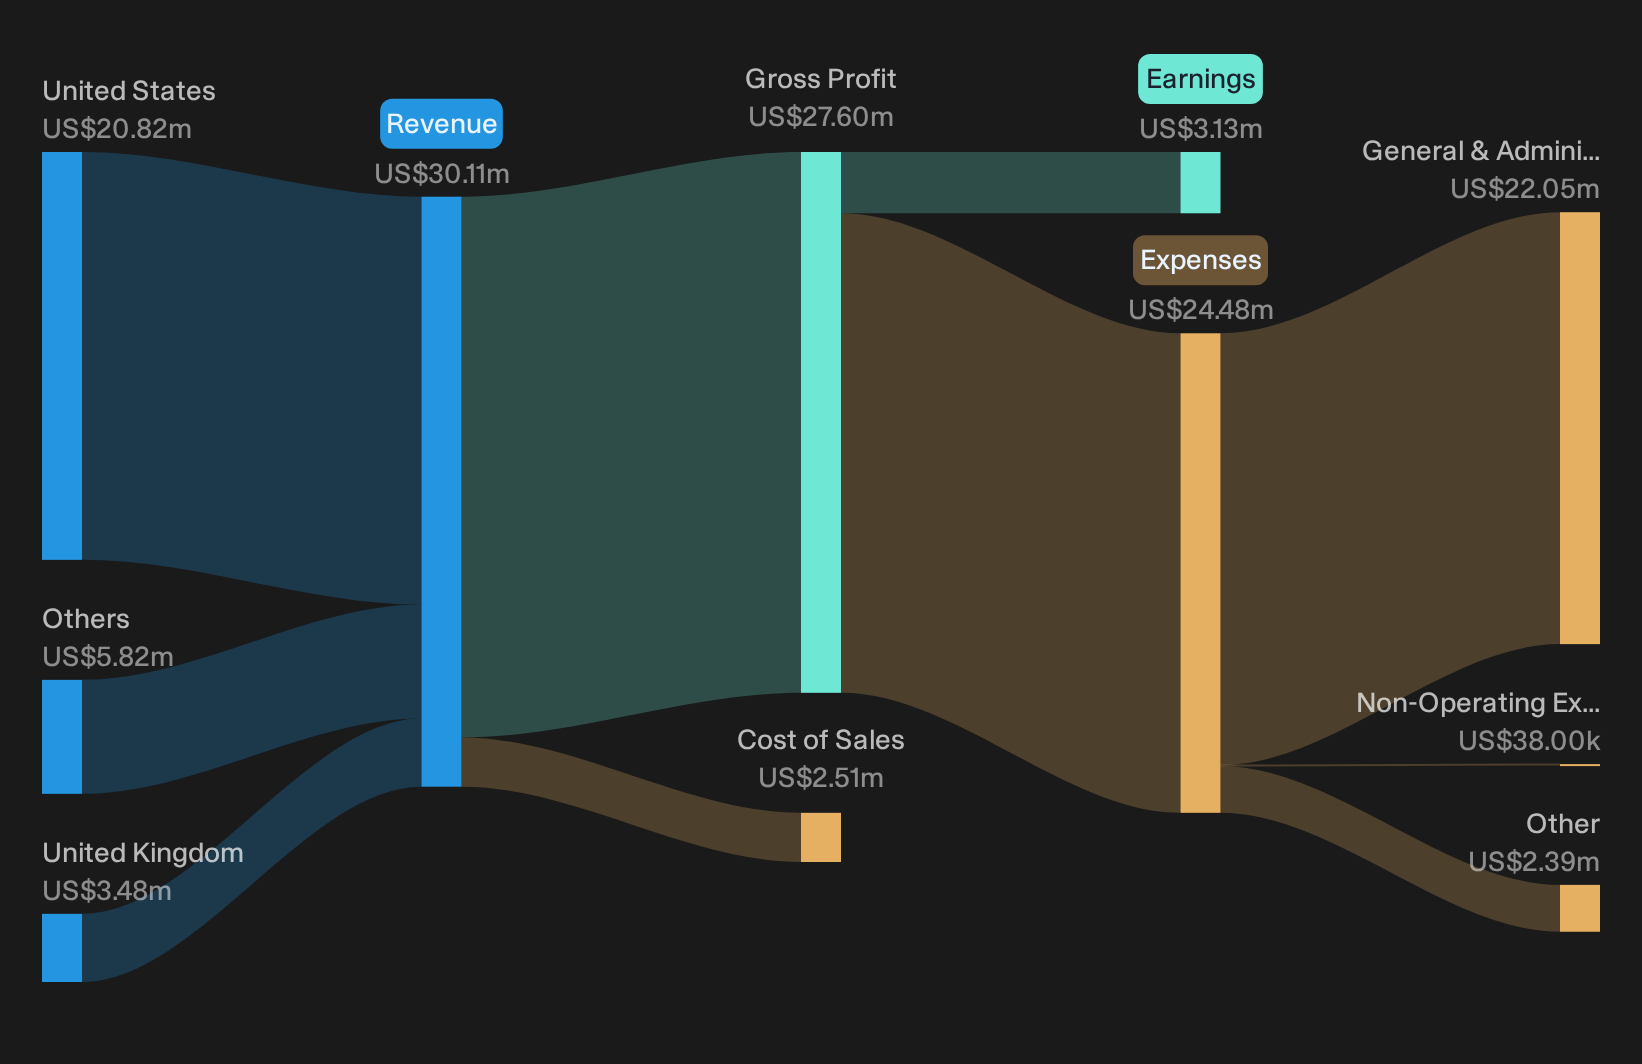
Corero Network Security sells DDoS protection, cloud-native security software and related services, generating about US$30 million in revenue and serving cloud, telecom and enterprise clients, with a market value around £85 million.
"Corero Network Security is repositioning from a single product DDoS provider toward a wider cyber resiliency platform that now includes web application protection, observability, performance monitoring, API security and Zero Trust, which can widen the addressable spend per customer and influence long term revenue and ARR growth."
The real test for Corero Network Security now rests on how one quiet shift in its revenue mix shapes the cash flows backing that growth story.
If that revenue mix shift is what you are watching, the full narrative for Corero Network Security explains how Corero Network Security’s platform push could turn that change into accelerating leverage.
Solid State (AIM:SOLI)
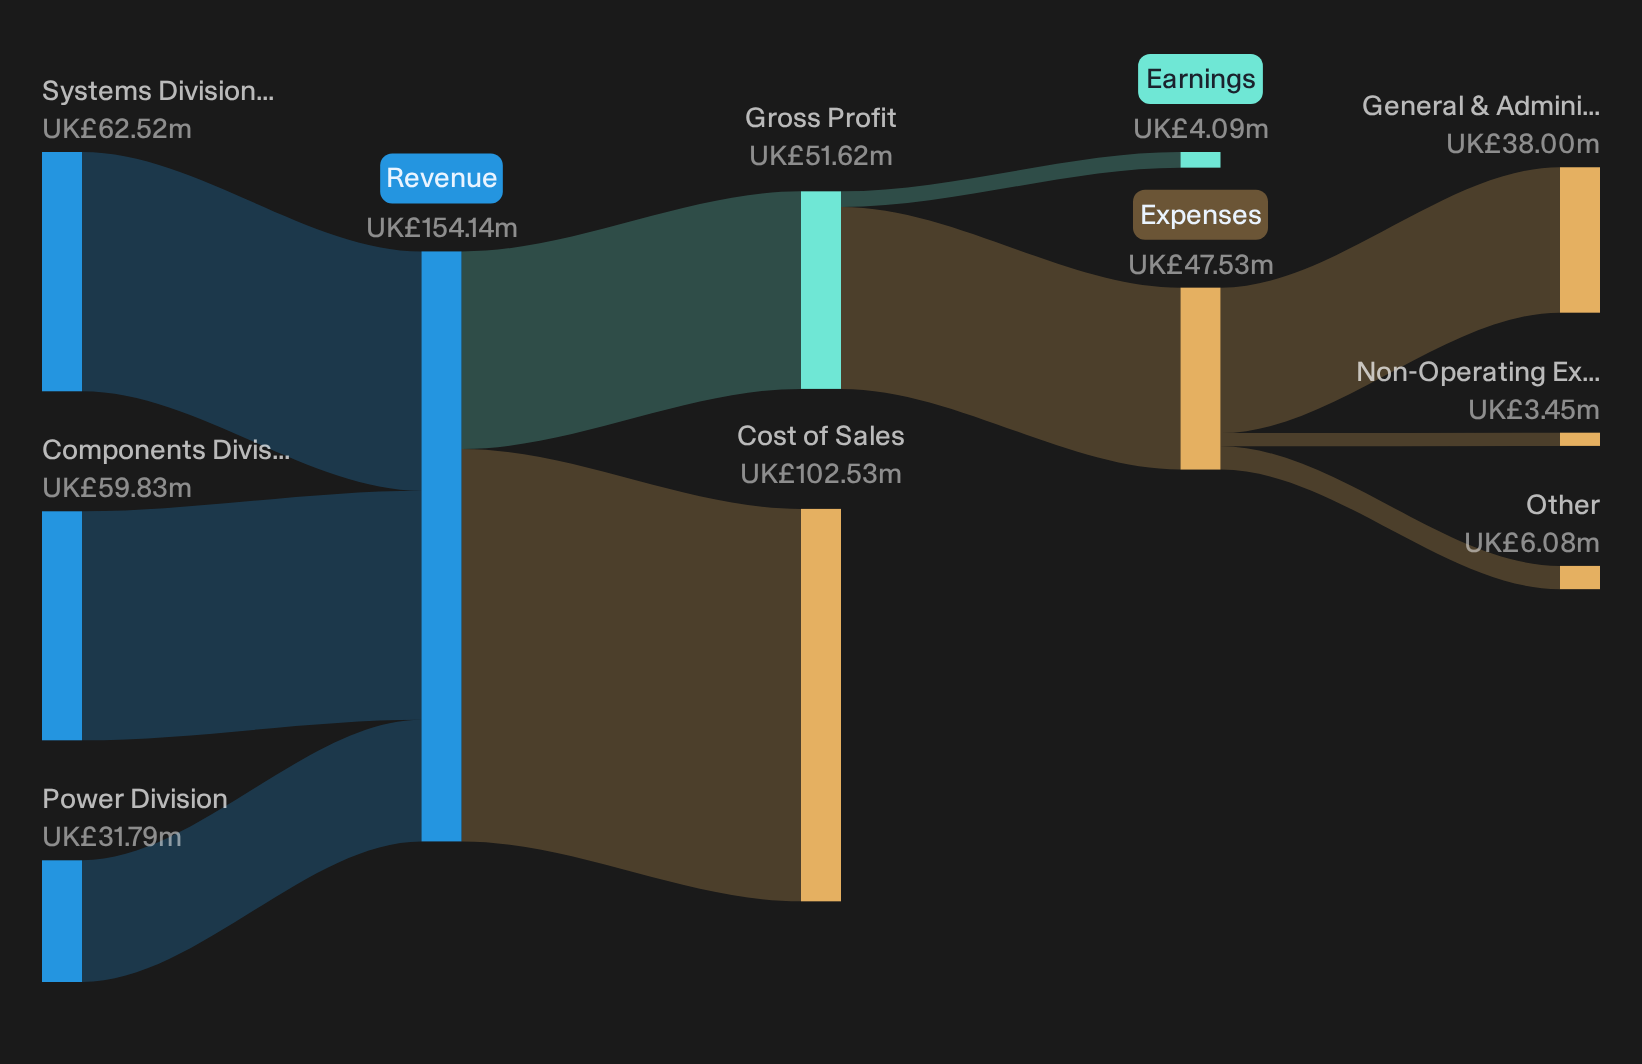
Solid State plugs into the UK AI and cloud-driven theme from the hardware side, supplying electronic components, power systems and engineered solutions that underpin compute, communications and automation projects, with around £62 million from its Systems division, £60 million from Components, £32 million from Power, and a market value near £103 million.
For investors tracking the build-out of AI and cloud infrastructure, Solid State offers a hardware-heavy way to gain exposure to that theme, and the analyst consensus Narrative on Simply Wall St frames that link through its defense and industrial electronics focus.
"Growing defense focus on agile radios, sensors and uncrewed systems aligns with Solid State’s comms, antenna, sensing and UAV power capabilities. This can support future order book growth and higher visibility on revenue."
What happens to Solid State’s earnings profile if a quiet shift in its mix of longer term contracts and own brand products really takes hold?
If that mix shift is on your radar, the full narrative for Solid State shows how contract length, own-brand depth and AI demand could be accelerating an underappreciated earnings profile.
Seeking Fresh Alternatives Before They Fly
Fresh opportunities can move fast. Breakout stories can gain momentum, prices can move, and the best entries can disappear before most investors even get caught up. Scan these ideas while it matters and aim to get in early.
- Spot resilient businesses that aim to hold up when sentiment drops by running the 5 resilient stocks with low risk scores and see which tickers still look prepared for stress.
- Target cash generative compounders before they gain wider attention by screening for 17 high quality undervalued stocks and focus your research time on higher quality balance sheets.
- Ride the build out of future AI infrastructure by checking the curated 53 AI infrastructure stocks that focuses on companies tied directly to compute and data capacity.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com