
How Investors May Respond To Greif Stock After Fourth Quarter Loss
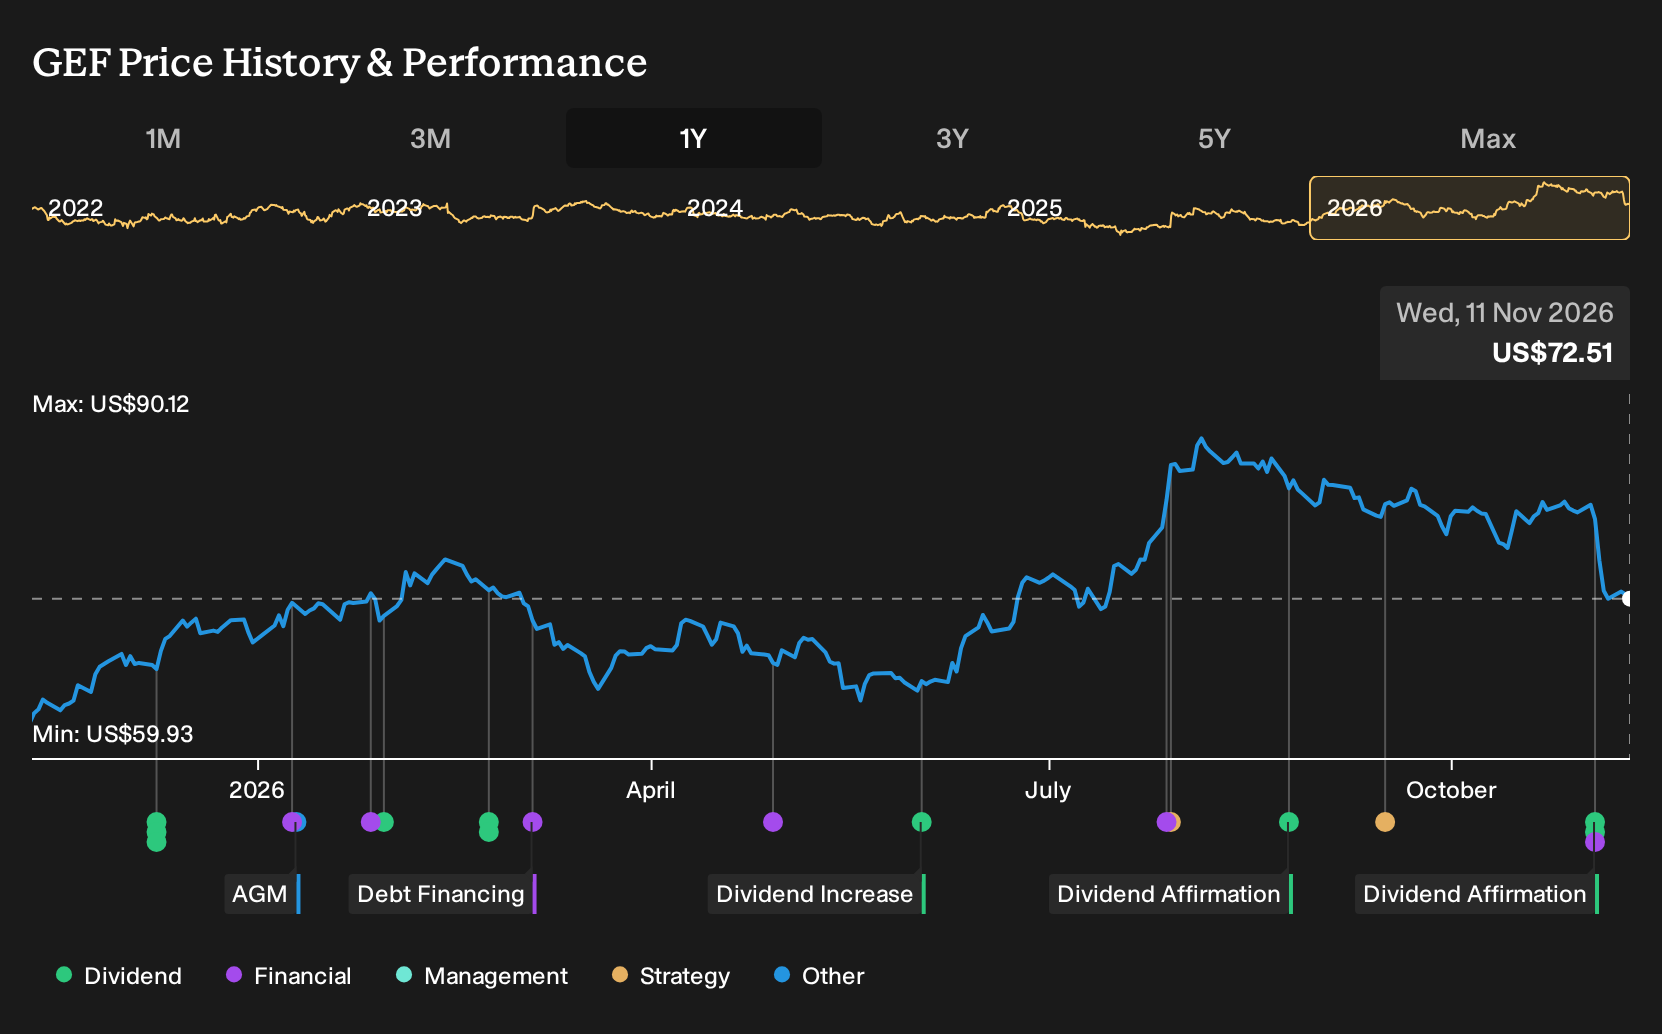
- Greif reported fourth quarter 2026 sales of US$1,143.6 million with a net loss of US$6.5 million and full year net income of US$258.5 million on sales of US$4,376.8 million, while affirming quarterly cash dividends of US$0.62 per Class A share and US$0.92 per Class B share payable on January 1, 2027.
- The combination of a fourth quarter loss and sharply lower full year net income compared with the prior year suggests meaningful cost or operational pressure at Greif, which sits in tension with continued cash returns through dividends on both share classes.
- We will look at how Greif's fourth quarter move from profit to loss may reshape the cost-focused investment narrative investors were using.
Greif Investment Narrative Recap
To own Greif, investors need to be comfortable with a packaging focused group that now leans more heavily on its core metal, polymer and fiber operations after earlier divestments. The analyst consensus narrative on Simply Wall St focuses on cost savings, a higher margin mix and relatively low leverage. The latest quarter introduces a short term wrinkle, with a swing to a US$6.5 million loss despite full year profitability.
The key near term swing factor is whether cost optimization and mix shift can offset softer industrial volumes and input cost pressure. The sharp step down in annual net income to US$258.5 million raises execution risk around that story. Weaker demand in metals, large drums and fiber products, and less favorable regulation for polymers, remain the main operational threats flagged by analysts.
The reaffirmed quarterly dividend of US$0.62 for Class A and US$0.92 for Class B shares is the news item that stands out for this period. It ties directly to the capital return angle that analysts highlight, alongside low leverage and extended debt maturities. Cash returns are clearly still part of the Greif pitch.
At the same time, Simply Wall St notes that the roughly 3.4% yield is not well covered by free cash flow, which makes the dividend decision important when considering risk. With earnings affected by one off items and softer conditions, investors may want to track how future results line up against the remaining US$120 million cost savings target and any pressure this puts on distributions.
Greif's narrative projects US$4.7b revenue and US$278.3 million earnings by 2029. This aligns with analysts assuming 2.6% yearly revenue growth and an earnings increase of about US$49.7 million from the current US$228.6 million level.
Uncover why Greif's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist you might want to weigh is capital returns. The most optimistic Greif analysts were leaning on share repurchases and dividends as core value drivers, backing earnings around US$276.6 million on roughly US$4.7b revenue by 2029. With a quarterly loss and a Class B dividend cut now in play, those upbeat assumptions may face real adjustment.
Explore 3 other Greif fair value estimates, including one that suggests as much as 173% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Greif research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Greif. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Greif's overall financial health at a glance.
Looking for more investment ideas beyond Greif?
Greif might be the starting point for your research, not the finish line. If you want to stress test your income thesis, compare quality, or simply widen your watchlist, the Simply Wall St Screener can help you line up other candidates against the same yardstick.
- If resilience matters most to you, you can start with companies that pair sturdier balance sheets with consistent fundamentals through our list of solid balance sheet and fundamentals (23 results).
- If you are hunting for mispriced quality, you can tighten the focus on businesses that combine stronger cash generation with supportive valuations using the 32 high quality undervalued stocks.
- If income is your anchor, you can scan for payout focused stocks with yields and financial profiles that complement Greif by reviewing the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com