
How Lower Quarterly Earnings Will Impact Avis Budget Group Stock (CAR)
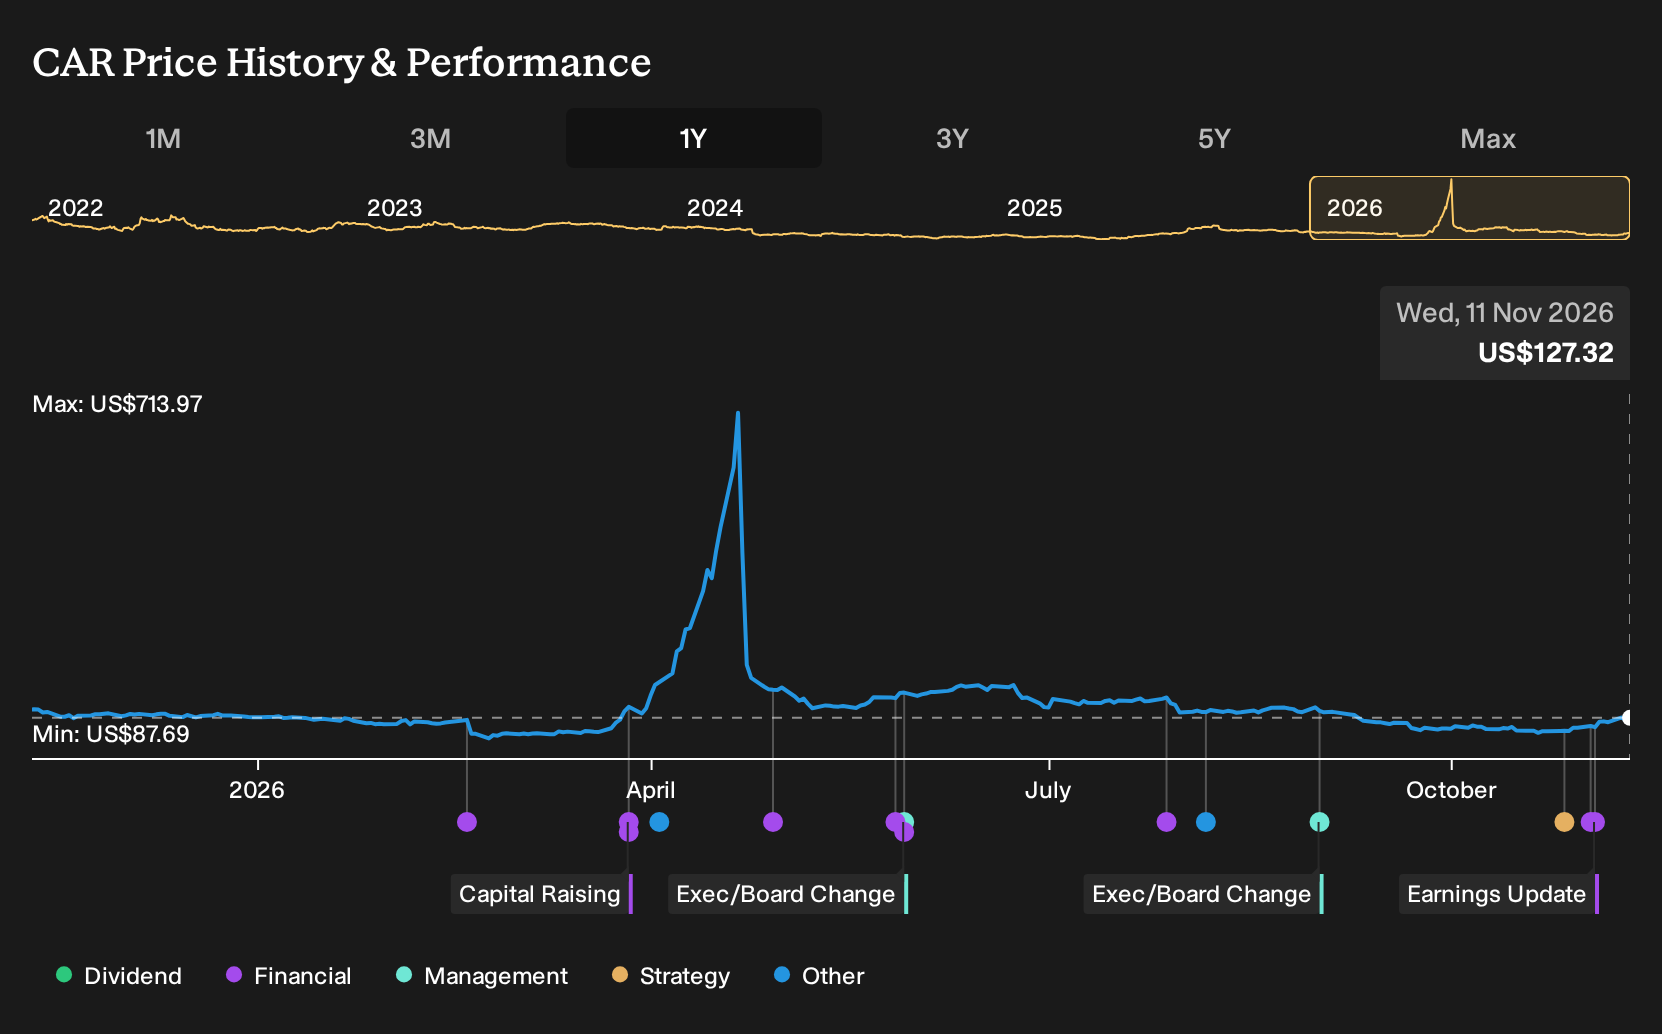
- Avis Budget Group reported third quarter 2026 sales of US$3.436b compared to US$3.519b a year earlier, with net income of US$183 million and diluted earnings per share from continuing operations of US$5.15, down from US$10.11.
- Alongside weaker quarterly profitability, management moved to redeem US$350 million of 5.75% Senior Notes due 2027. This, together with a Federal Court ruling clarifying award coverage for car washers and check-in staff, highlights both cost pressures and efforts to reshape the balance sheet and labour framework.
- The focus now turns to how Avis Budget Group’s investment narrative may evolve in light of sharply lower quarterly earnings per share.
Compare how Avis Budget Group stacks up against other car rental and travel peers under earnings pressure by scanning our hand picked 32 high quality undervalued stocks.
Avis Budget Group Investment Narrative Recap
A shareholder in Avis Budget Group needs to believe the rental platform can turn its premium mix, tighter fleet and technology projects into steadier earnings while carrying meaningful debt. The latest quarter shows pressure on profitability, with diluted EPS from continuing operations at US$5.15, but nine month sales held close to last year and the reported loss narrowed.
In the short term, the key catalyst remains execution on utilization and pricing while recall costs, interest expense and legal matters stay contained. The biggest risk is that recall activity or weaker profitability collide with high leverage, which could strain coverage ratios. The recent results and award ruling do not fundamentally change that equation.
The redemption notice for US$350 million of 5.75% Senior Notes due July 2027 looks most relevant here. According to the analyst consensus Narrative on Simply Wall St, balance sheet repair is already a central part of the story, with earlier commentary pointing to plans to retire those same 2027 notes using a settlement inflow.
By confirming full redemption at par plus accrued interest on December 30, 2026, management is now acting on that piece of the thesis. For you, the operational angle is clear. Lower future interest on those notes may give Avis Budget Group a little more room to absorb recall costs, pursue digital projects and work toward the earnings recovery analysts are modelling.
Avis Budget Group's current analyst consensus narrative points to forecast revenues of US$12.1b and earnings of US$592.8 million by 2029, built on assumed revenue growth of 1.2% per year and an earnings swing of about US$1.23b from a reported loss of US$636.0 million today to the 2029 forecast level.
Uncover why Avis Budget Group's fair value indicates a 9% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternative view focuses less on recalls and more on demand risk. In that story, bearish analysts already expected almost flat revenue at about US$11.9b and earnings of roughly US$453.9 million by 2029, before this earnings miss and debt redemption news. That is a much tougher Avis Budget Group narrative. Use it as a reminder that forecasts vary widely and may shift again as these developments sink in.
Explore 2 other Avis Budget Group fair value estimates, including one that suggests as much as 13% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Avis Budget Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Avis Budget Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avis Budget Group's overall financial health at a glance.
Looking for more investment ideas beyond Avis Budget Group?
If the Avis Budget Group story leaves you wanting a broader watchlist, use this moment to cast the net wider. The Simply Wall St Screener can help you spot other opportunities that fit the type of risk and return profile you want, rather than relying on a single stock to carry your thesis.
- If you want resilient businesses that aim to keep risk in check, start with a curated 30 resilient stocks with low risk scores that may better match a capital preservation mindset.
- For investors who care most about financial strength, look through a list of solid balance sheet and fundamentals (23 results) and see which companies pair sturdy balance sheets with underlying fundamentals.
- If you are hunting for potential future standouts before they attract broad attention, scan a 19 high quality undiscovered gems that focuses on quality first and story second.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com