
Is Platform Launch Altering The Investment Case For Parsons (PSN)?
- Parsons launched the iNET Convergent Response platform and its Altamira unit received a US$63 million, four year NASIC task order, reinforcing the group’s role in mission critical national security, public safety and critical infrastructure work.
- The combination of a new iNET and TAK based solution and fresh NASIC funding highlights Parsons’ push toward higher value, software rich federal programs with long operational lifecycles.
- Attention now turns to how Parsons’ iNET Convergent Response launch could influence the existing investment narrative around higher margin federal work.
Scan how Parsons’ push into mission critical AI infrastructure compares with other contractors by jumping across to our hand picked 53 AI infrastructure stocks in the same theme.
Parsons Investment Narrative Recap
An investor in Parsons needs to be comfortable with a contractor that depends on long contracts, Federal budgets and big city infrastructure programs. The analyst consensus narrative on Simply Wall St focuses on earnings forecasts and margin improvement tied to that backlog. The iNET Convergent Response launch aligns with the shift toward higher value, software-led federal and critical infrastructure work.
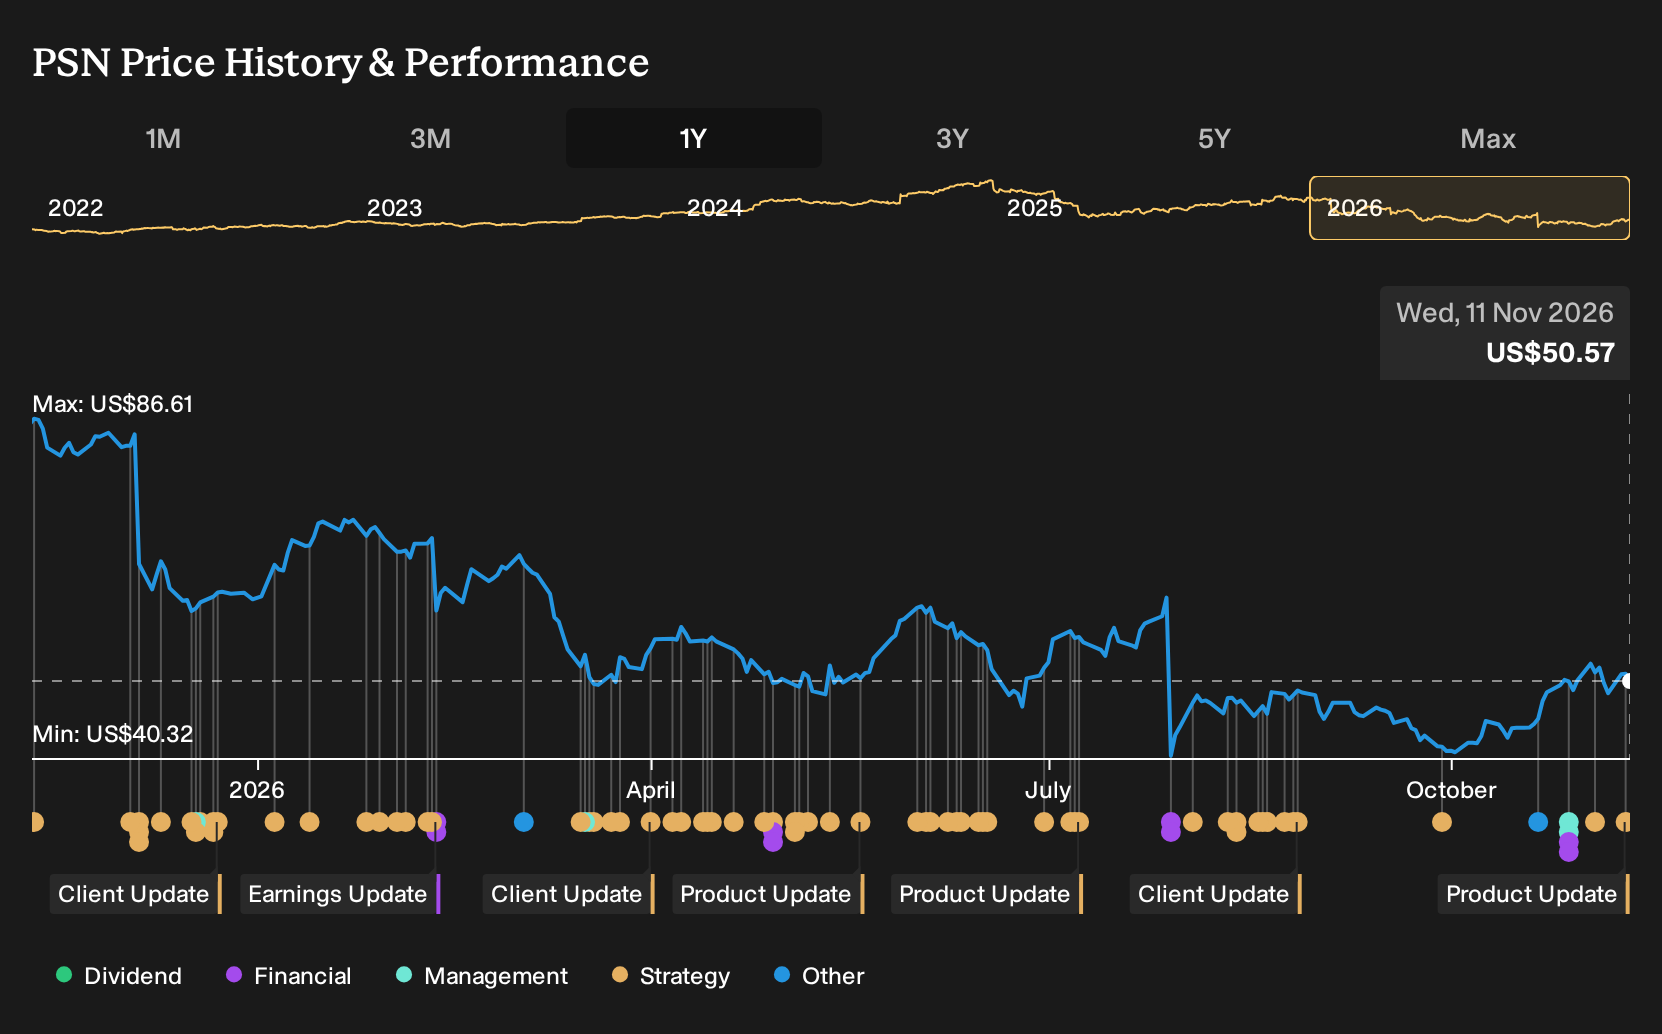
The main short-term swing factor remains execution after the Q2 2026 impact on profit and the reduction to 2026 revenue guidance. New AI-enabled platforms and the Altamira NASIC task order support the margin story, but they do not eliminate the risk of further charges from legacy joint ventures or contract exits.
The iNET Convergent Response announcement appears especially important for that mix-shift narrative. Parsons is aiming to generate more of its Federal Solutions and Critical Infrastructure revenue from productized, AI-driven platforms that can operate across missions instead of relying on one-off project work. That direction is already central to the margin and earnings ramp in the analyst consensus narrative on Simply Wall St.
For potential catalysts, the new platform matters only if Parsons can sell it into large, long-duration programs in areas such as national security, major events and transportation management. Execution risk is significant, given recent margin pressure and one-off losses. Investors will likely watch whether wins tied to iNET and TAK are reflected in backlog and cash generation over the next few reporting periods.
What Parsons’ Forecasts Assume About Growth And Profit
Parsons' narrative projects US$7.2b revenue and US$407.1m earnings by 2029. That profile lines up with analysts assuming 4.6% yearly revenue growth and an earnings increase of about US$249.7m from US$157.4m today.
Uncover why Parsons' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts already framed Parsons around product upside, with forecasts of US$7.7b revenue and US$486.2m earnings by 2029 before this iNET Convergent Response news. You can see how that AI led catalyst view might strengthen from here, or you might disagree entirely. It is worth exploring both angles.
Explore 3 other Parsons fair value estimates, including one that suggests as much as 112% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis.
- A useful starting point for your Parsons research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Parsons. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Parsons' overall financial health at a glance.
Looking For More Investment Ideas Beyond Parsons?
Once you have formed a view on Parsons, it can be useful to compare that thesis with other opportunities that match your risk profile, income needs and time horizon. The Simply Wall St Screener can help you filter the wider market down to a focused watchlist that reflects what you care about most.
- If you want potential growth with small position sizes, start by scanning 12 elite penny stocks with strong financials. Focus on companies that already show relatively strong financial footing.
- For investors who care most about paying a fair price for quality, run a search for companies in the 32 high quality undervalued stocks. Look for a combination of balance sheet strength and solid cash generation.
- If resilience matters more than maximum upside, build a shortlist from the 30 resilient stocks with low risk scores. Then consider which businesses best fit your comfort level.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com