
RB Global (RBA) Stock Could Be Overvalued On Strong Q3 Results
RB Global has delivered a 66.8% gain over the past 3 years, even as the share price has been softer more recently, which puts a spotlight on whether that climb is fully backed by the company’s earnings power today. With the stock last closing at US$95.67 and investors digesting fresh profit headlines, the key issue is how much of that story is already reflected in the multiple the market is willing to pay.
- A 66.8% return over 3 years has materially reshaped long term holders’ gains, which makes the current earnings valuation far more important for anyone considering their next steps with RB Global stock.
- Recent reports of higher revenue, stronger net income and share buybacks suggest management may support earnings per share through both business performance and capital returns, which can influence how rich or restrained an earnings based valuation looks.
- The analysts covering RB Global have run their own numbers. See what analysts think RB Global's shares could be worth.
The issue now is whether RB Global's current price is adequately supported by the earnings the business is generating today and what investors are paying for each dollar of that profit.
If you are weighing whether RB Global’s recent 66.8% three year gain is fully reflected in its P/E, it can help to compare that earnings lens across 32 high quality undervalued stocks.
Does RB Global Look Pricey on Earnings?
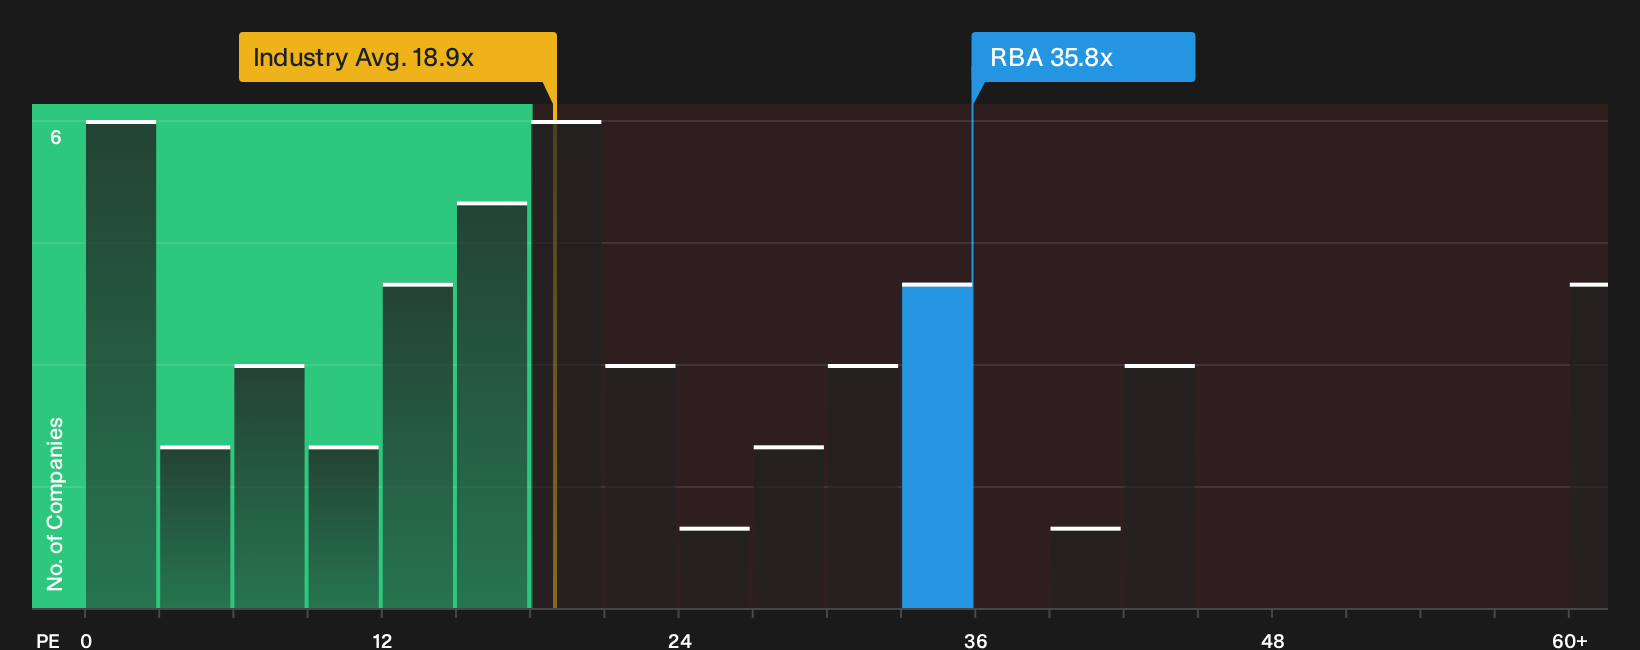
The P/E ratio is the cleanest way to see what you are paying for each dollar of RB Global’s reported profit. At around 35.8x earnings, the stock trades at a clear premium to the Commercial Services industry average of about 18.9x and also screens richer than the peer group near 30.0x.
On a more tailored yardstick that blends RB Global’s growth profile, profitability, scale and risk, the P/E implied by that framework comes out lower than where the market is currently pricing the shares. This points to the stock looking overvalued on this metric. Because recent Q3 2026 revenue and profit headlines have been strong, that premium suggests investors are already paying up for solid execution and continued momentum rather than getting those earnings at a discount. Explore the numbers behind RB Global's P/E valuation.
The RB Global Narrative: What Would Justify Today's Price?
RB Global's valuation puzzle only really comes into focus once you spell out the future that would need to unfold for the current P/E to look cheap or demanding. Simply Wall St Narratives on the Community page do that by setting out concrete assumptions for RB Global's growth, margins and earnings, and by turning each implied fair value into a thesis about the business that you can watch play out over time rather than a one off snapshot.
One of the top narratives on RB Global: 34% undervalued
This Narrative is the bullish analyst Narrative on Simply Wall St, built on the most optimistic analyst price target and forecasts, not one person's view.
"BigIron brings RB Global a U.S. agriculture platform into a roughly US$60b annual transactional market. This opens up a path to layer auction, data and service fees…"
Discover why this Narrative puts RB Global at 34% undervalued.
One more RB Global check that belongs beside the valuation
Price tags tell only part of the RB Global story, because the research checks also flag specific risk indicators that sit outside the P/E and earnings picture and deserve your attention. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com