
Eton Pharmaceuticals (ETON) Stock May Be Fully Priced After Its Huge Run
Eton Pharmaceuticals has seen its share price move sharply in recent years, which puts fresh attention on one question for you as an investor. Is the current valuation supported by the company’s earnings power, or is the price running ahead of what the business is actually generating today?
- Over the past 3 years the stock has delivered a very large gain of about 18x, which puts real pressure on the justification coming from its profit stream.
- Recent updates on new products and a richer drug pipeline can shape expectations for future profitability and the durability of current margins. This in turn feeds directly into how much investors may be willing to pay for each dollar of earnings.
- The analysts covering Eton Pharmaceuticals have run their own numbers. See what analysts think Eton Pharmaceuticals's shares could be worth.
The issue now is whether Eton Pharmaceuticals’ current share price is reasonable when you line it up against the earnings it produces today and what those results suggest for the future.
If you want to test the same earnings question across a wider set of companies, compare Eton Pharmaceuticals with a curated list of 32 high quality undervalued stocks.
Does Eton Pharmaceuticals Look Pricey on Earnings?
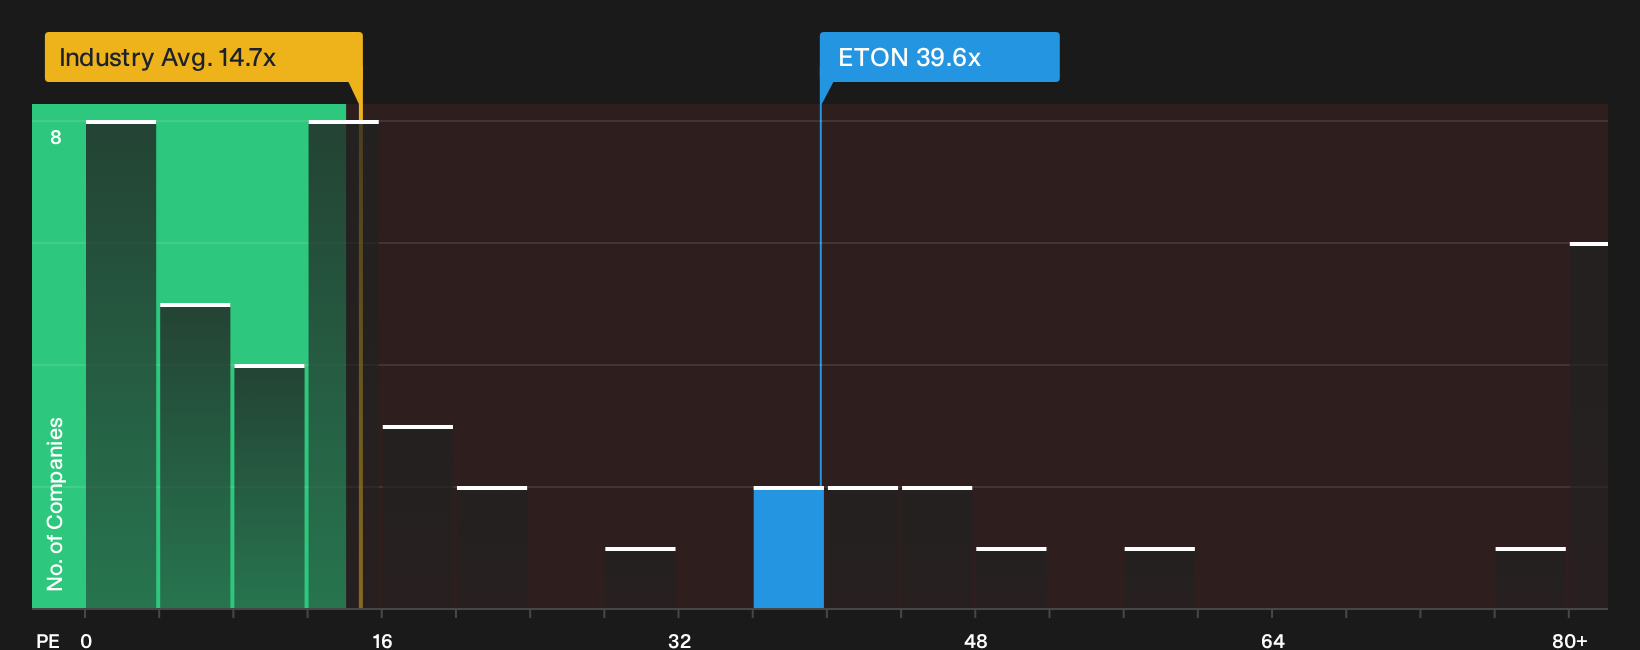
The P/E ratio suits Eton Pharmaceuticals because earnings are now a key reference point for what investors are paying for the business. On this measure, the stock trades at about 39.6x earnings, compared with a Pharmaceuticals sector average near 14.7x and a peer grouping around 11.0x. That leaves the shares valued at a substantial premium to both the broader industry and similar companies on an earnings basis.
The fair value framework, which adjusts for Eton Pharmaceuticals’ growth profile, margins, size and risk, points to a lower P/E than where the stock currently trades, so the shares screen as overvalued on this lens. Because the recent Q3 2026 update highlighted strong results and a higher full year outlook, part of this richer multiple likely reflects investors already baking in optimistic expectations for the pipeline and future profitability. If you are weighing an entry point, you need to decide whether that premium is justified by the earnings power you expect the company to deliver over time. Explore the numbers behind Eton Pharmaceuticals's P/E valuation.
The Eton Pharmaceuticals Narrative: What Would Justify Today's Price?
Narratives for Eton Pharmaceuticals pick up where the valuation question leaves off by spelling out which paths for growth, margins and earnings would need to play out for the current share price to look materially higher or lower over time. Each one turns that fair value view into a clear and testable idea about Eton Pharmaceuticals' business so you can track how the story holds up as fresh information arrives.
One of the top narratives on Eton Pharmaceuticals: roughly fairly valued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The current valuation implies the share price does not fully reflect Eton Pharmaceuticals’ high-margin profile, growing rare disease franchise and the potential contribution from upcoming neurology and ultra-rare programs..."
Discover why this Narrative puts Eton Pharmaceuticals at roughly fairly valued.
One More Angle On Eton Pharmaceuticals Worth Checking
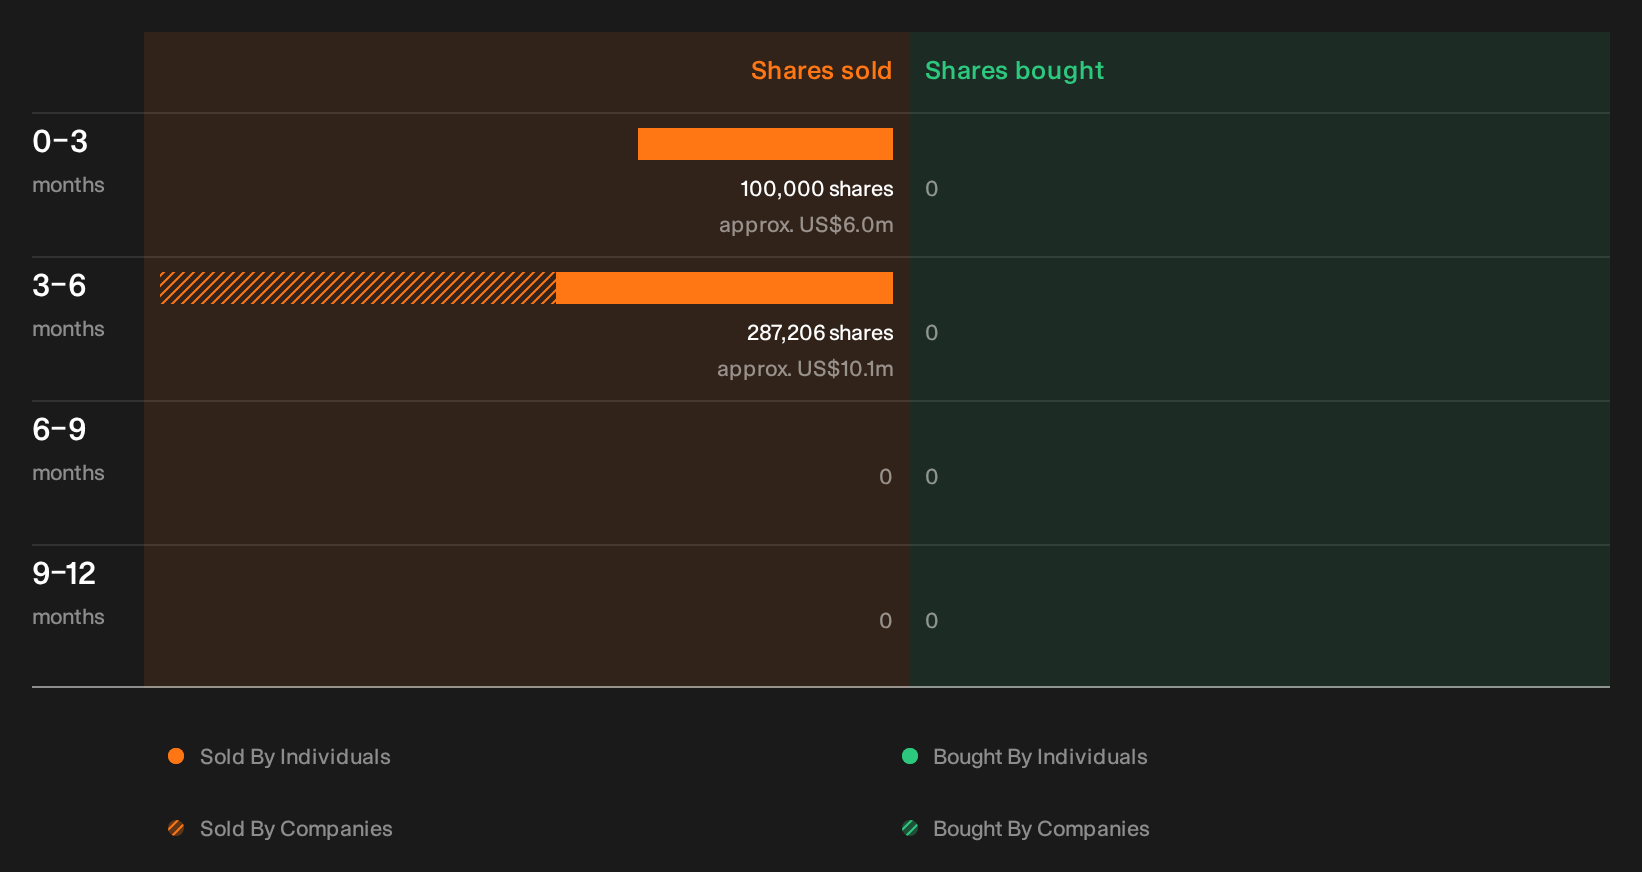
Valuation only tells part of the story for Eton Pharmaceuticals, because recent trades by company insiders can sometimes hint at a different message that our checks have started to pick up. See the recent insider selling flagged for Eton Pharmaceuticals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com