
D.R. Horton (DHI) Could Be 2% Undervalued On Earnings Dip And New 2027 Guidance
D.R. Horton (DHI) has just packed three big updates into one day: fourth quarter and full year earnings declined year over year, the quarterly dividend was lifted to $0.50, and management issued fresh 2027 revenue guidance.
The fresh guidance and dividend move landed against a choppy tape for D.R. Horton. The share price is down 1.5% on the day and 6.1% over the past week, yet still up 9.8% over 30 days, which points to momentum cooling after a recent rebound. Over a longer horizon, total shareholder return of 2.6% over one year and 53.5% over five years suggests the stock has rewarded patient holders, despite the current wobble around earnings and the new outlook.
Compare D.R. Horton’s earnings wobble and dividend lift with a curated 32 high quality undervalued stocks that may be primed for their own rerating after recent news flow.
D.R. Horton looks like a solid homebuilder with a bigger dividend and clear revenue guidance on the table. After the recent earnings slip and share pullback, is that strength actually selling at a fair price today?
Most Popular Narrative: 1.7% Undervalued
D.R. Horton’s analyst consensus Narrative on Simply Wall St pegs fair value at $150, a touch above the latest close at $147.48. This points to only a modest gap for investors to weigh using an 8.58% discount rate.
The main thing that has to go right is that D.R. Horton continues to execute on capital efficient land use and operating efficiency, using its lot control strategy, external developers, and cycle time improvements to offset higher lot costs and sustained incentives.
The current numbers on margins, incentives, cash generation, leverage, and capital returns to shareholders imply a share price that does not fully reflect the narrative that D.R. Horton is undervalued and bullish.
See why 61 investors see D.R. Horton as 2% undervalued.
Result: Fair Value of $150 (UNDERVALUED)
Still, the narrative can crack if sales incentives remain heavy enough to squeeze margins, or if legal disputes around mold and mortgage practices escalate costs.
Find out about the key risks to this D.R. Horton narrative.
Another View: D.R. Horton Through A Cash Flow Lens
The analyst narrative leans on a fair value of $150 per D.R. Horton share, which frames the stock as modestly undervalued. A different tool, the SWS DCF model, points in the opposite direction, with an estimated future cash flow value of $125.16 that sits below the current $147.48 share price. That gap casts D.R. Horton as overvalued on this measure and raises a simple question for you as an investor. Which story do you trust more, the earnings based target or the cash flow math?
Before leaning toward either side, it can help to see how those cash flow assumptions are built and where they might be most sensitive to changes in growth or margins, Look into how the SWS DCF model arrives at its fair value.
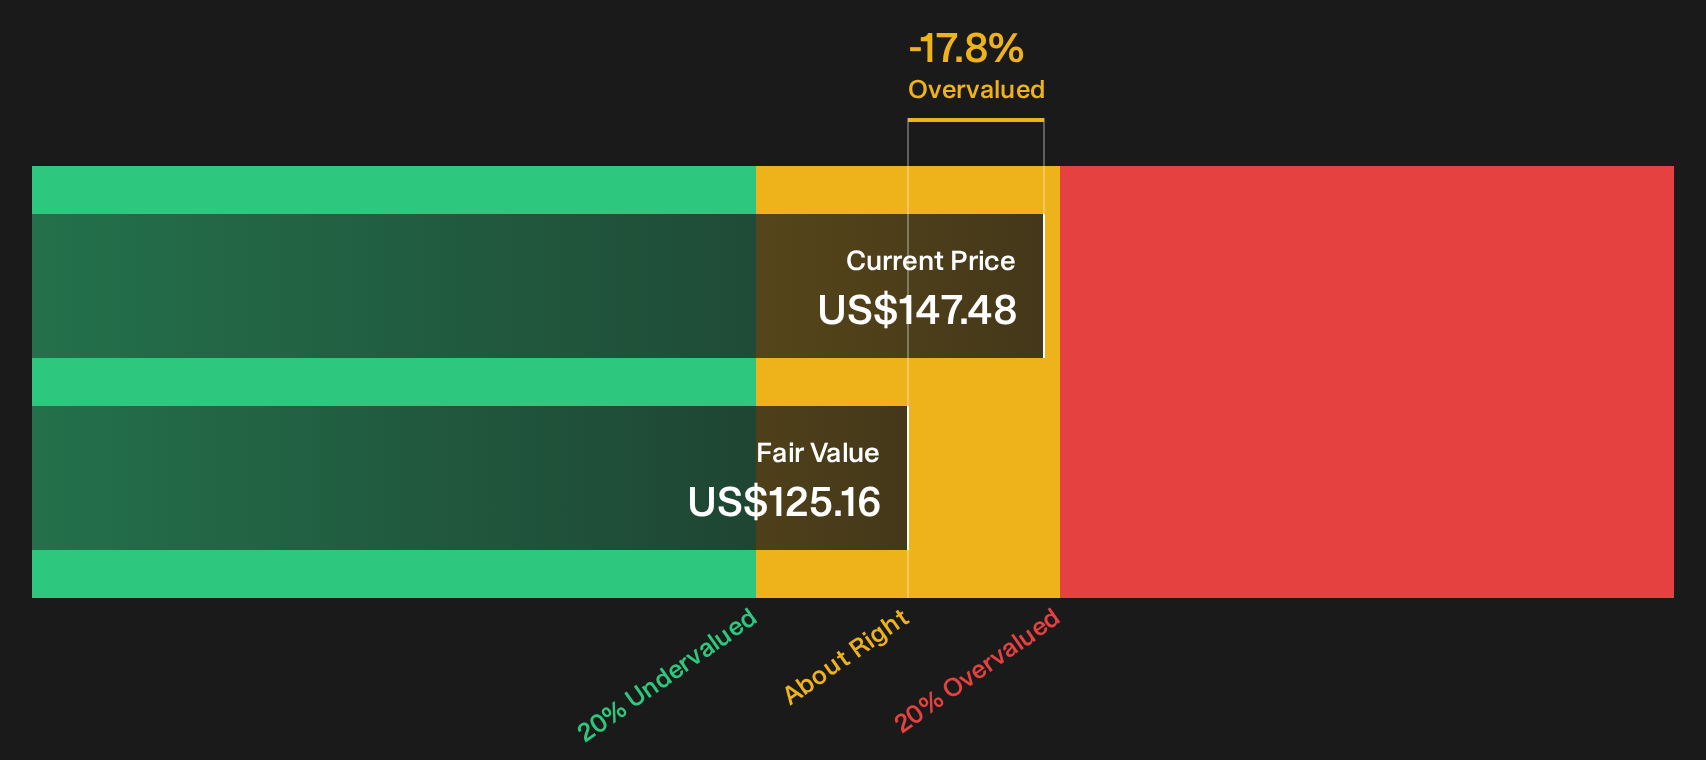
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out D.R. Horton for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around D.R. Horton feel hard to square, that is the point. Move fast, pull up the data, and test the optimism yourself with 3 key rewards.
Looking for more investment ideas beyond D.R. Horton?
If you only stop at D.R. Horton, you miss a wider field of opportunities that could better fit your goals, risk comfort, and timeline.
- Target higher yield potential by scanning for sturdier income candidates through our 6 dividend fortresses.
- Hunt for quality at a discount by shortlisting companies that look mispriced on fundamentals using the 32 high quality undervalued stocks.
- Prioritize resilience by filtering for businesses with robust finances via the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com