
Is KB Home (KBH) A Bargain After Its Recent Share Price Swing?
KB Home (KBH) has drawn fresh attention after its recent share move, with the price closing at US$50.04 and a market value of about US$3.07b. Investors are weighing that against mixed return figures.
The recent pullback, including a 0.85% 1 day share price decline and a 5.8% drop over the past week, comes after a strong 20.2% 1 month share price return. However, the 1 year total shareholder return is down 16.5%, indicating shorter term momentum has improved even as longer term performance remains under pressure.
Scan how KB Home compares with other housing related opportunities by running the hand picked list of solid balance sheet and fundamentals (23 results) while this pullback is still front of mind.
So is KB Home’s sharp swing just sentiment snapping back after a rough year, or a closer reflection of what the underlying business now looks worth?
Most Popular Narrative: 3% Undervalued
KB Home's last close at $50.04 sits a little below the analyst consensus Narrative fair value of $51.57, which is built using a 10.1% discount rate and detailed revenue and earnings forecasts published on Simply Wall St in the analyst consensus Narrative on Simply Wall St.
KB Home is focusing on maintaining attractive pricing by offering compelling value relative to local market conditions, and is now leaning more on higher margin Built to Order product that carries a margin premium compared with inventory homes as that mix trends toward roughly three quarters of deliveries. This mix shift can support housing gross margin and earnings.
See why 14 investors see KB Home as 3% undervalued.
Result: Fair Value of $51.57 (UNDERVALUED)
Still, the KB Home narrative can be knocked off course if weak buyer confidence keeps housing revenues under pressure, or if resale listings force deeper price cuts.
Find out about the key risks to this KB Home narrative.
Another View: KB Home Through A Cash Flow Lens
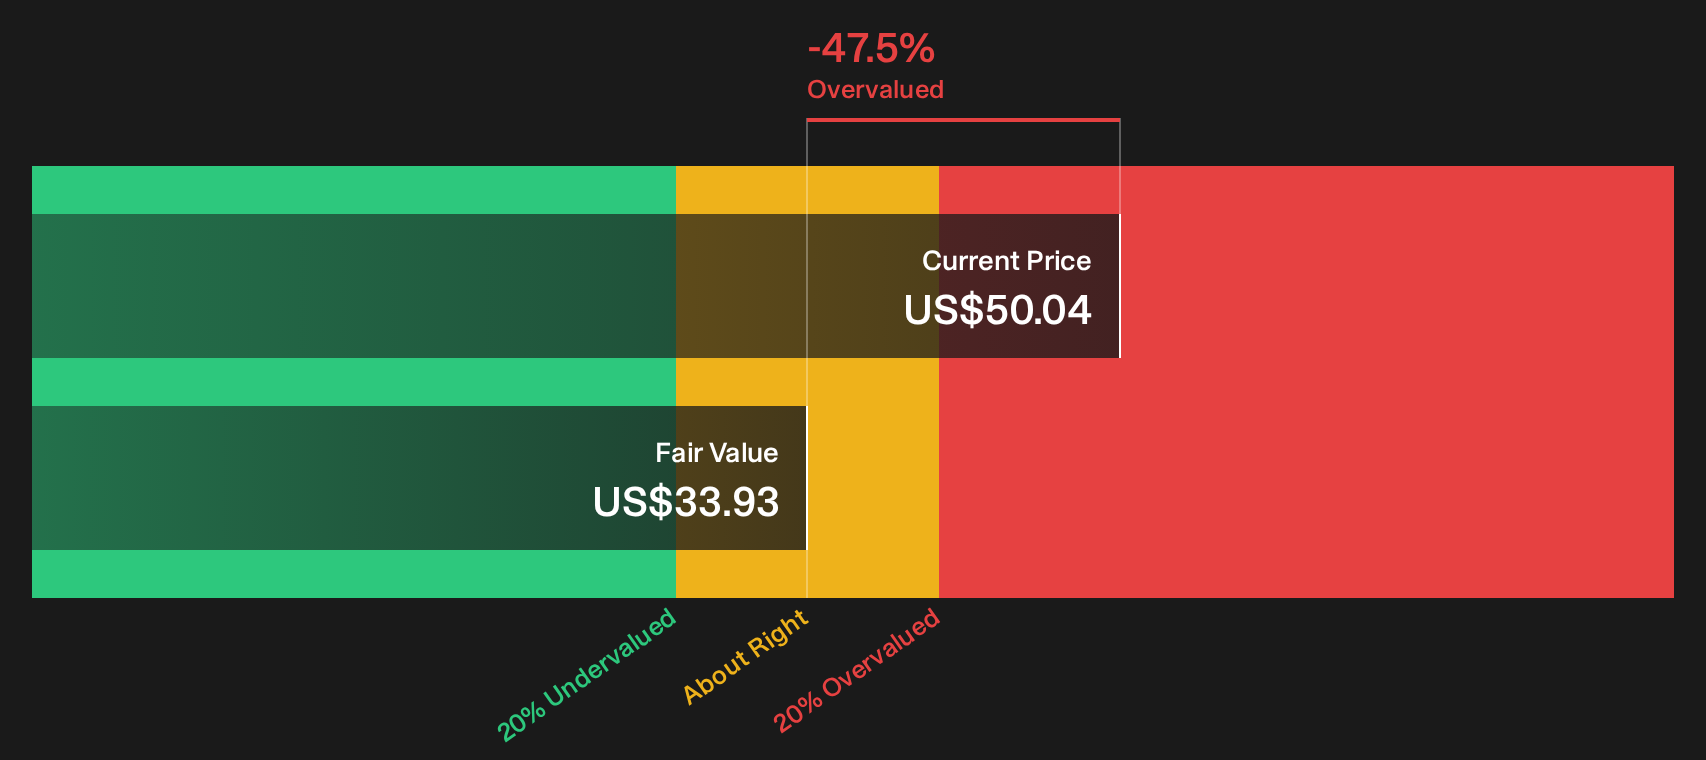
The equity story looks different when you shift from the analyst Narrative to the Simply Wall St DCF model. On that measure KB Home at $50.04 screens as overvalued against an estimated future cash flow value of $33.93. The gap is wide enough to make any investor pause and ask which set of assumptions feels more realistic.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out KB Home for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on KB Home so far. If you want to move quickly and decide where you stand, consider reviewing the 3 key rewards and 3 important warning signs to weigh the potential risks and rewards.
Looking for more investment ideas beyond KB Home?
If KB Home has sharpened your focus on valuation and risk, now is the time to widen your search and line up your next candidates.
- Hunt for quality at a discount by scanning companies that look attractively priced on both fundamentals and balance sheets with the 32 high quality undervalued stocks.
- Lock in potential income streams by reviewing stocks that feature robust yields and resilient payout profiles through the 6 dividend fortresses.
- Reduce portfolio stress by filtering for businesses with stronger balance sheets and fundamentals using the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com