
How $1b Buyback At Cirrus Logic (CRUS) Has Changed Its Investment Story
- Cirrus Logic recently increased its share repurchase authorization to a total of US$1 billion and reported second quarter fiscal 2027 sales of US$559.46 million, net income of US$114.74 million and diluted EPS from continuing operations of US$2.23.
- The expanded buyback, together with ongoing acquisition interest and revenue guidance of US$510 million to US$570 million for the next quarter, shows how Cirrus Logic is actively using its balance sheet to reshape capital allocation and its future business mix.
- We will now look at how Cirrus Logic's larger share repurchase plan could influence the existing investment narrative around cash generation.
Scan how Cirrus Logic's capital return story compares with other cash generative hardware plays by reviewing the hand picked list of solid balance sheet and fundamentals (23 results) in the same bracket.
Cirrus Logic Investment Narrative Recap
To stay invested in Cirrus Logic, you need to be comfortable with a story built on mixed signal leadership and heavy exposure to a few large smartphone customers, while management works to widen revenue streams into PCs and industrial uses. The analyst consensus Narrative on Simply Wall St expects modest top line growth with declining earnings, so execution on diversification matters. The latest quarter shows steady sales around US$559.46 million and net income of US$114.74 million, suggesting the core franchise remains intact. In the near term, customer concentration still looks like the single biggest operational risk.
In the short term, the key swing factor is how quickly new mixed signal products and PC designs contribute, especially after Cirrus Logic previously lowered FY27 PC expectations due to supply constraints and OEM timing issues. The new revenue outlook of US$510 million to US$570 million for the next quarter keeps attention on demand from key smartphone programs and any ongoing supply bottlenecks. If those headwinds persist or key customers adjust orders, earnings could be more volatile than the current steady run rate implies.
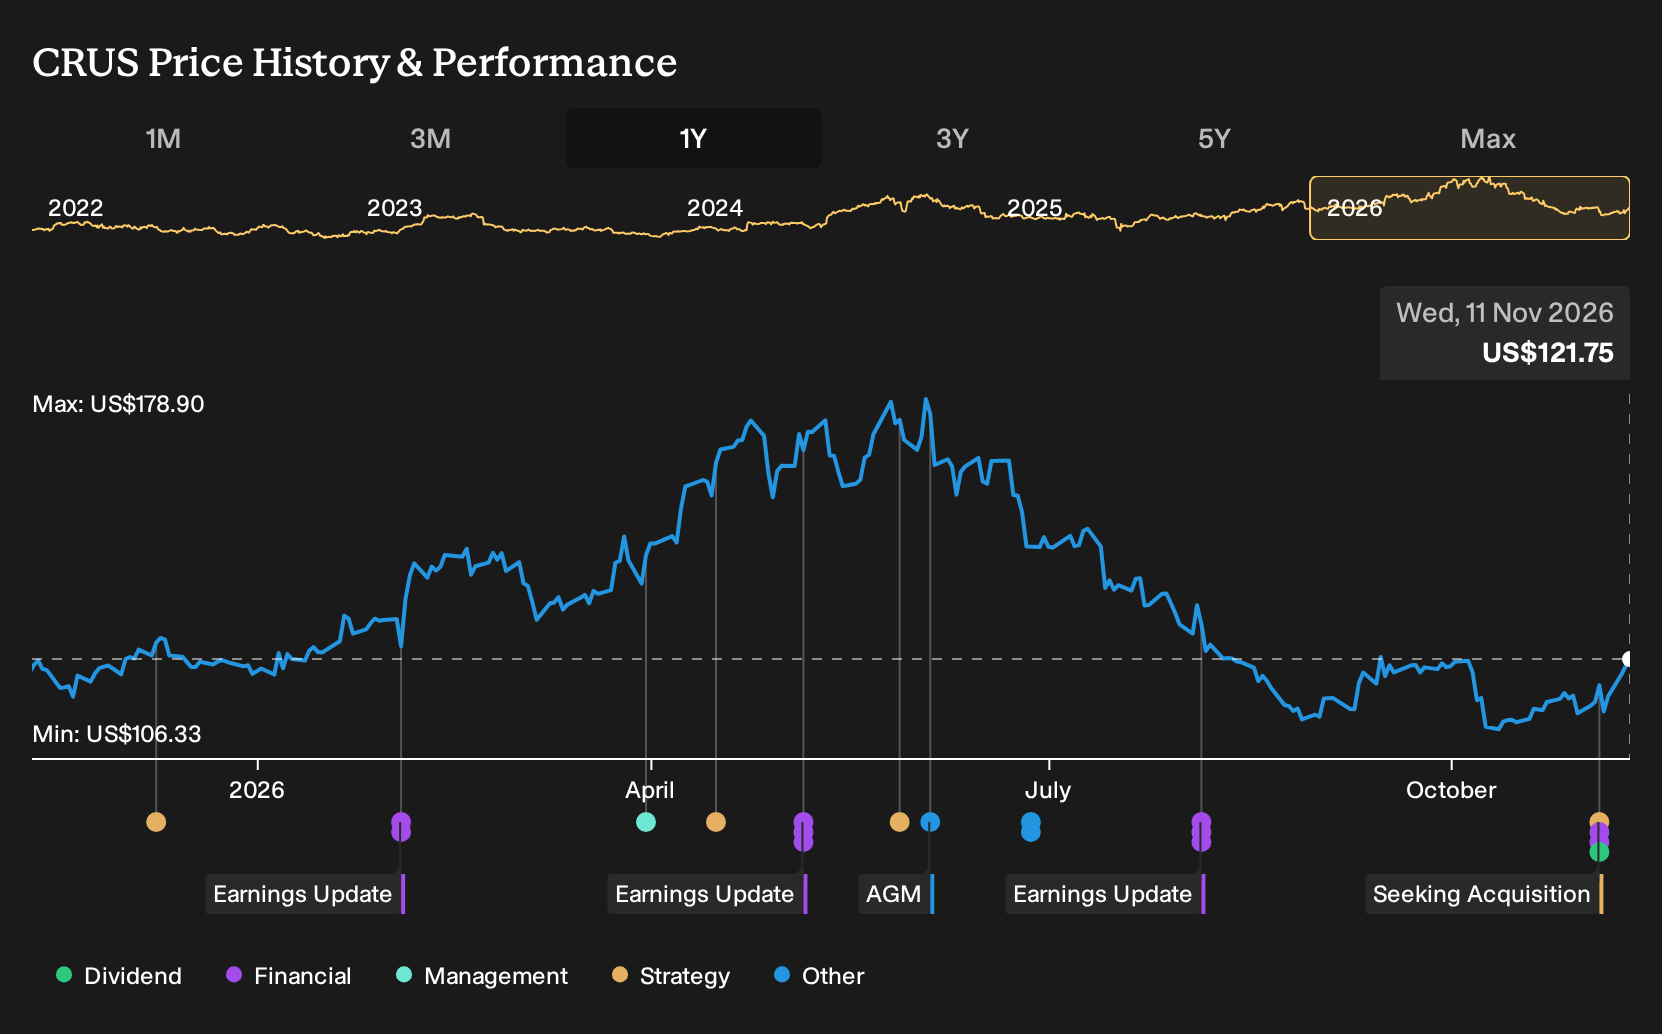
The expanded US$1b share repurchase plan is the clearest new signal. Management has already bought back 3,258,573 shares for US$404.54 million since May 2025, including 1,162,757 shares, or 2.3% of the float, between June 28 and October 30, 2026. The company has now added another US$500 million of capacity. That scale of capital return sits alongside a balance sheet that analysts on Simply Wall St view as supporting good value, with the stock trading at 14.7x P/E compared with a higher sector average.
For you as a shareholder, the buyback interacts directly with the earnings path described in the analyst consensus Narrative on Simply Wall St. Those forecasts call for revenue growing about 2.2% a year and earnings declining on average 7.6% a year over the next three years, so per share outcomes rely more on disciplined capital allocation than on rapid profit expansion. A US$1b authorization can offset some forecast EPS pressure if operating performance tracks those estimates. However, if customer concentration or PC delays weigh harder on cash generation, the scope to keep retiring stock at this pace could narrow.
Cirrus Logic's narrative projects US$2.2b revenue and US$385.2 million earnings by 2029. Analysts are building this on 2.1% yearly revenue growth and an earnings decline of about US$45.4 million from current earnings of US$430.6 million to the 2029 consensus level.
Uncover why Cirrus Logic's fair value indicates a 16% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Cirrus Logic’s acquisition appetite as the real swing factor. They were already pencilling in revenue of about US$2.3b and earnings near US$425.0 million by 2029 before this US$1b buyback and M&A push. Their view is more upbeat than consensus, and these fresh moves may eventually shift both narratives.
Explore 7 other Cirrus Logic fair value estimates, including one that suggests as much as 108% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cirrus Logic research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Cirrus Logic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cirrus Logic's overall financial health at a glance.
Looking for more Cirrus Logic style ideas?
If the Cirrus Logic story has you thinking about where else solid balance sheets and consistent cash generation might show up, it can help to widen the search with a few focused screens on Simply Wall St.
- For investors who want financial strength and cleaner balance sheets, start with a curated 30 resilient stocks with low risk scores that filters for resilience before anything else.
- If value is the main priority and you prefer companies where quality and pricing both matter, scan the 32 high quality undervalued stocks to see which stocks currently line up with that profile.
- For readers aiming to pair income with durability, filter through a hand picked 6 dividend fortresses that focuses on higher yields supported by underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com